We had a pretty rough week in the markets with many risk assets selling off on Friday. The Fed held at 3.75-4% as everyone expected; by Friday the market had about 85% priced in a December hike. Warsh also said the Fed will hold fewer rate meetings from 2027.
Microsoft beat and barely got rewarded for it, Alphabet sold off on a miss and its spending plans, Amazon showed $42.4 billion of negative free cash flow, and Intel’s guidance set off a chip rout on Friday. NBC put the damage at about $1 trillion of tech market value.
Oil had its week. A tanker got hit by limpet mines in the Strait of Hormuz; the Houthis kept firing at Saudi Arabia, oil settled at six-month highs, and Chevron and Exxon hit all-time highs.
Crypto got the biggest hack in its history, with Binance losing about $6 billion, suspending withdrawals. Midterms are on Tuesday, with prediction markets favoring the Democrats.
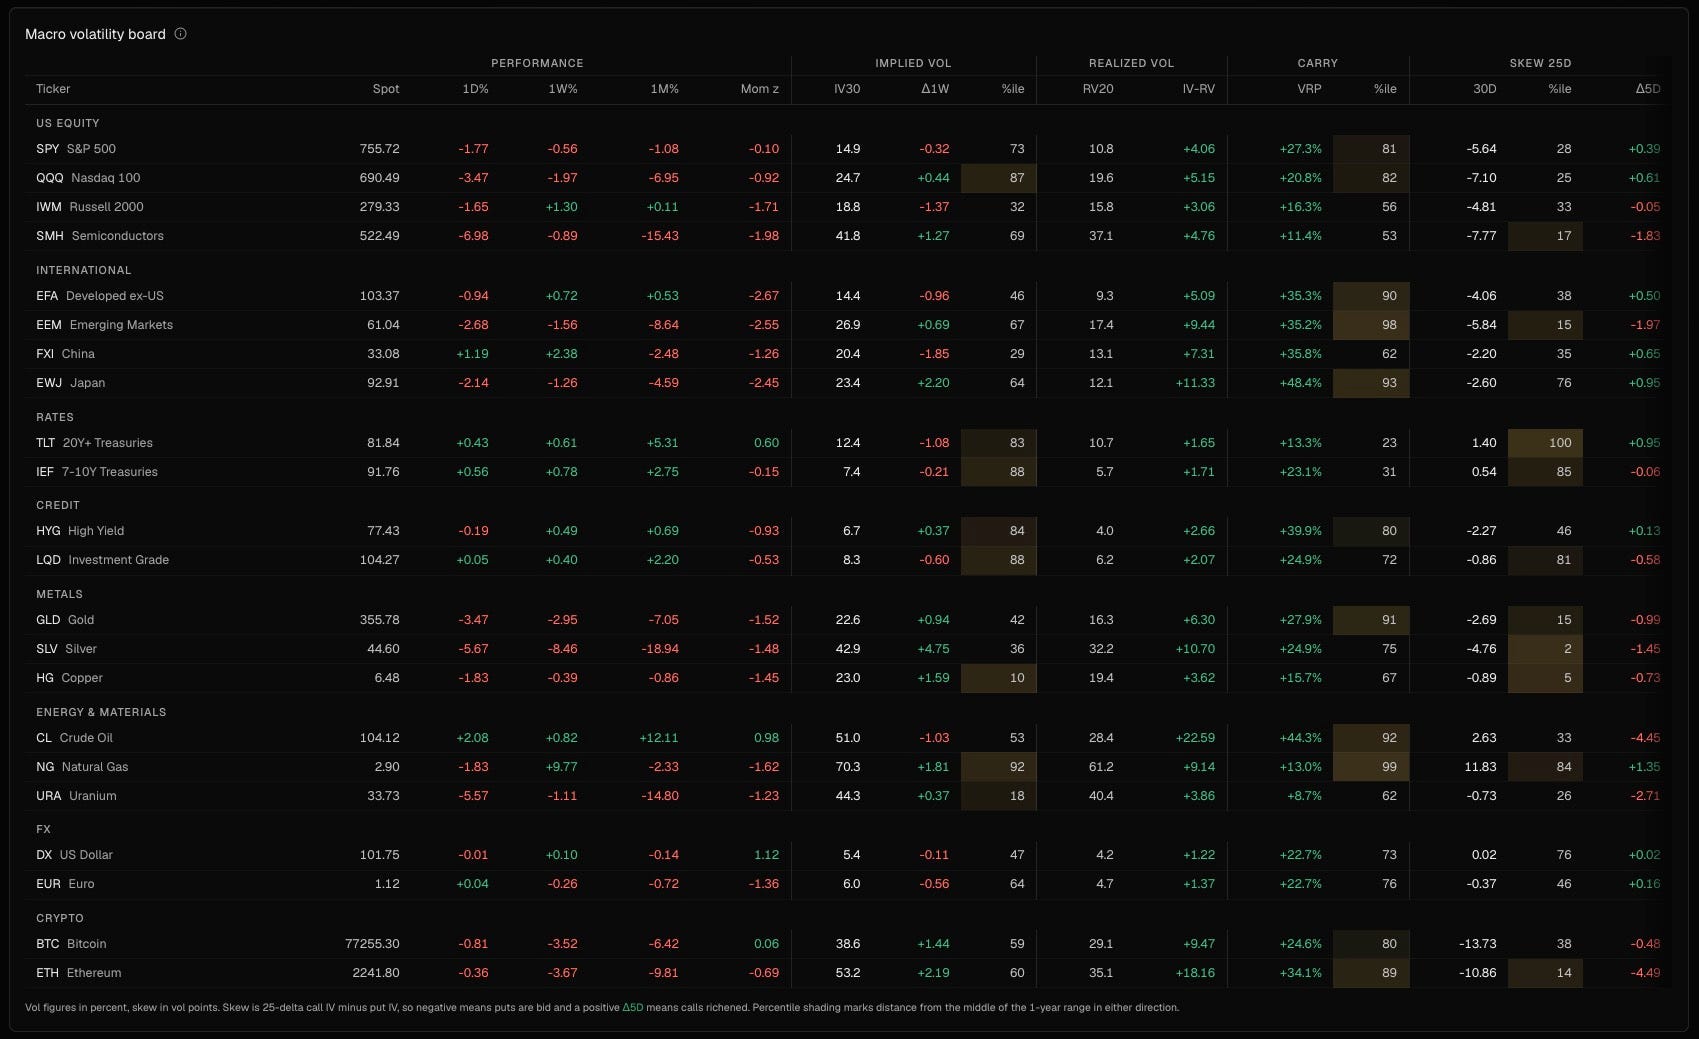
As a reminder, all data are coming from Tradingriot.com, those of you that decide to subscribe will get access to historical options and futures data for equities, commodities, rates, FX & digital assets. Distilled into daily signals, actionable strategies, and a pre-made portfolio to follow.
If you are interested in getting free market updates during the week, you can join a free read-only Discord.
Equities
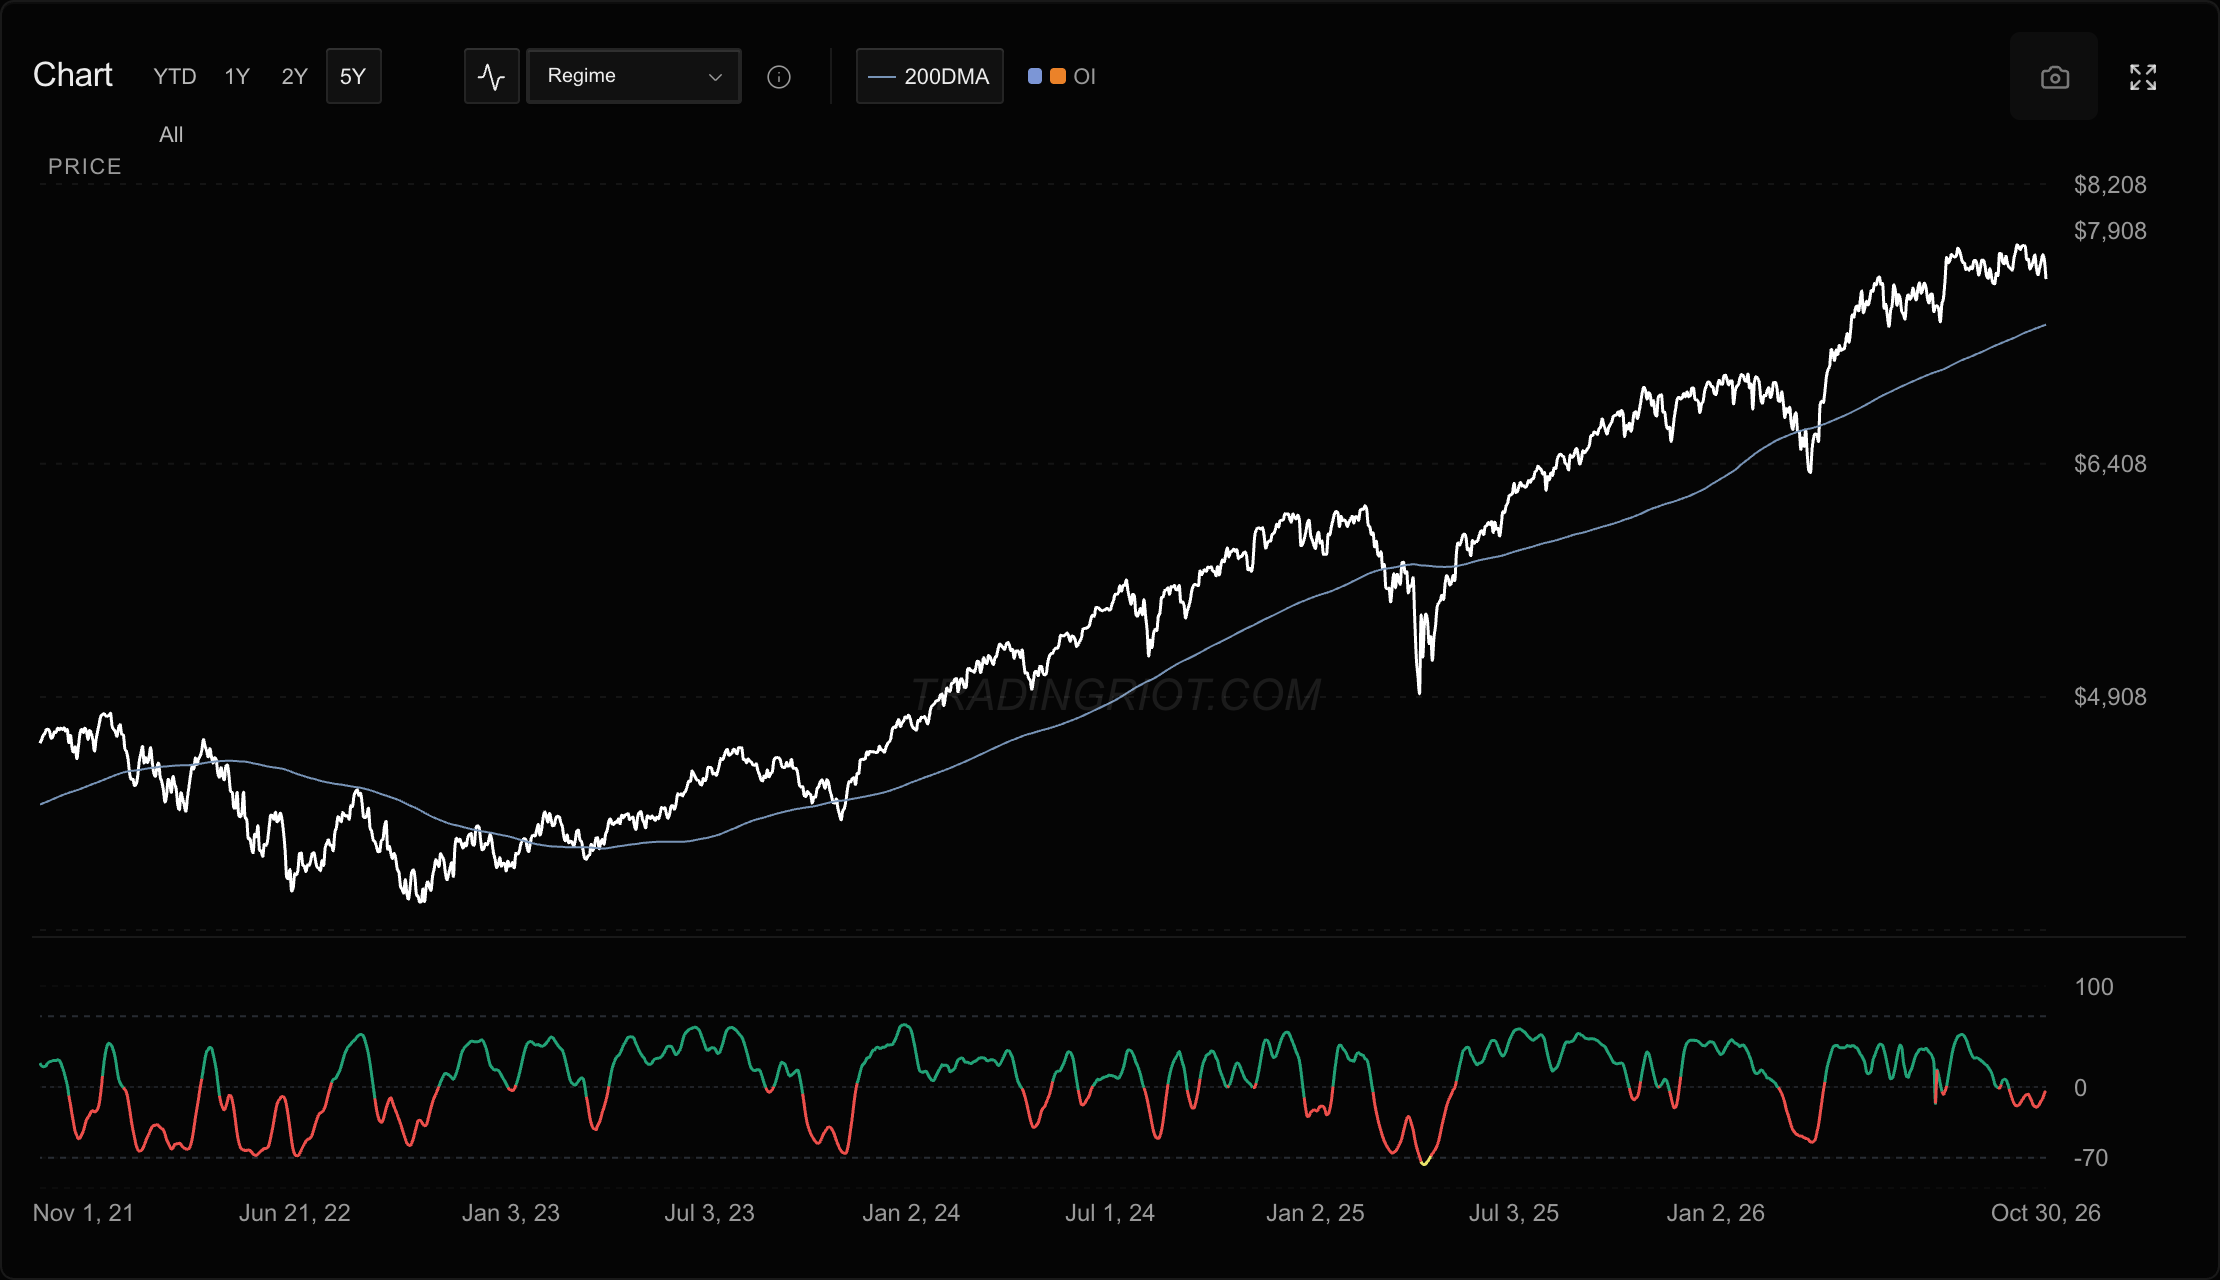
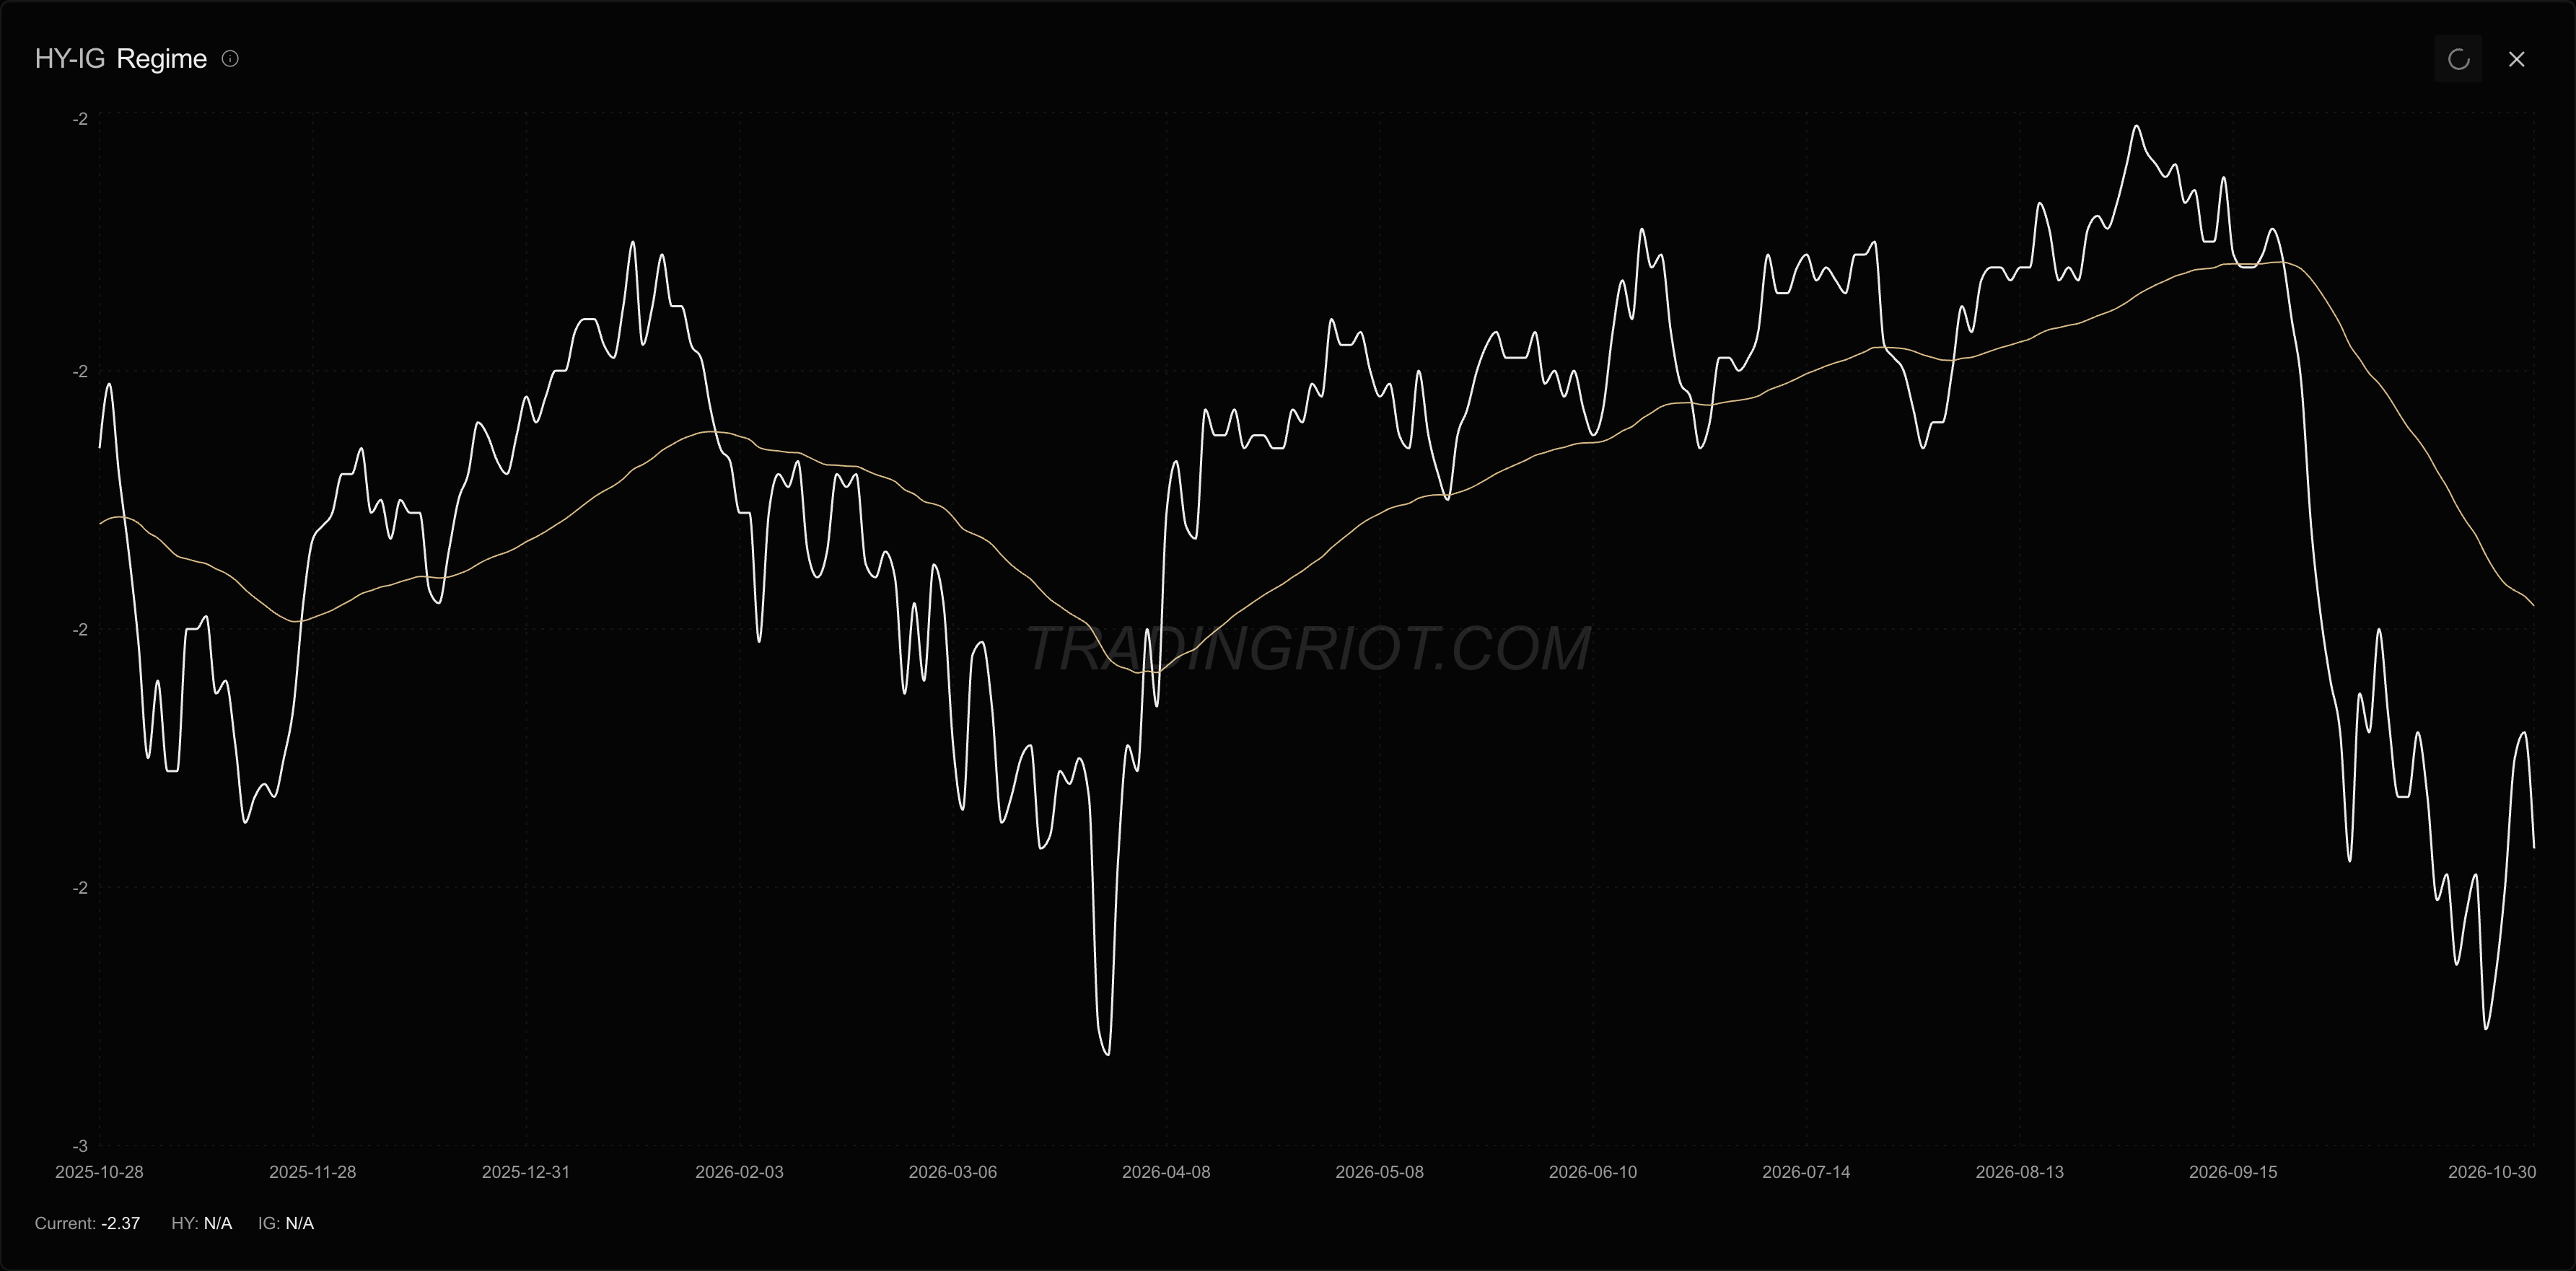
Earlier this month there was a large divergence between SPX price action and the composite regime on Tradingriot.com which tracks VIX, credit, breadth, and momentum.
Some of that gap has closed, partly through price and partly because breadth has improved, but it’s still there. And while I don’t think chasing shorts makes much sense here, it also does not look too appealing to bid yet.
Looking at VIX, the market definitely looks nervous but not scared yet.
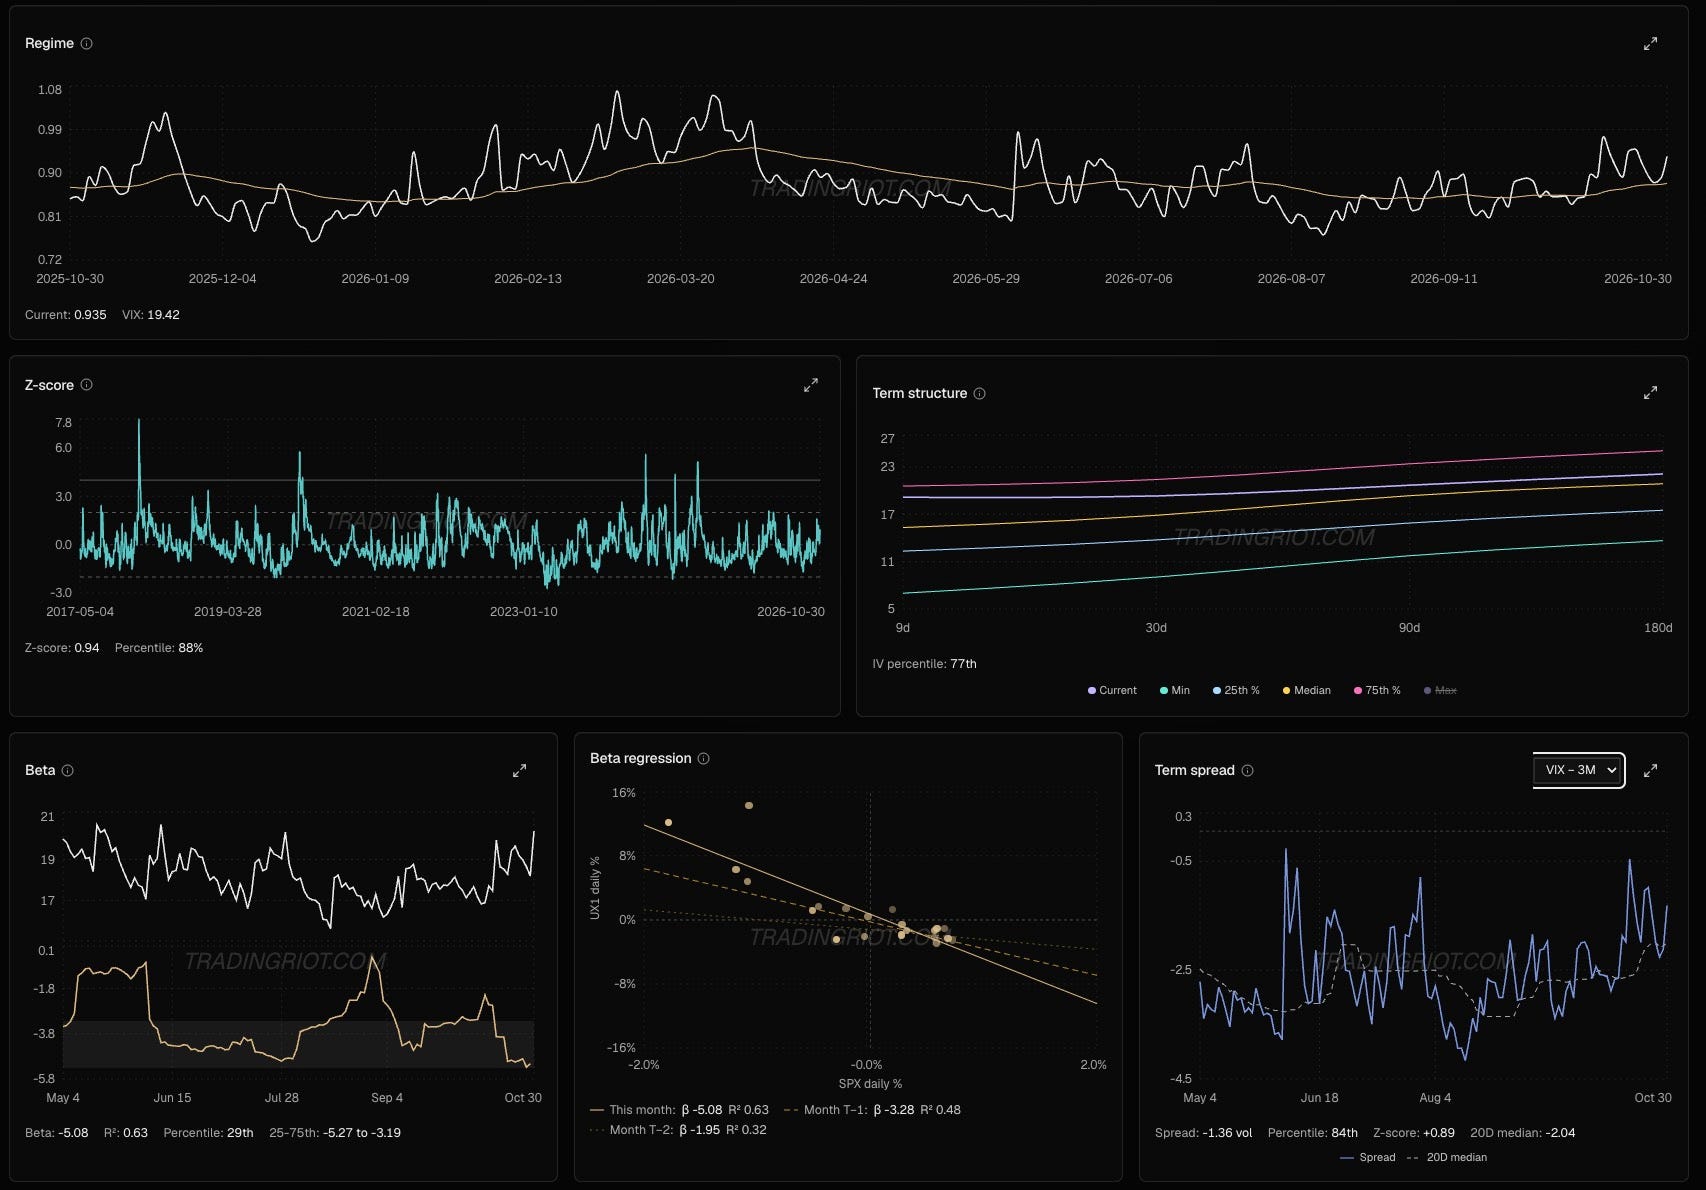
Credit was a main warning early sign at the end of September as it went risk-off and is nearing the March panic lows.
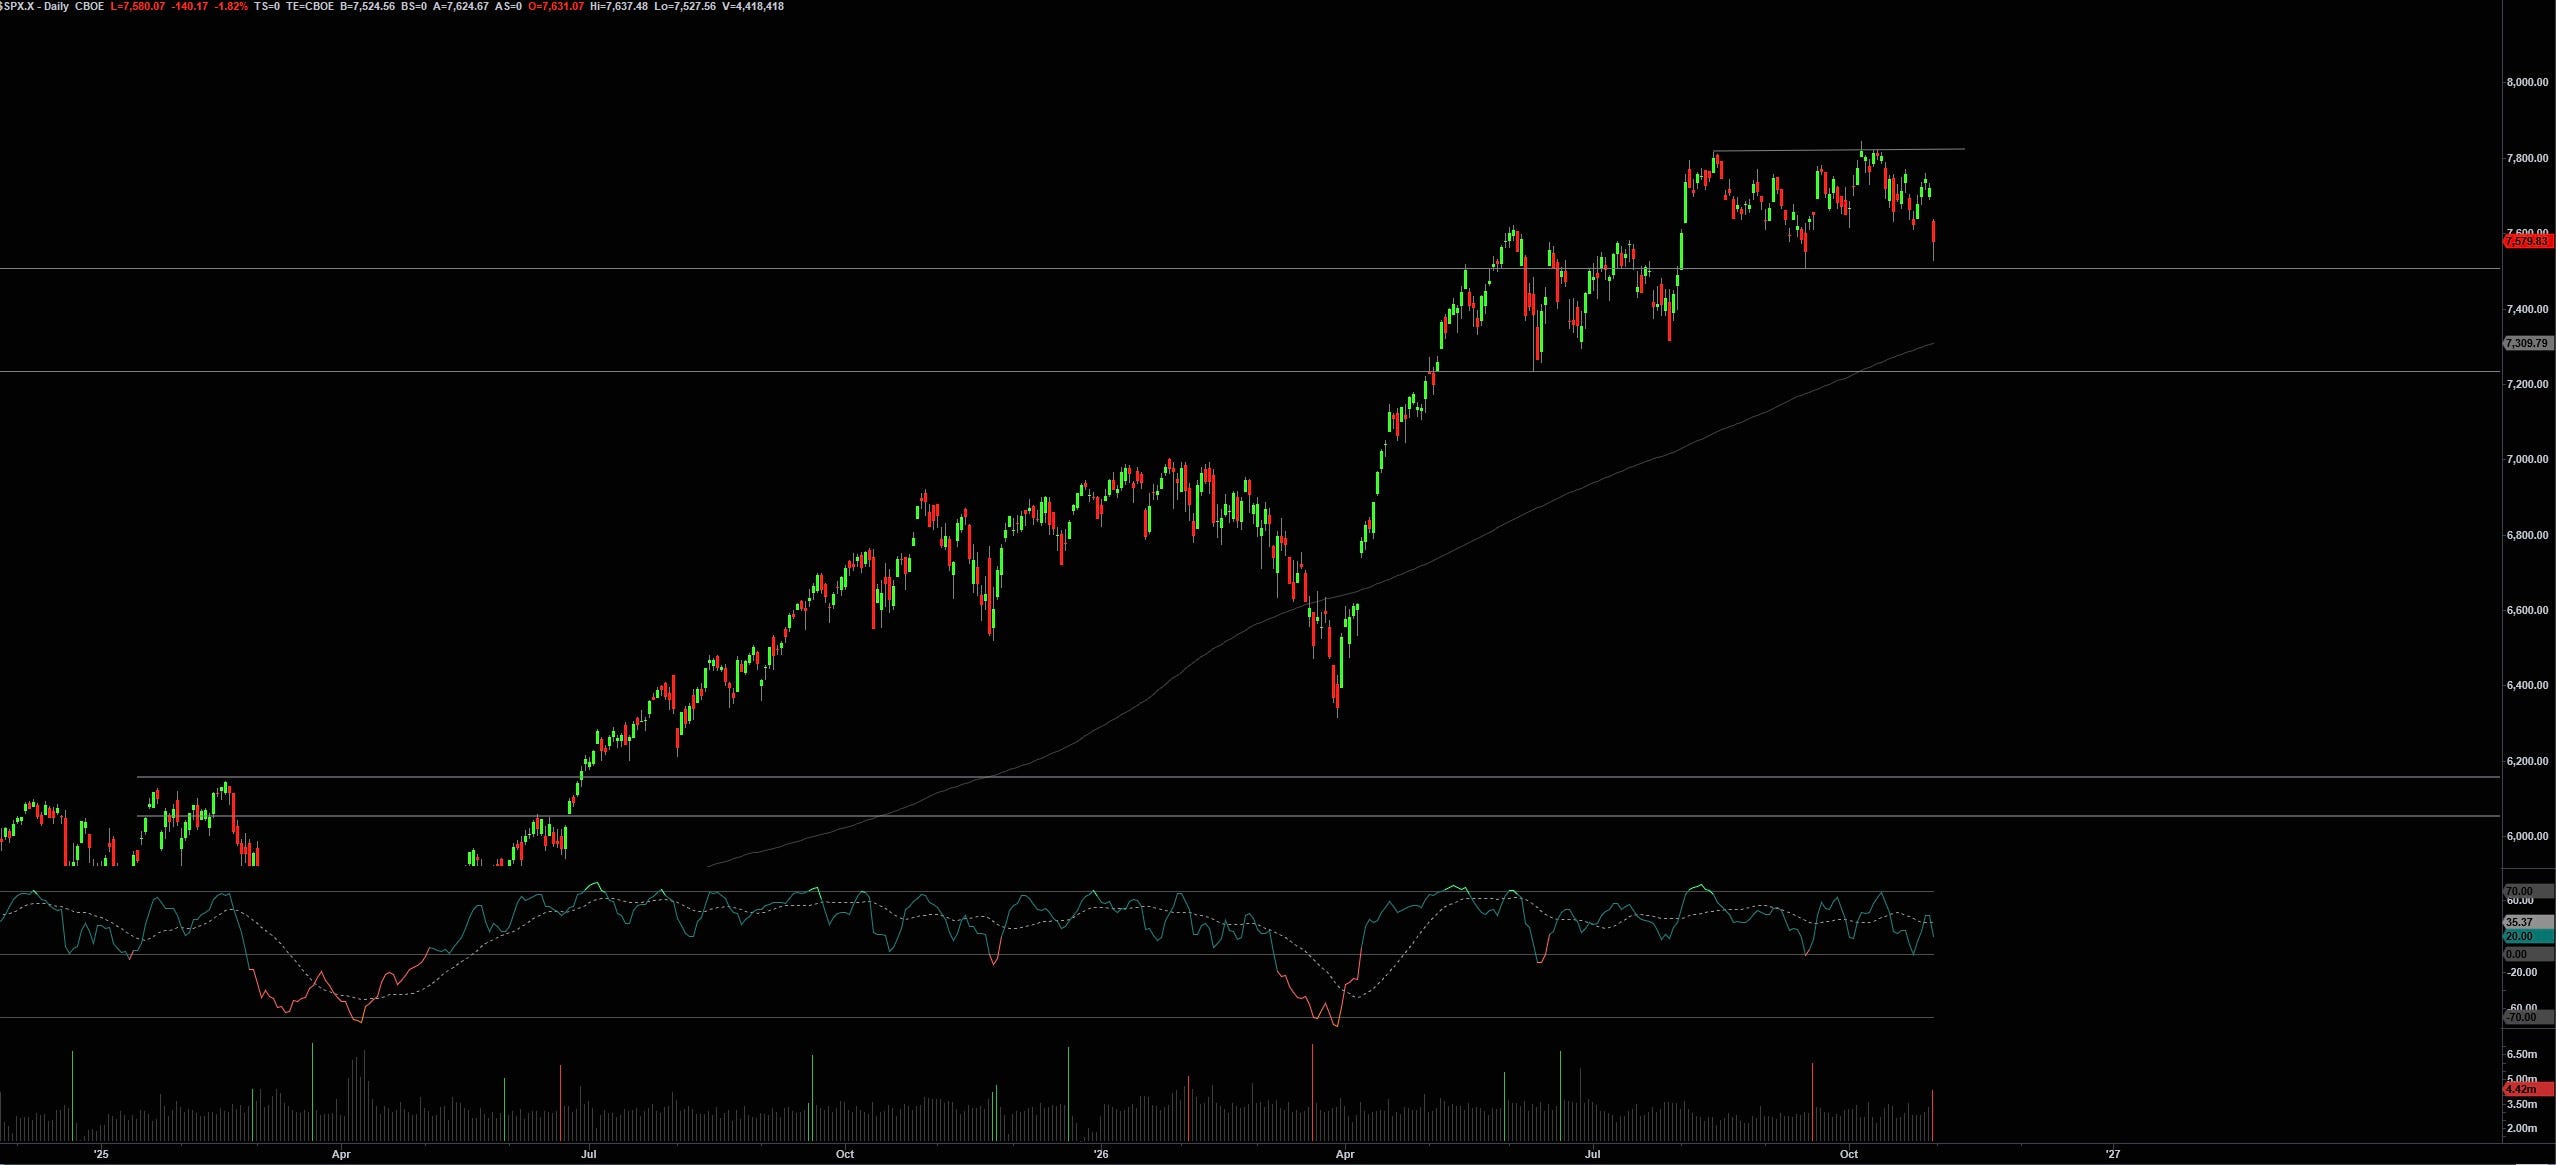
Friday’s sell-off came close to tapping the August lows, which is the first area of support I am looking at. If things are going to get worse between 7200 and 7300, it will be another clear support area with 200-DMA.
Sectors
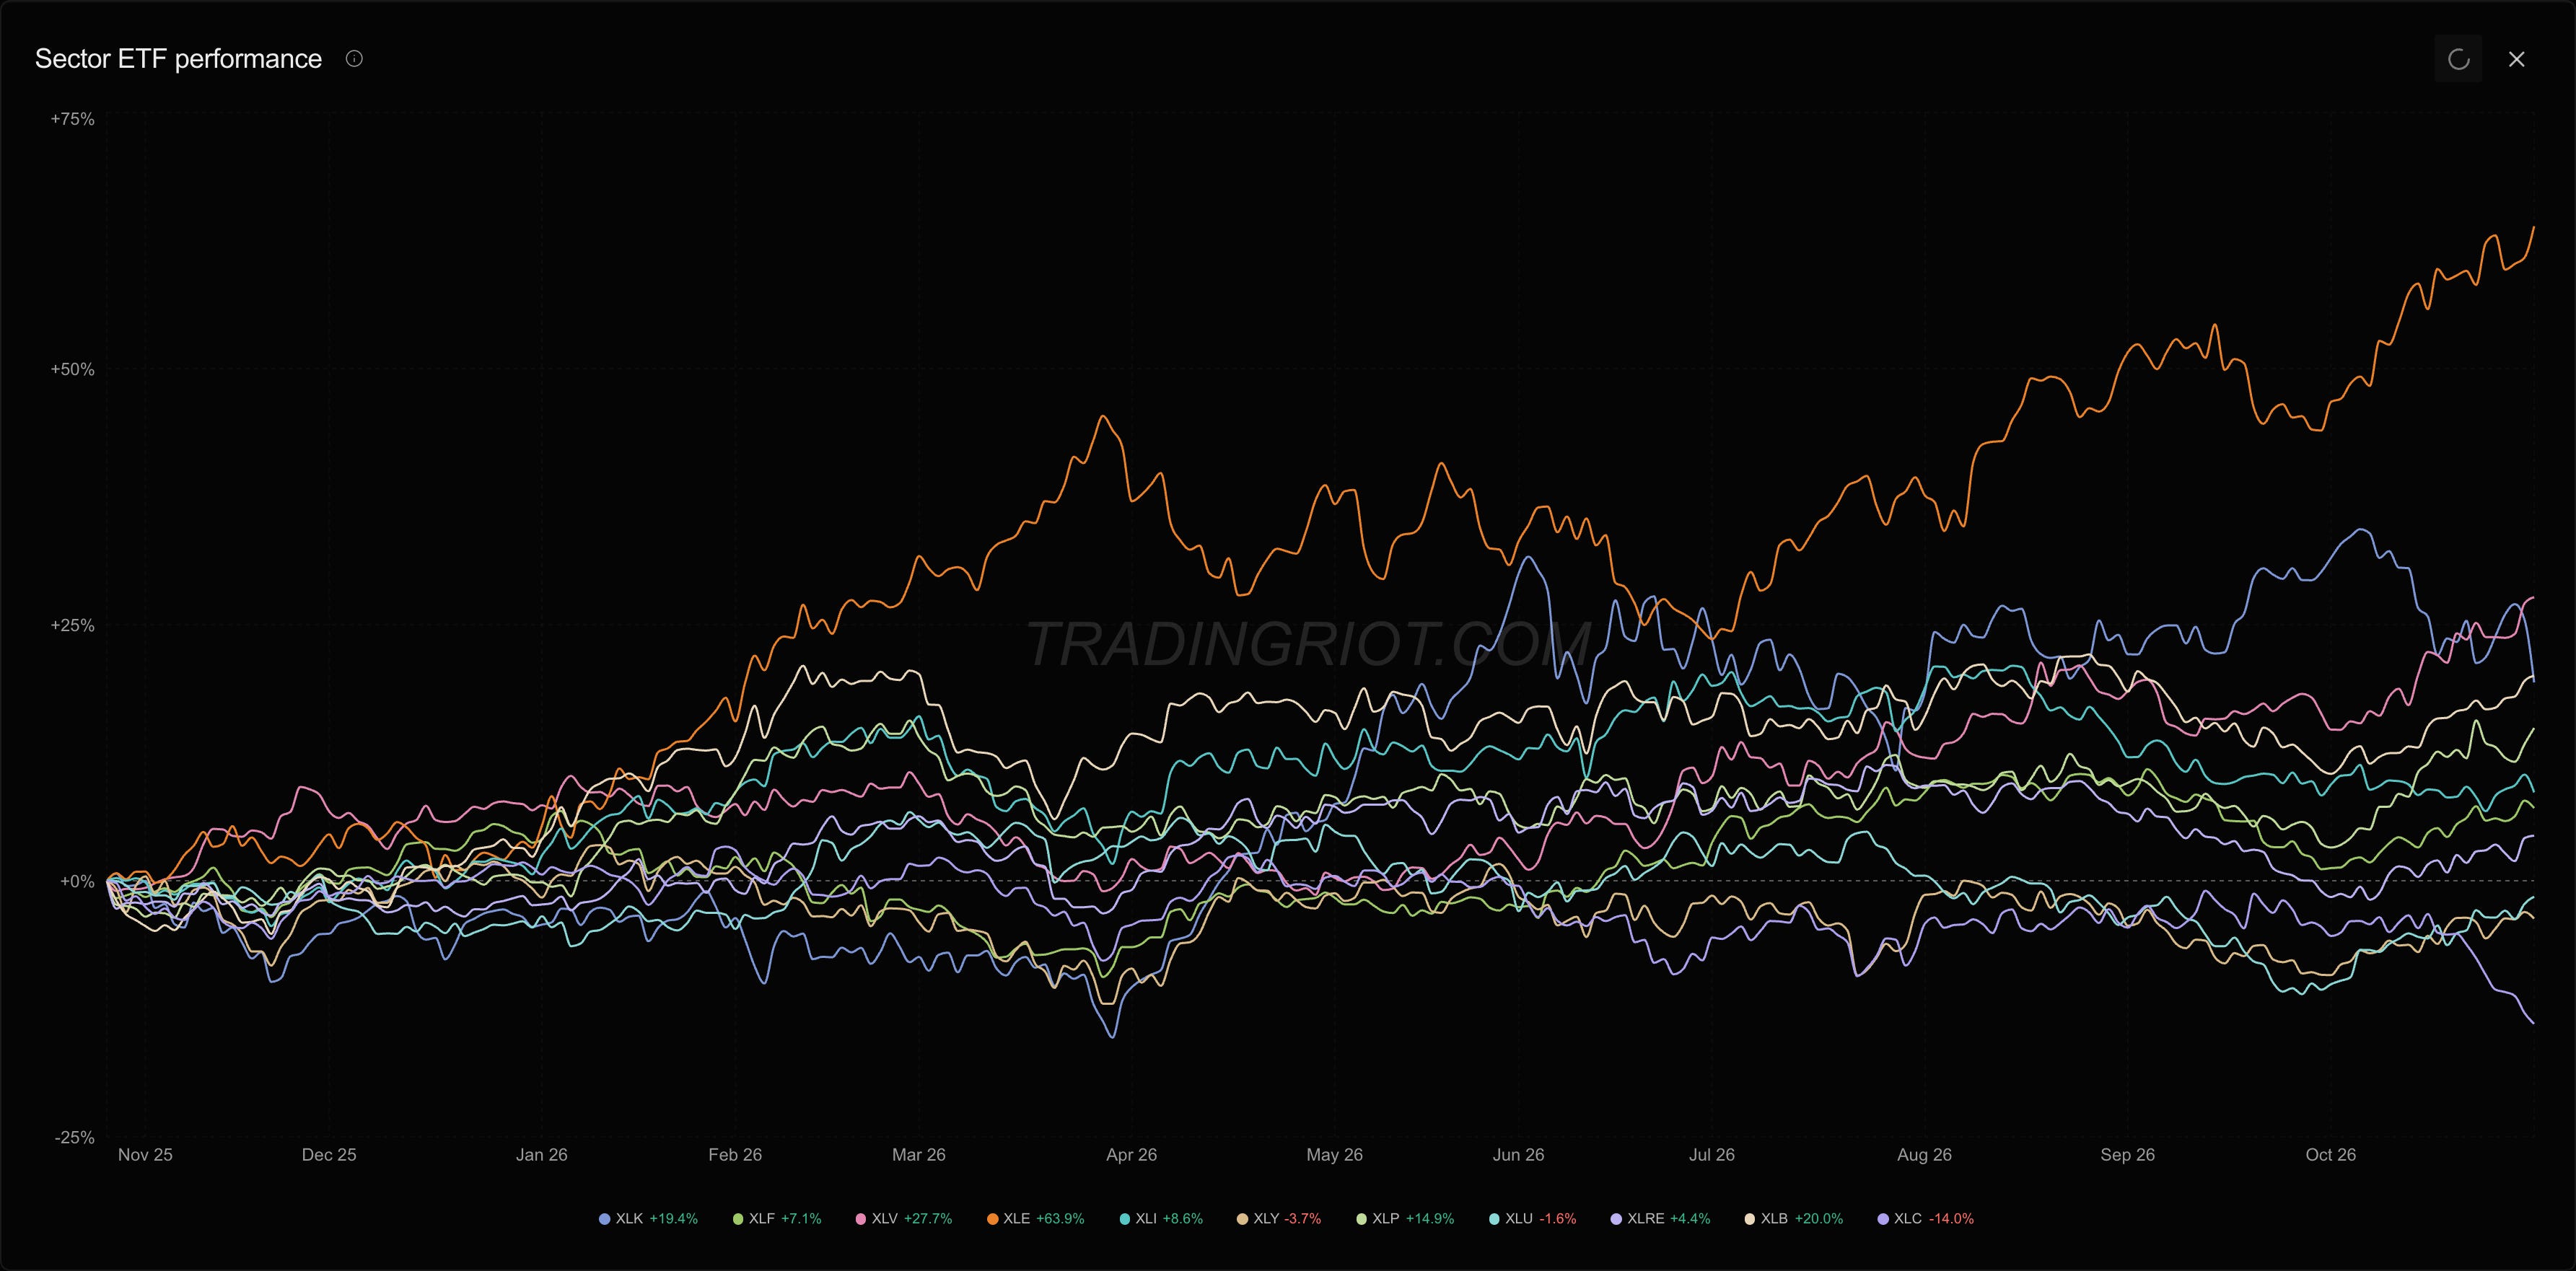
As probably all of you know, under the surface this has been a rotation out of tech. XLE, XLP, and XLV are each up about 11% over that time, while XLK and XLC are down about 9% and SMH 15%.
This week nine of the eleven sector SPDRs were still up, and IWM gained while QQQ fell.
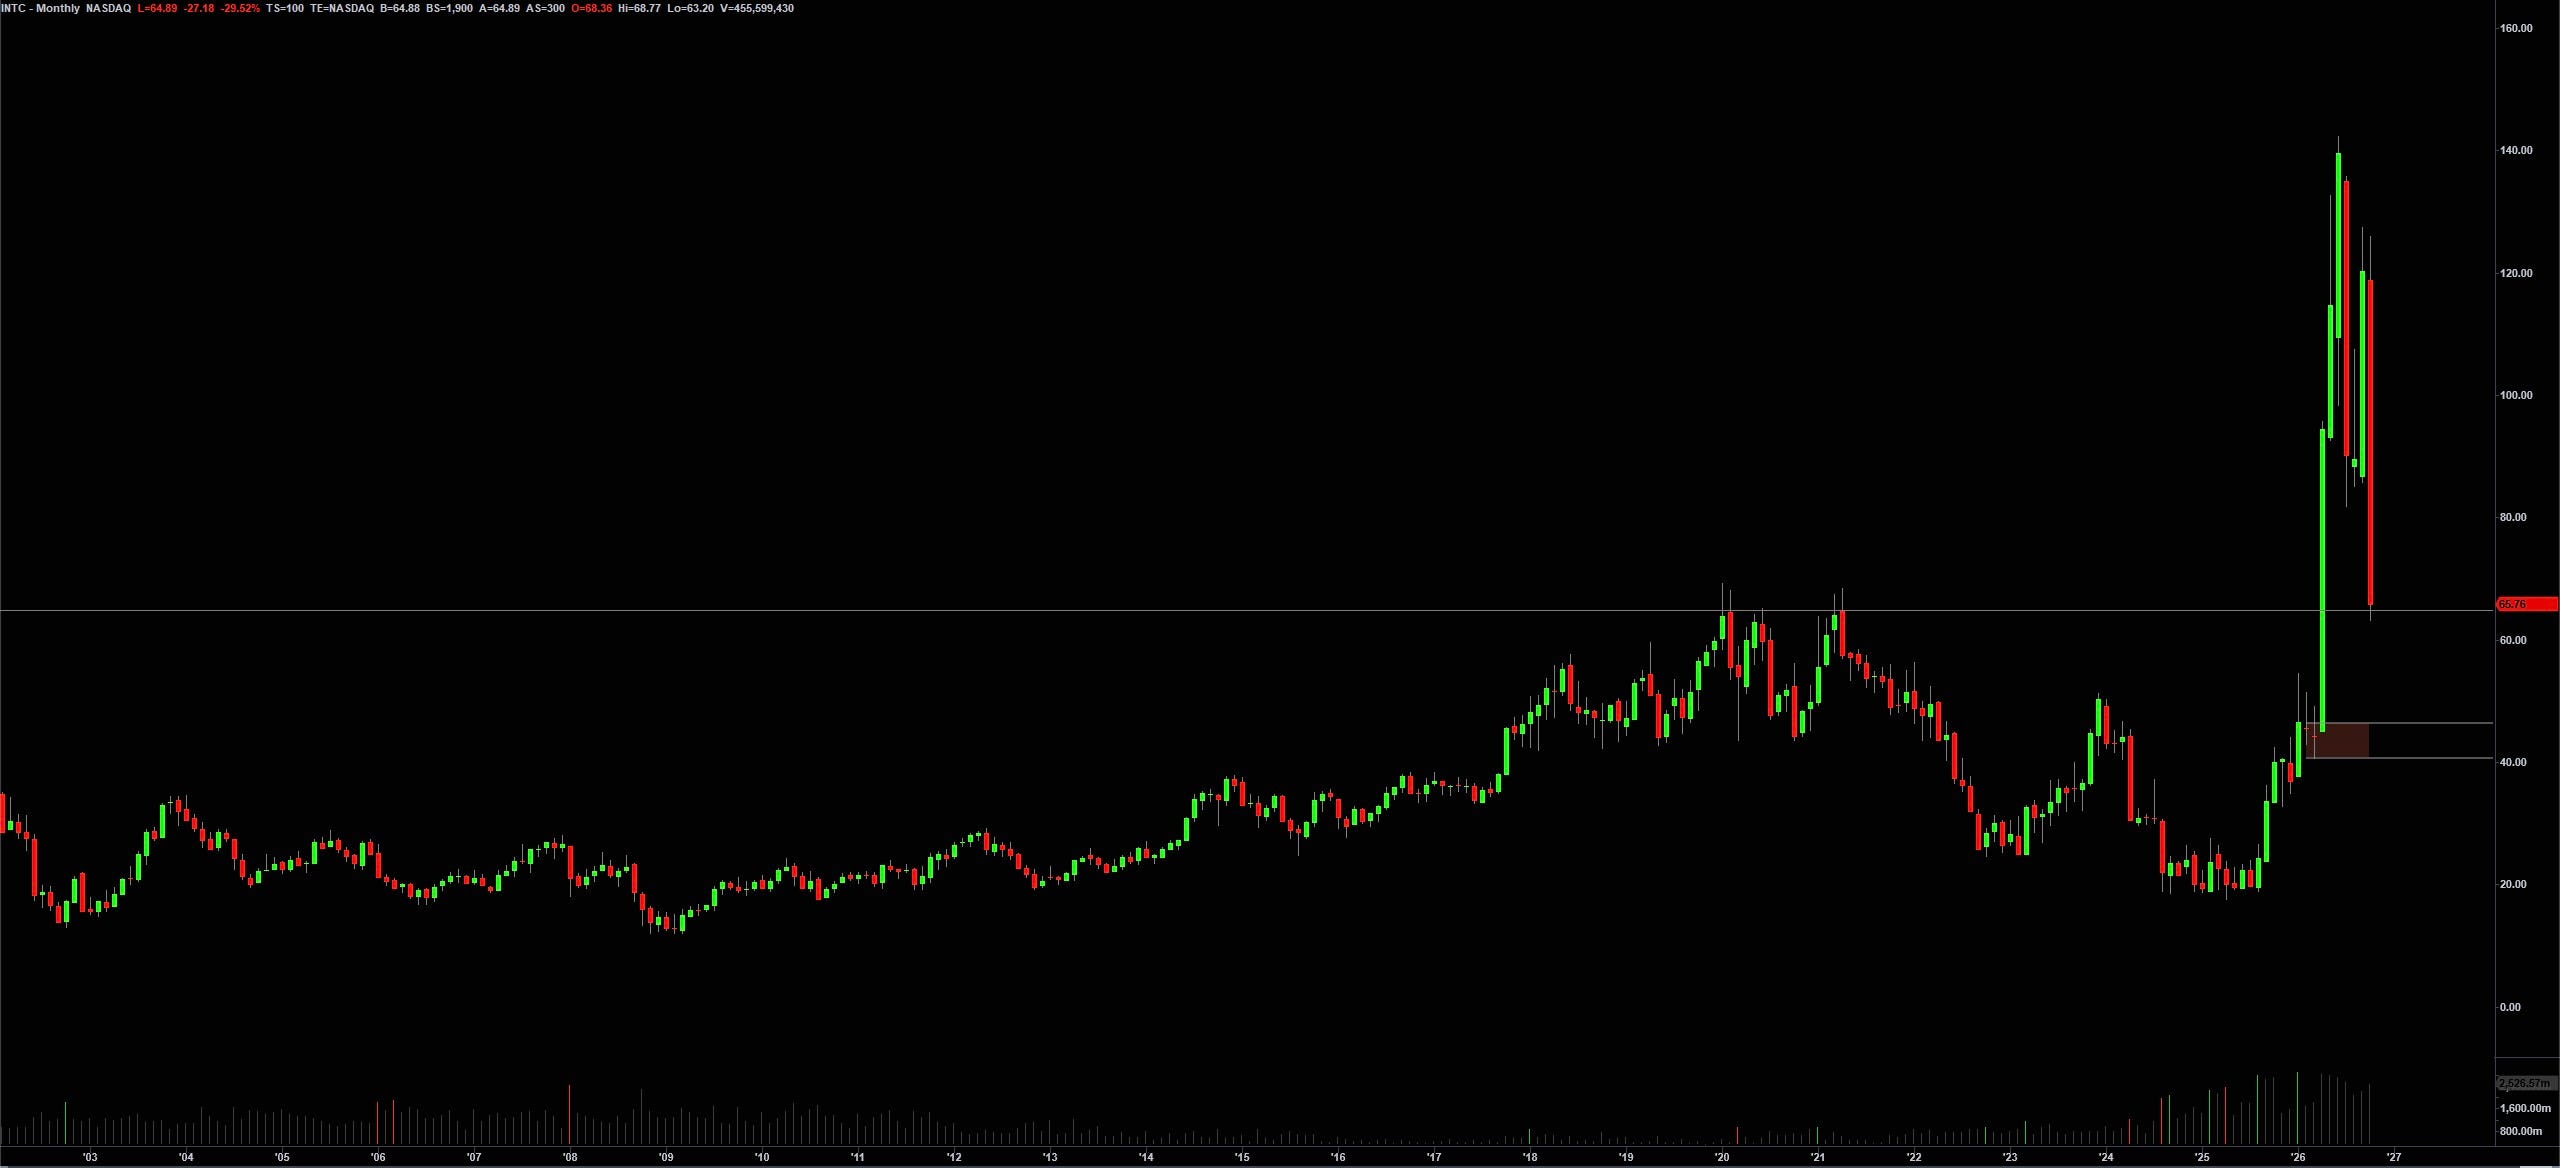
The damage was concentrated in the AI trade. Intel’s ~30% drop on Friday was reported as its worst day since the 1970s. This type of panic usually gives a good opportunity, and while I don’t expect this to bounce back to ATH in a straight line, the price is sitting at an interesting spot now, testing the prior ATH.
Earnings
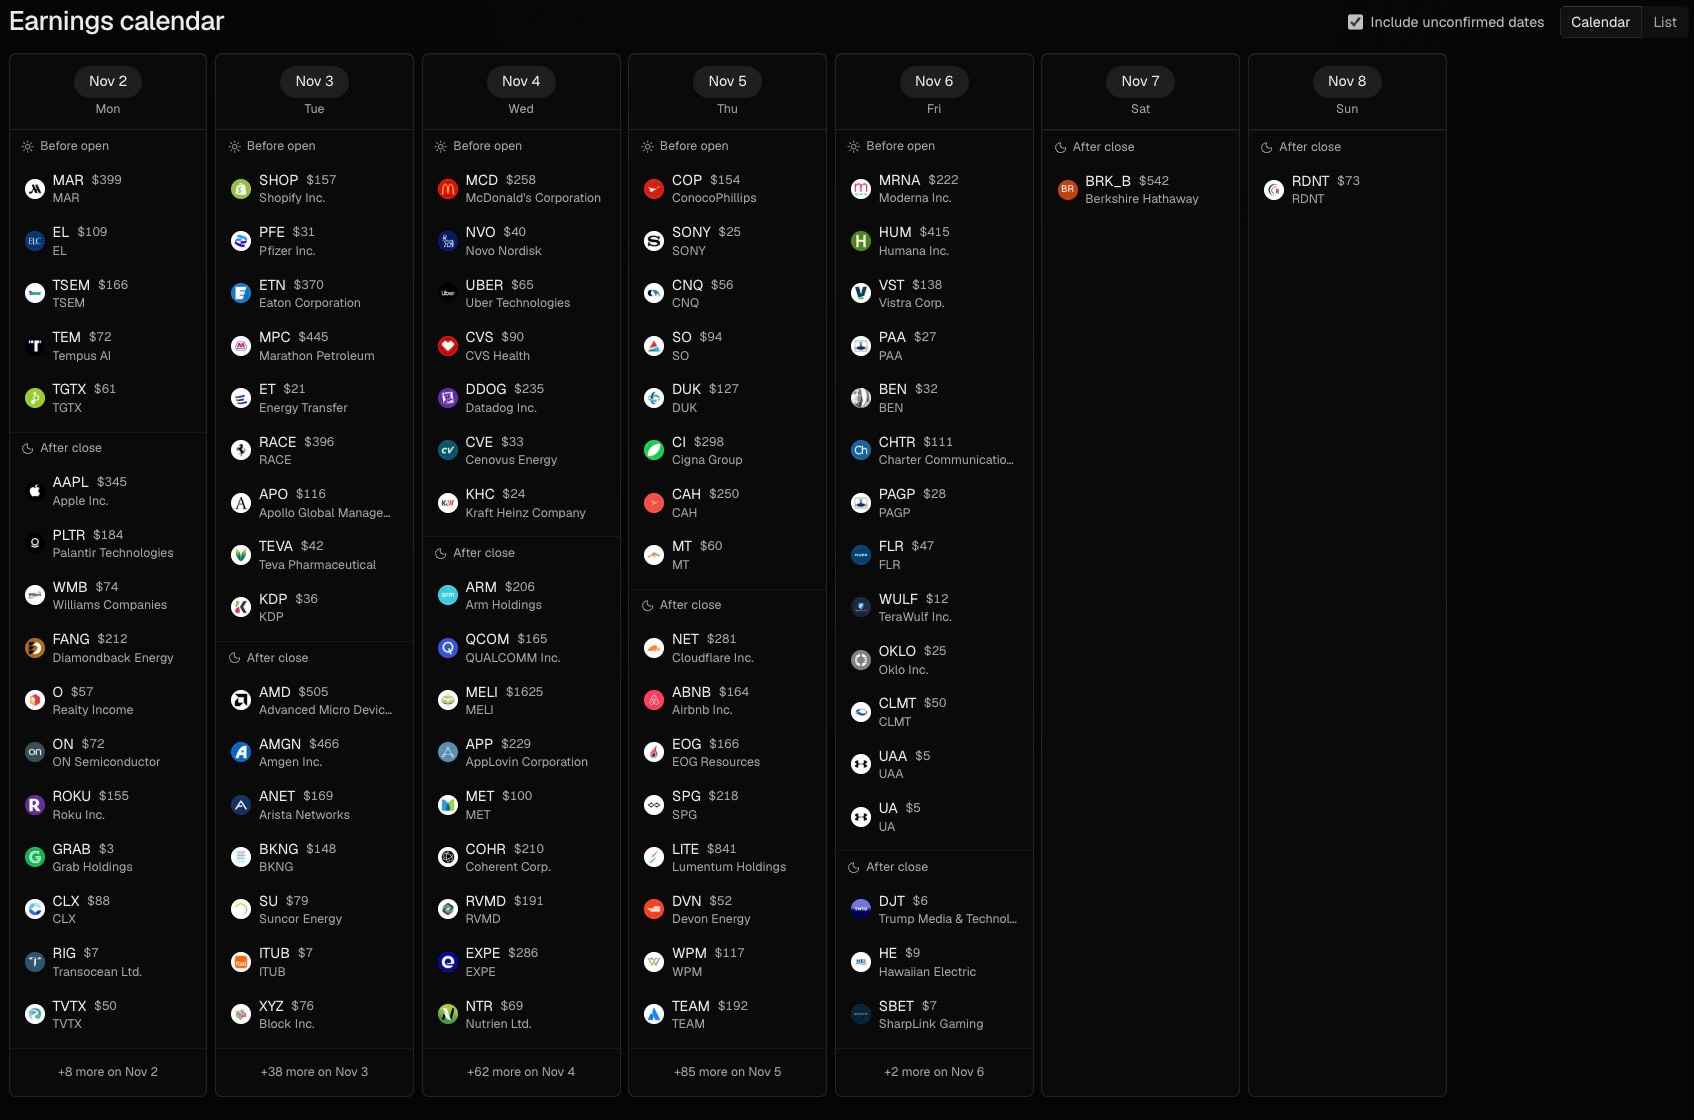
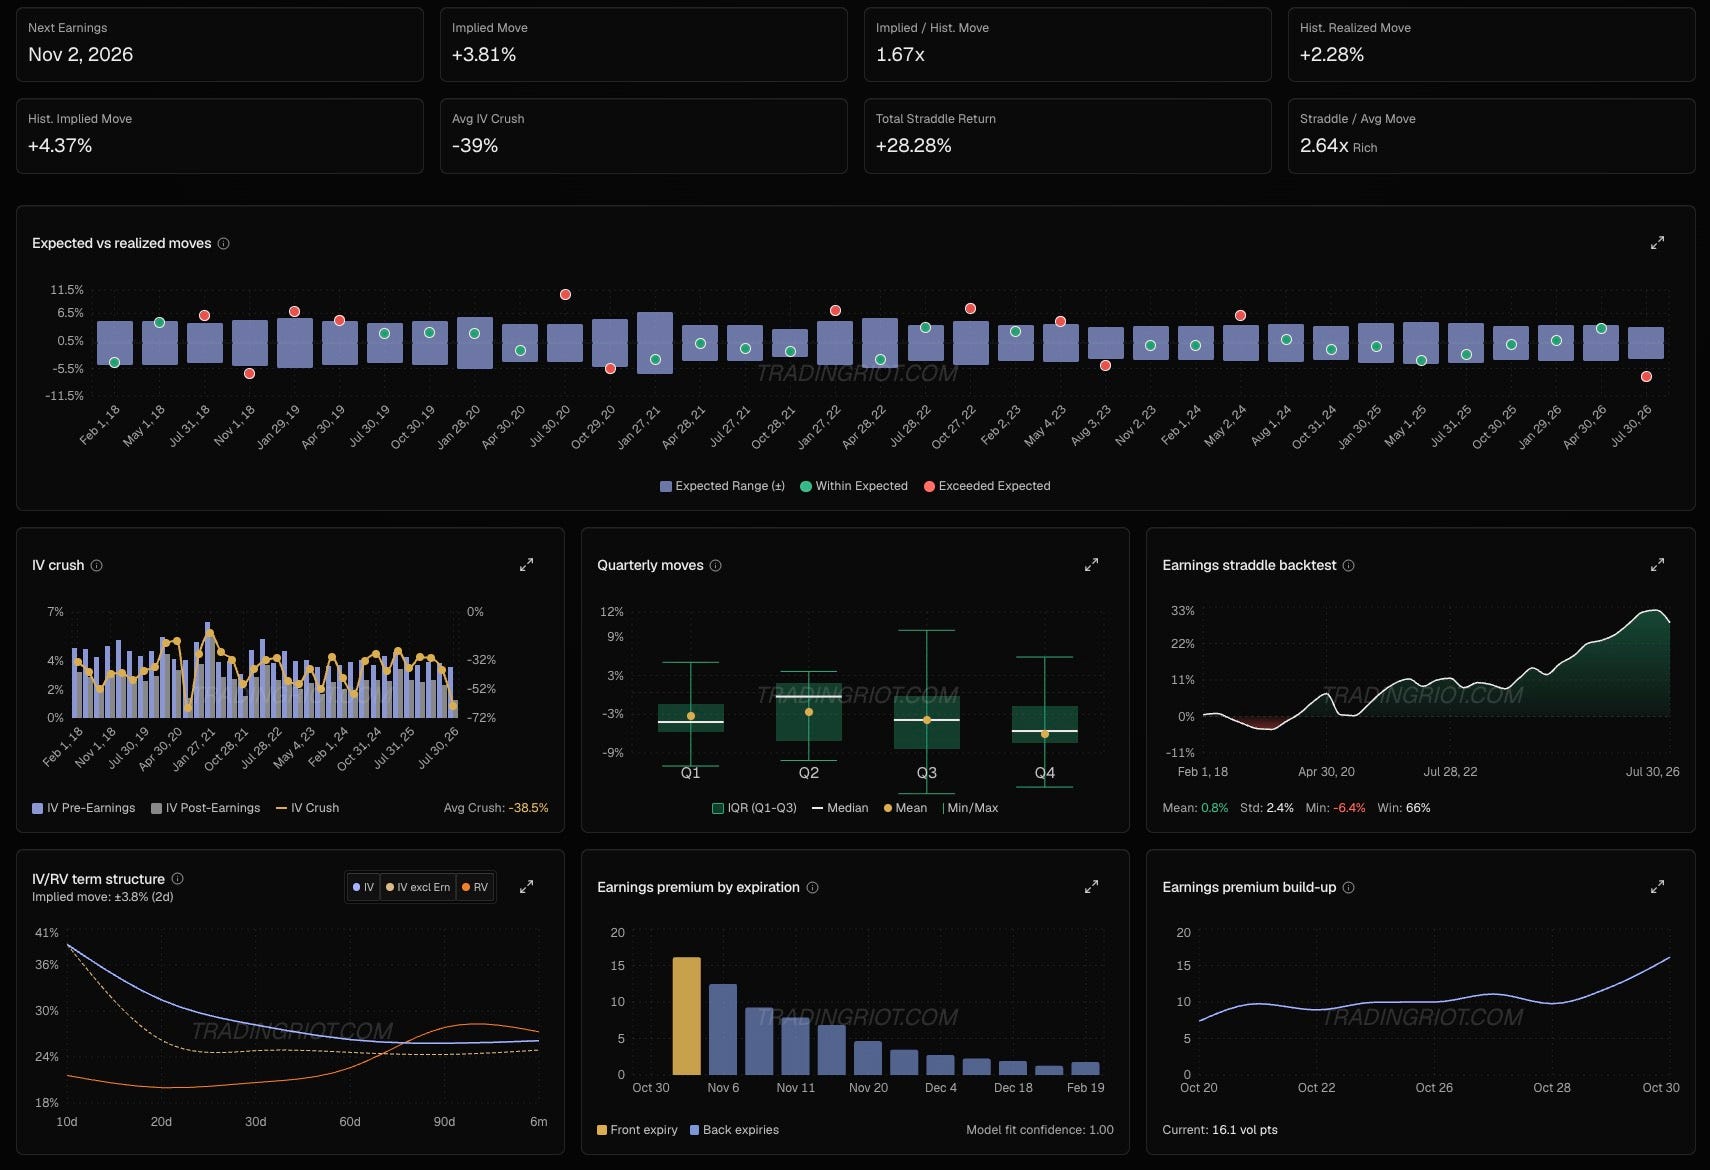
Plenty of major names are reporting next week, which will surely continue to shake things up. Apple is priced well above its history, and Palantir is well below. AMD and Arm are priced about in line with theirs.
Systematic portfolio
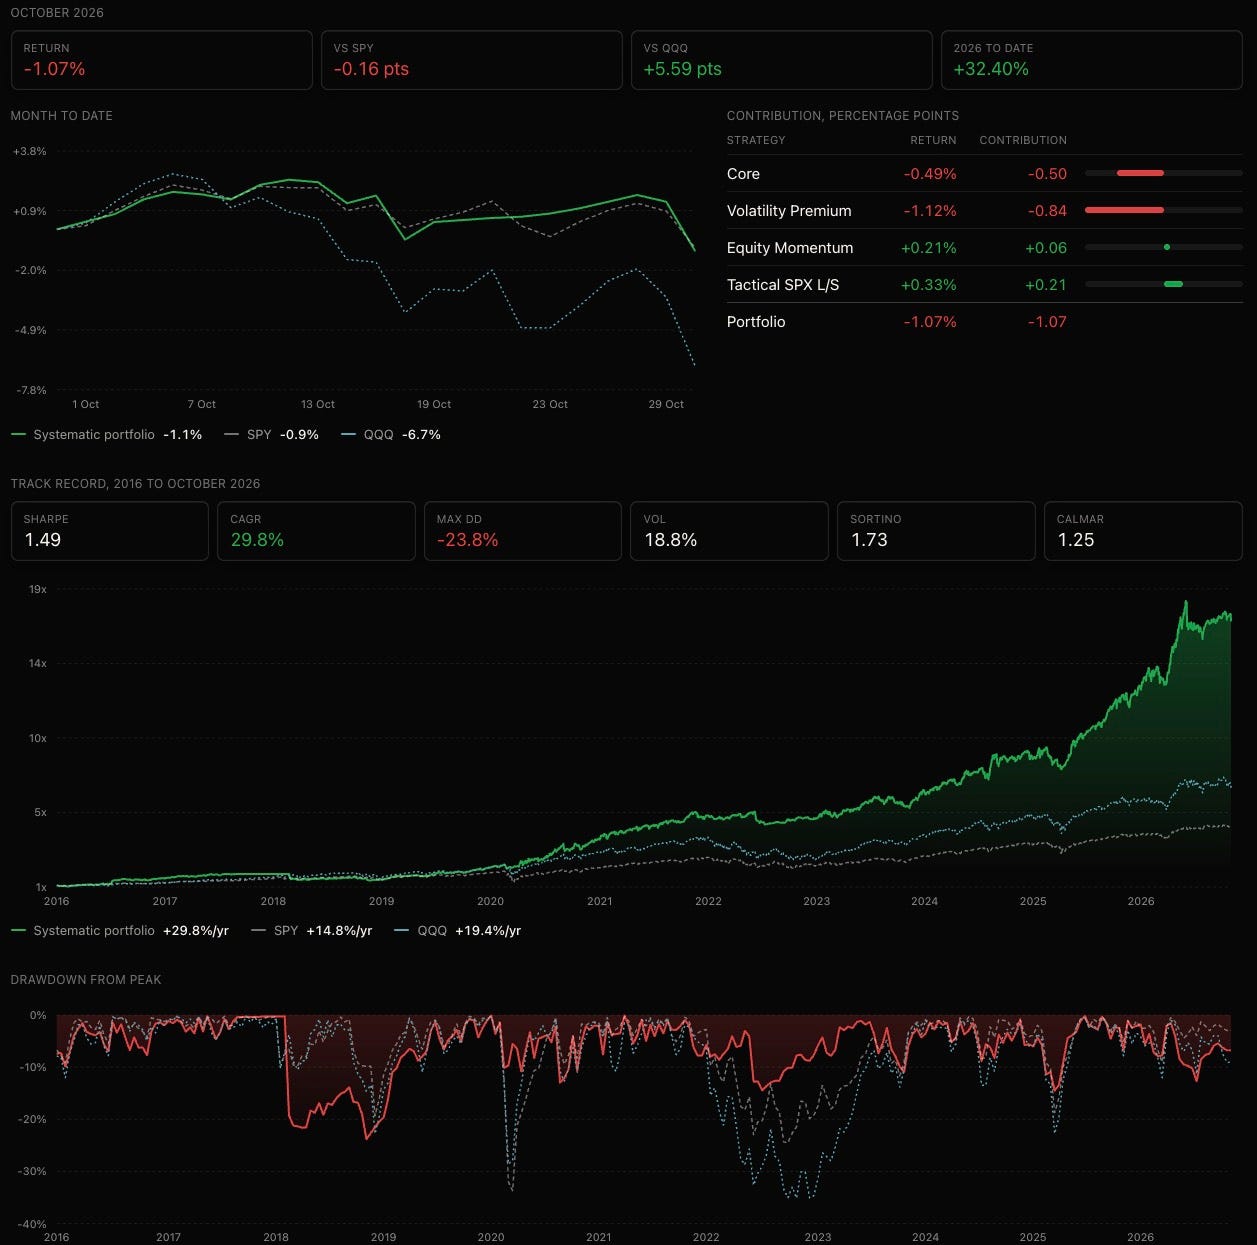
The systematic book is down ~1% a month, which is pretty solid all things considered, while it underperformed QQQ last month; tables have definitely turned this time around.
This is mostly due to the well-time rotation out of AI stocks and small profit on tactical SPXL short.
Crypto
As it is the staple in crypto, the good news of ICE (exchange, not the ICE that deports people) partnering with Hyperliquid to bring perpetuals to US customers was followed by over six billion dollars lost during the Binance hack.
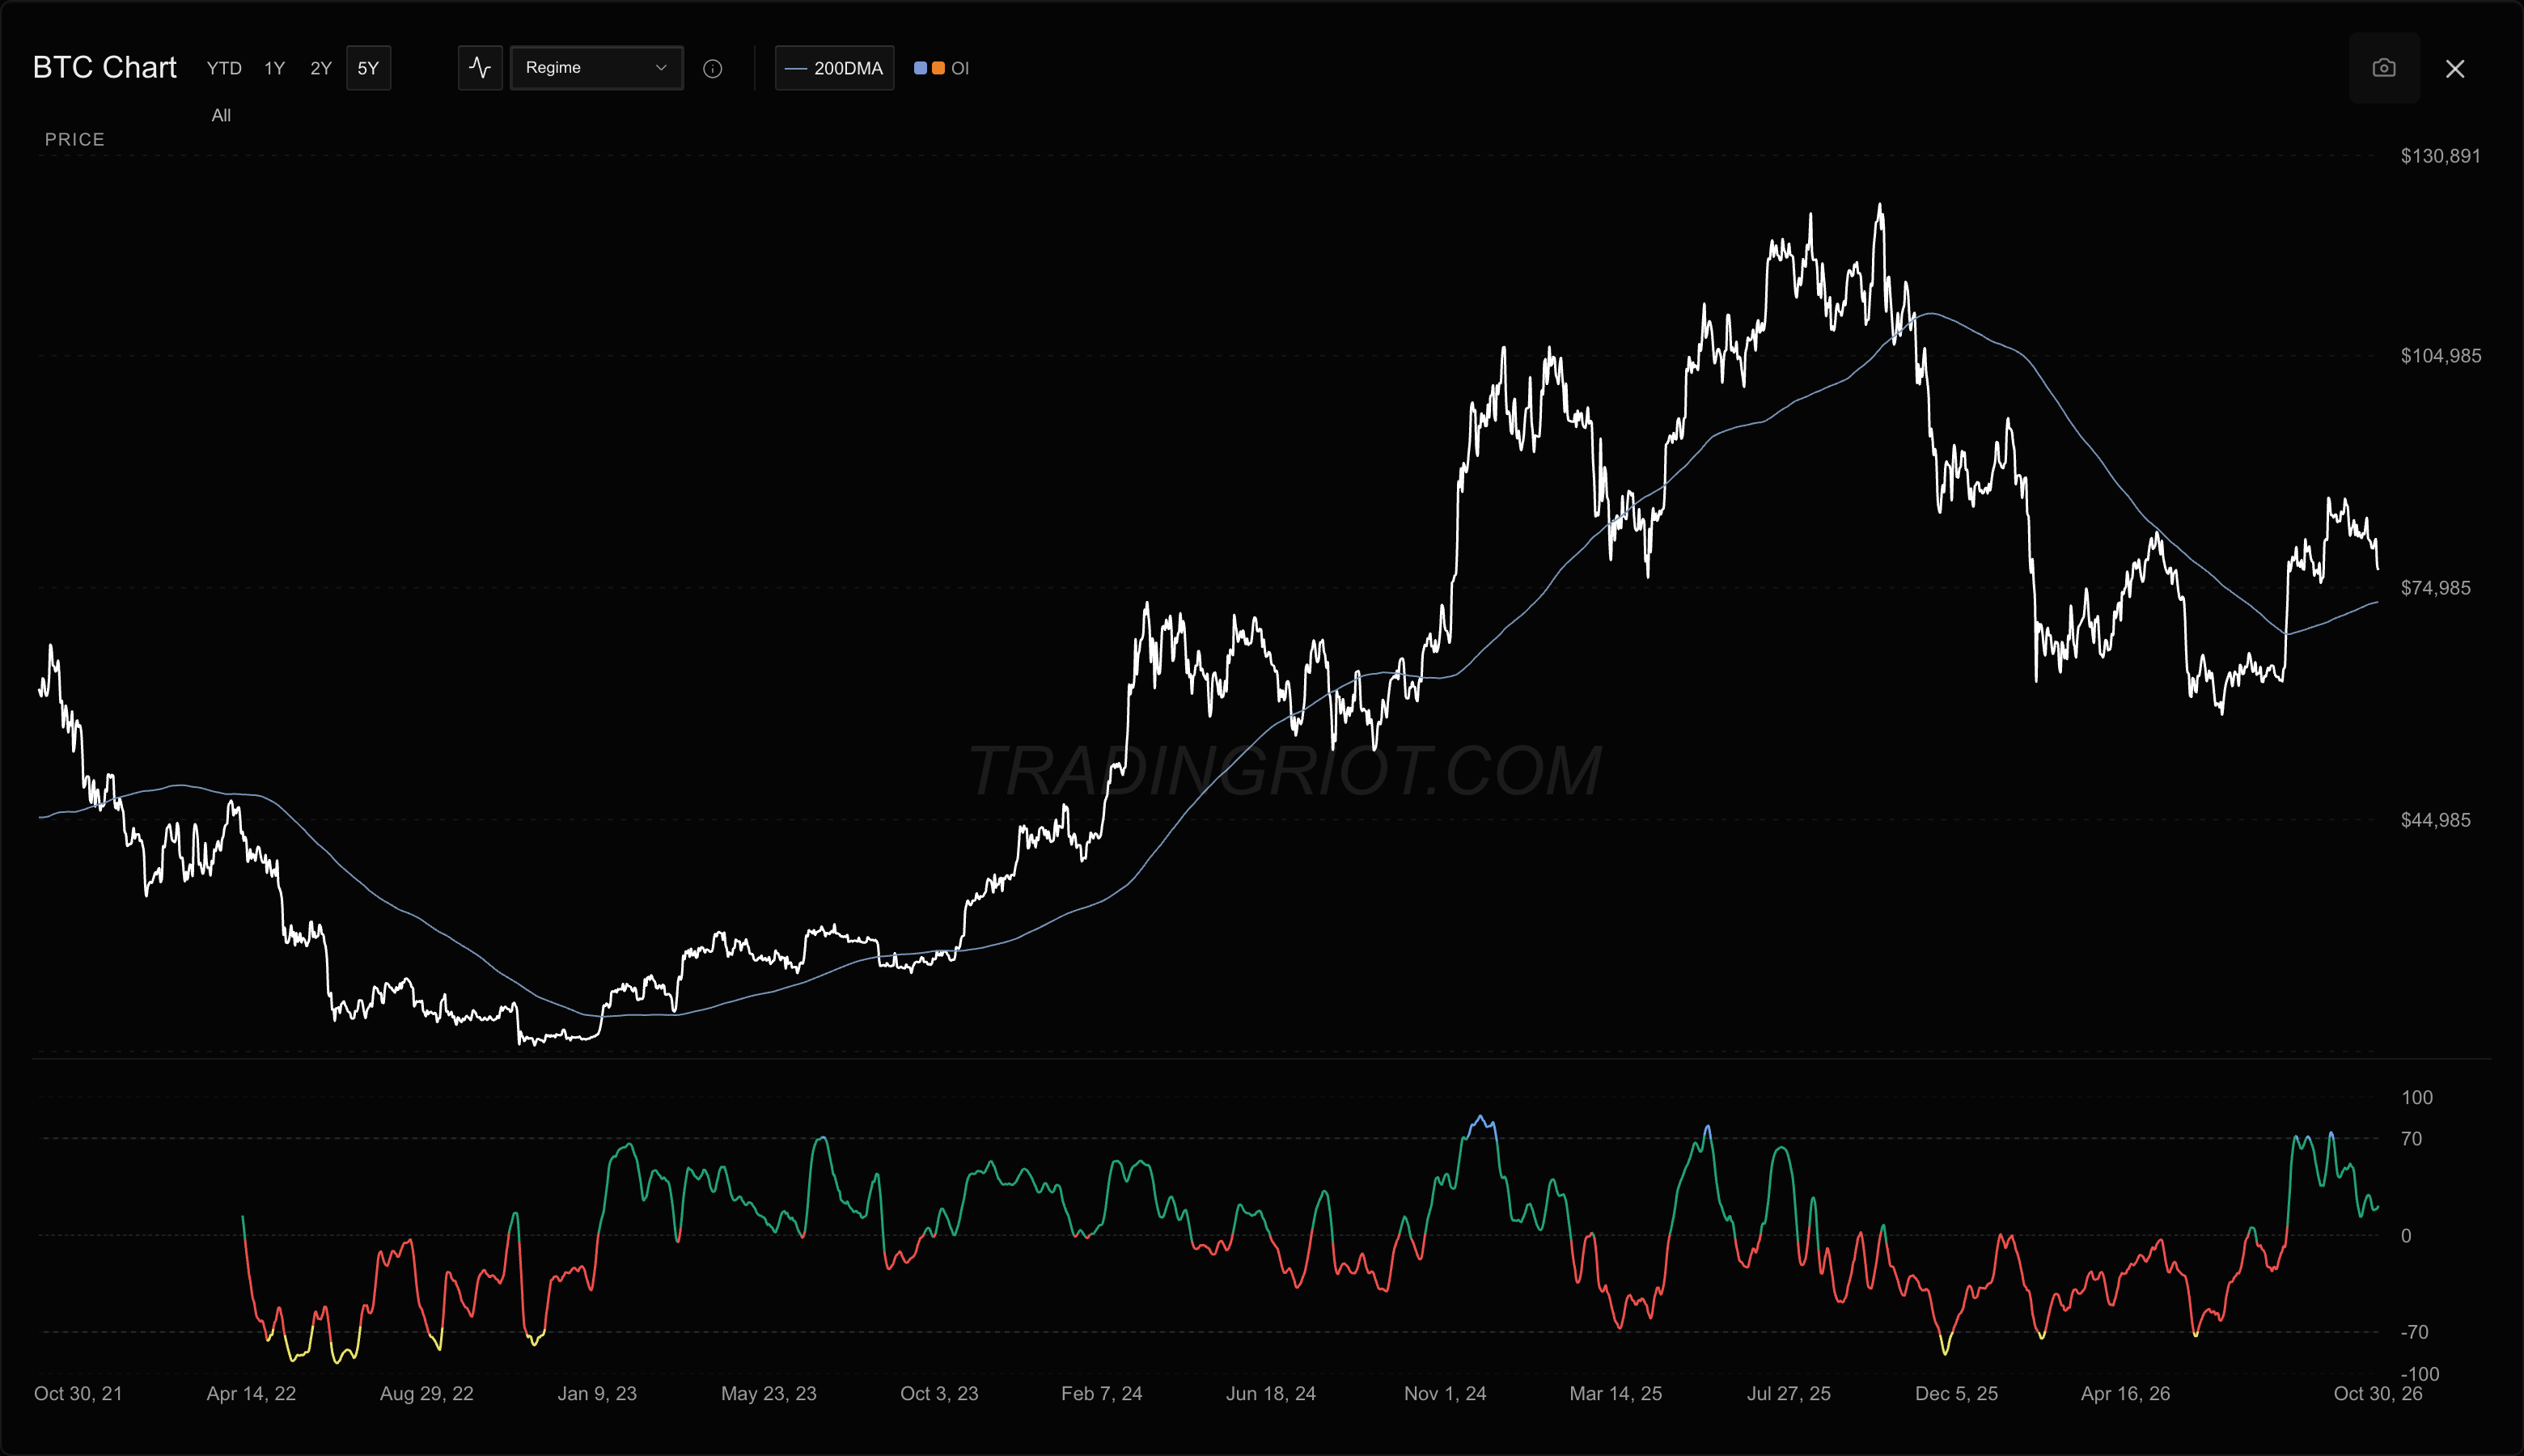
While Bitcoin sold off, it did not have the “$6bn was just hacked from Binance” type of sell-off and was mostly following the risk-off Friday move across the board.
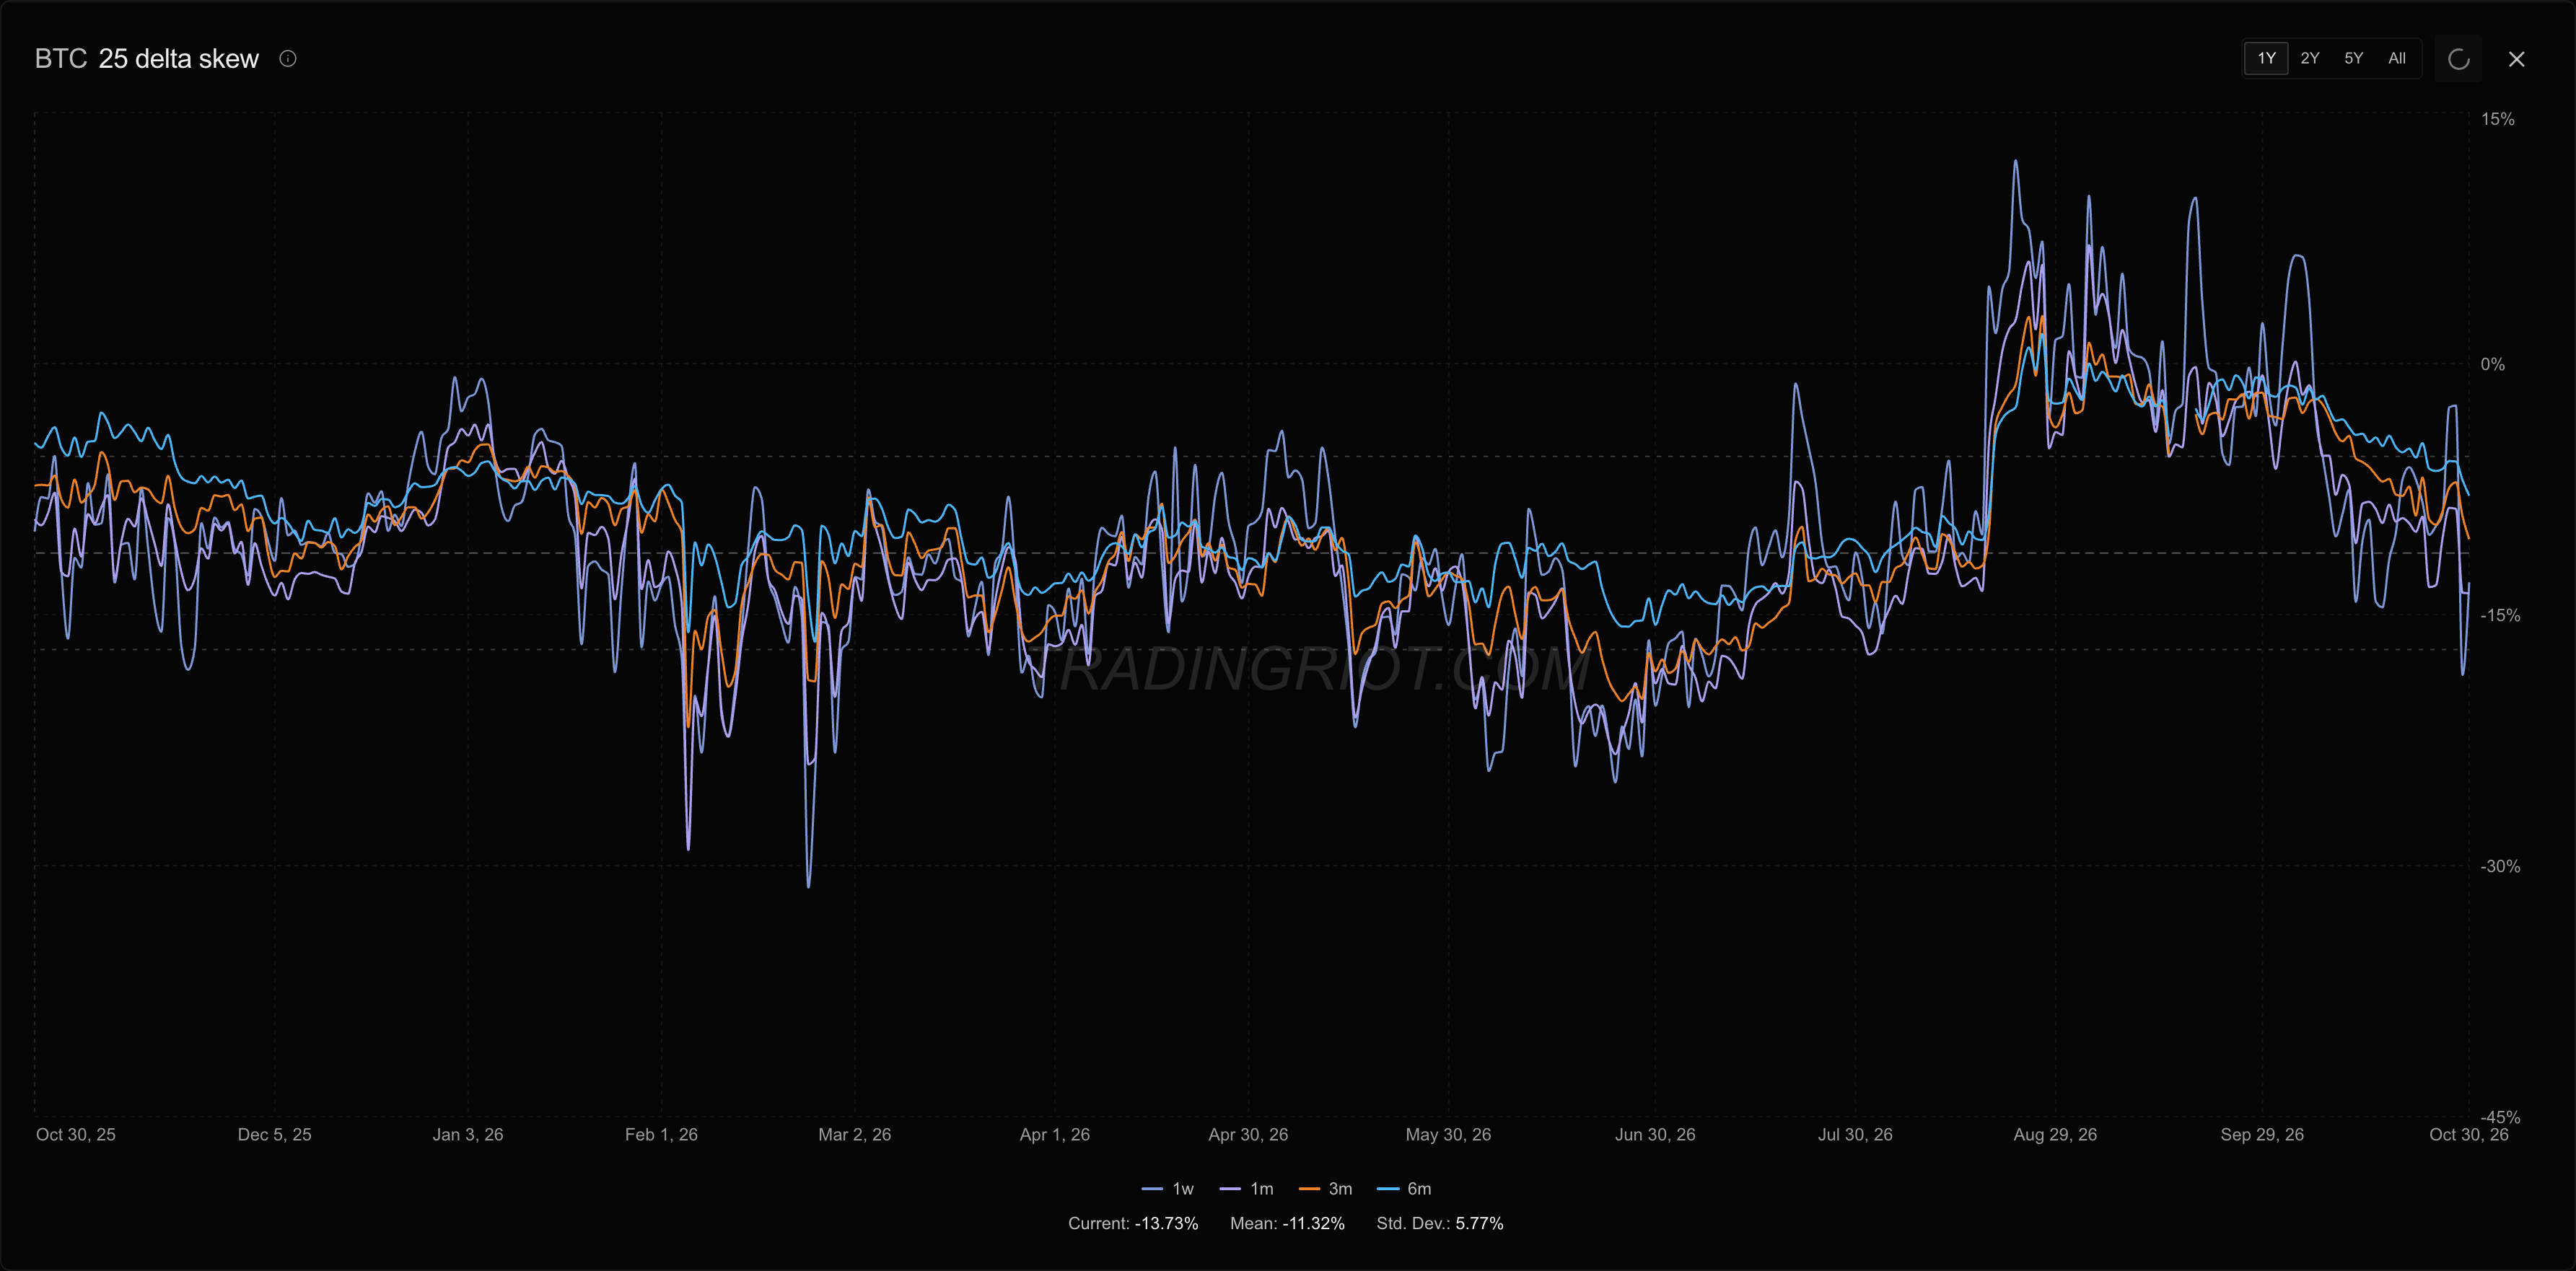
Options showed this pretty clearly with increasing put demand as skew slid lower on all tenors; perps don’t seem to bulge yet.
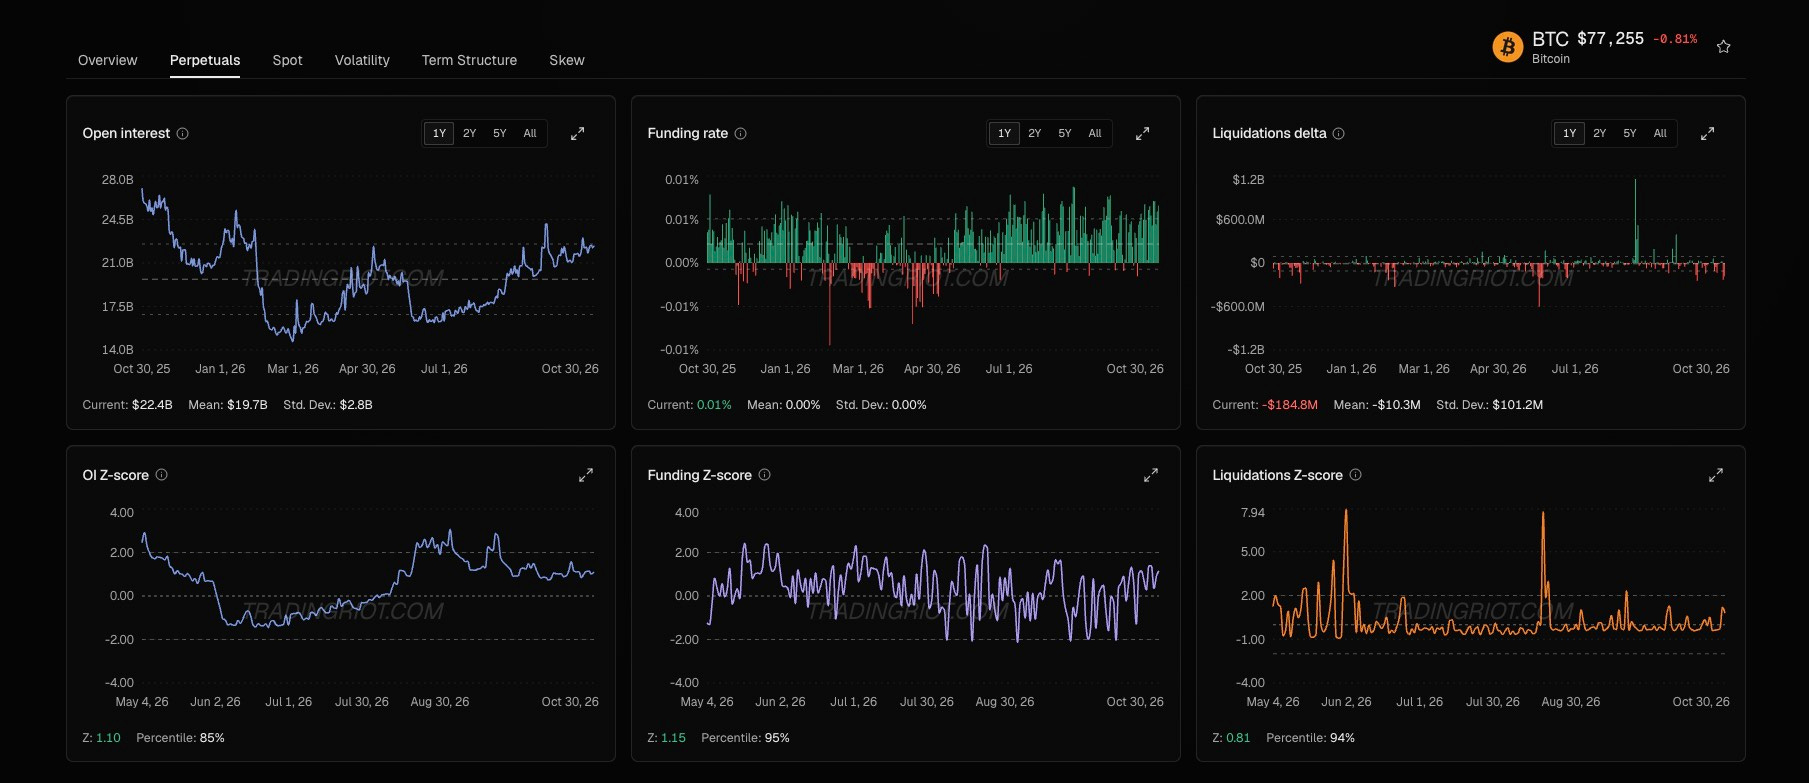
As funding rates stay elevated and there are no visible pukes in open interest, I am not too eager to buy the dip on BTC.
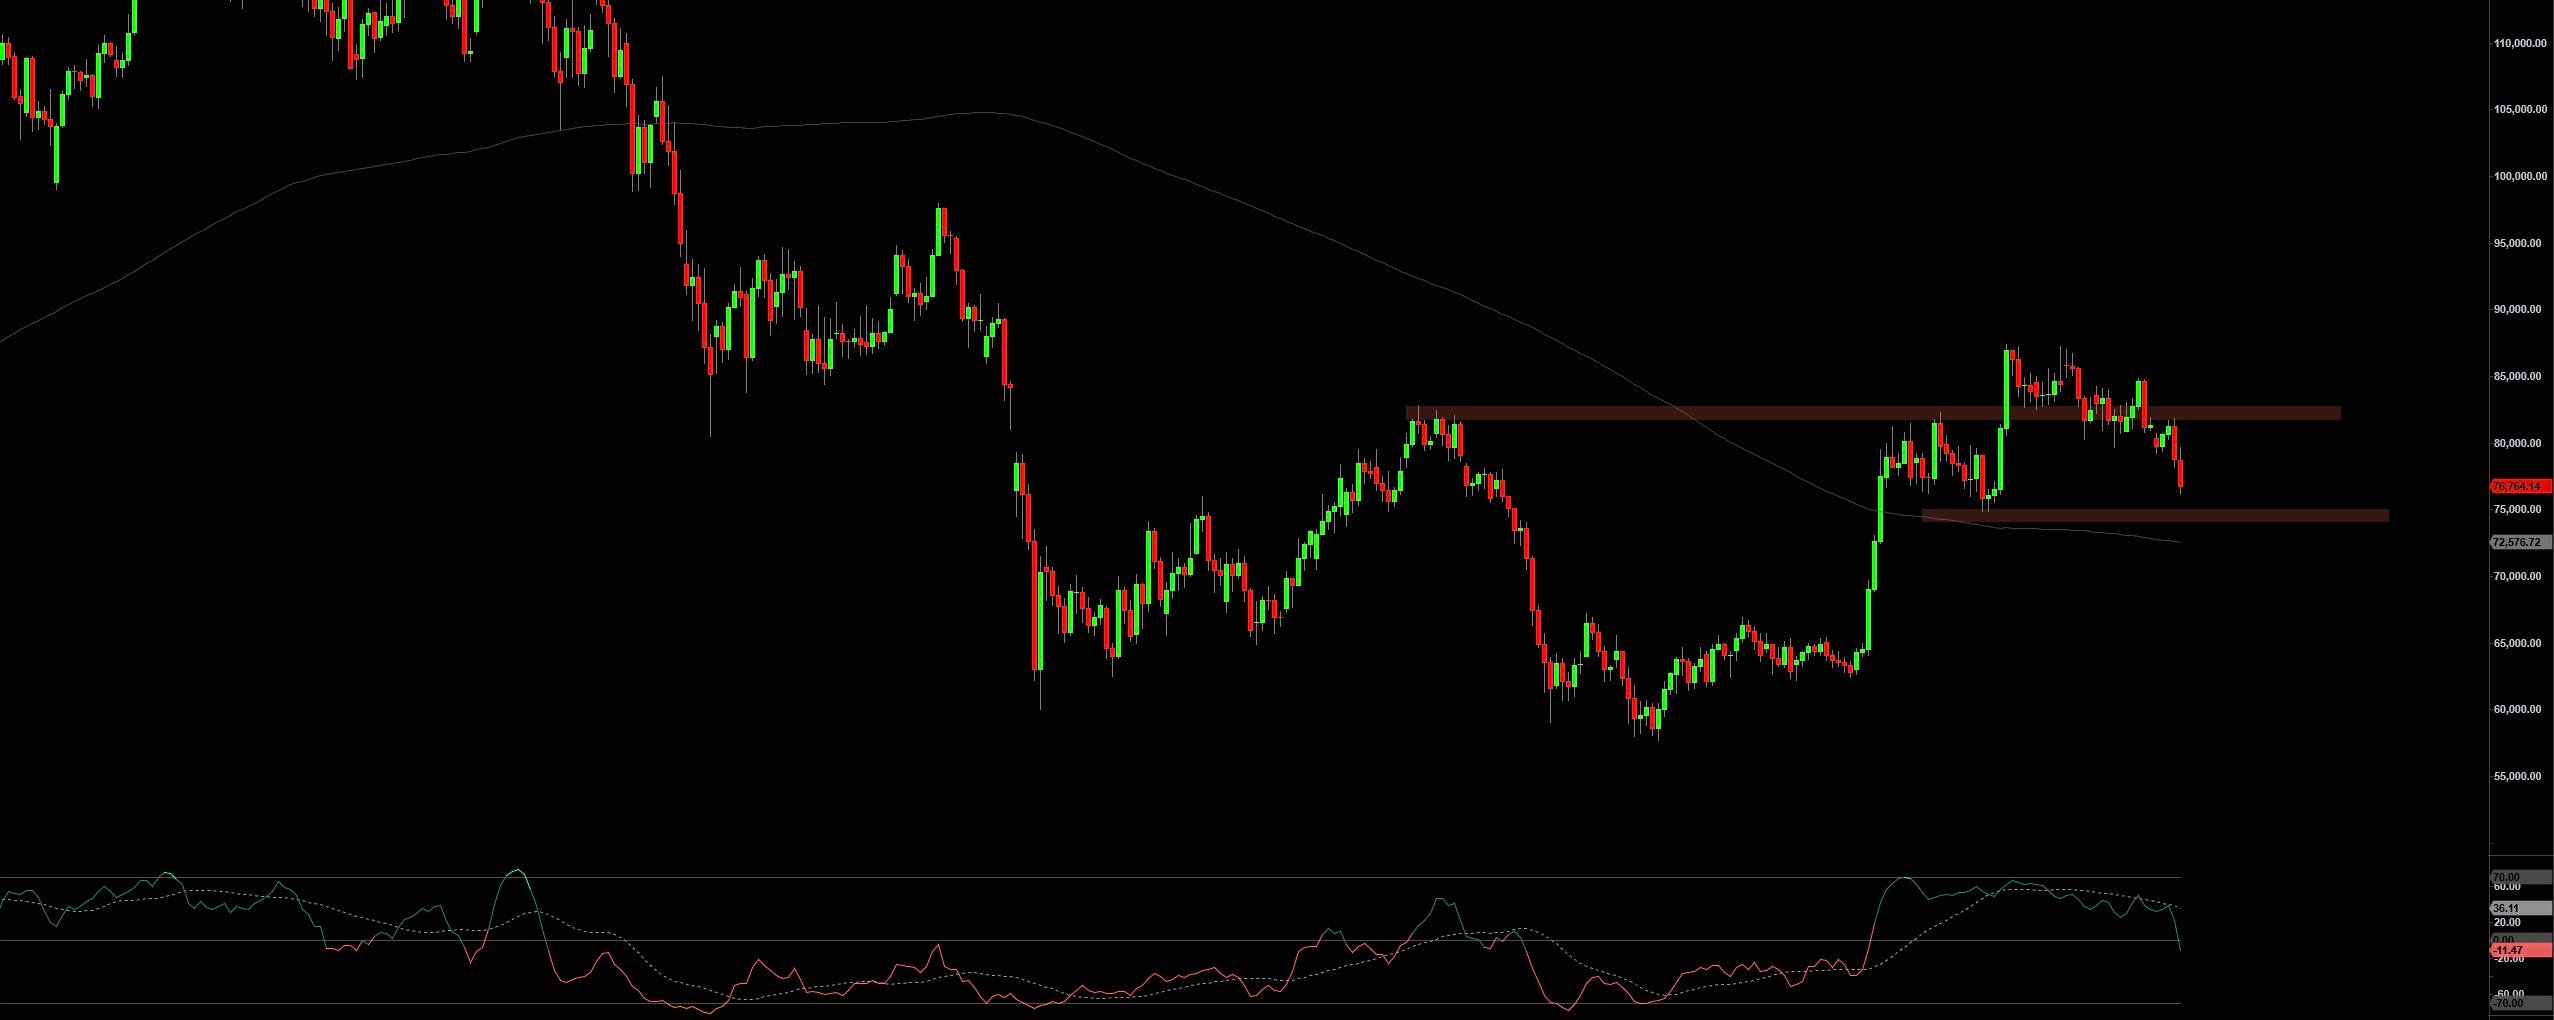
I think next week will be pretty interesting for BTC, as it’s coming to the “loose this level and it’s light out” level at around 75k with 200-DMA also hanging around there; under that there isn’t much to support it back down to the 60s.
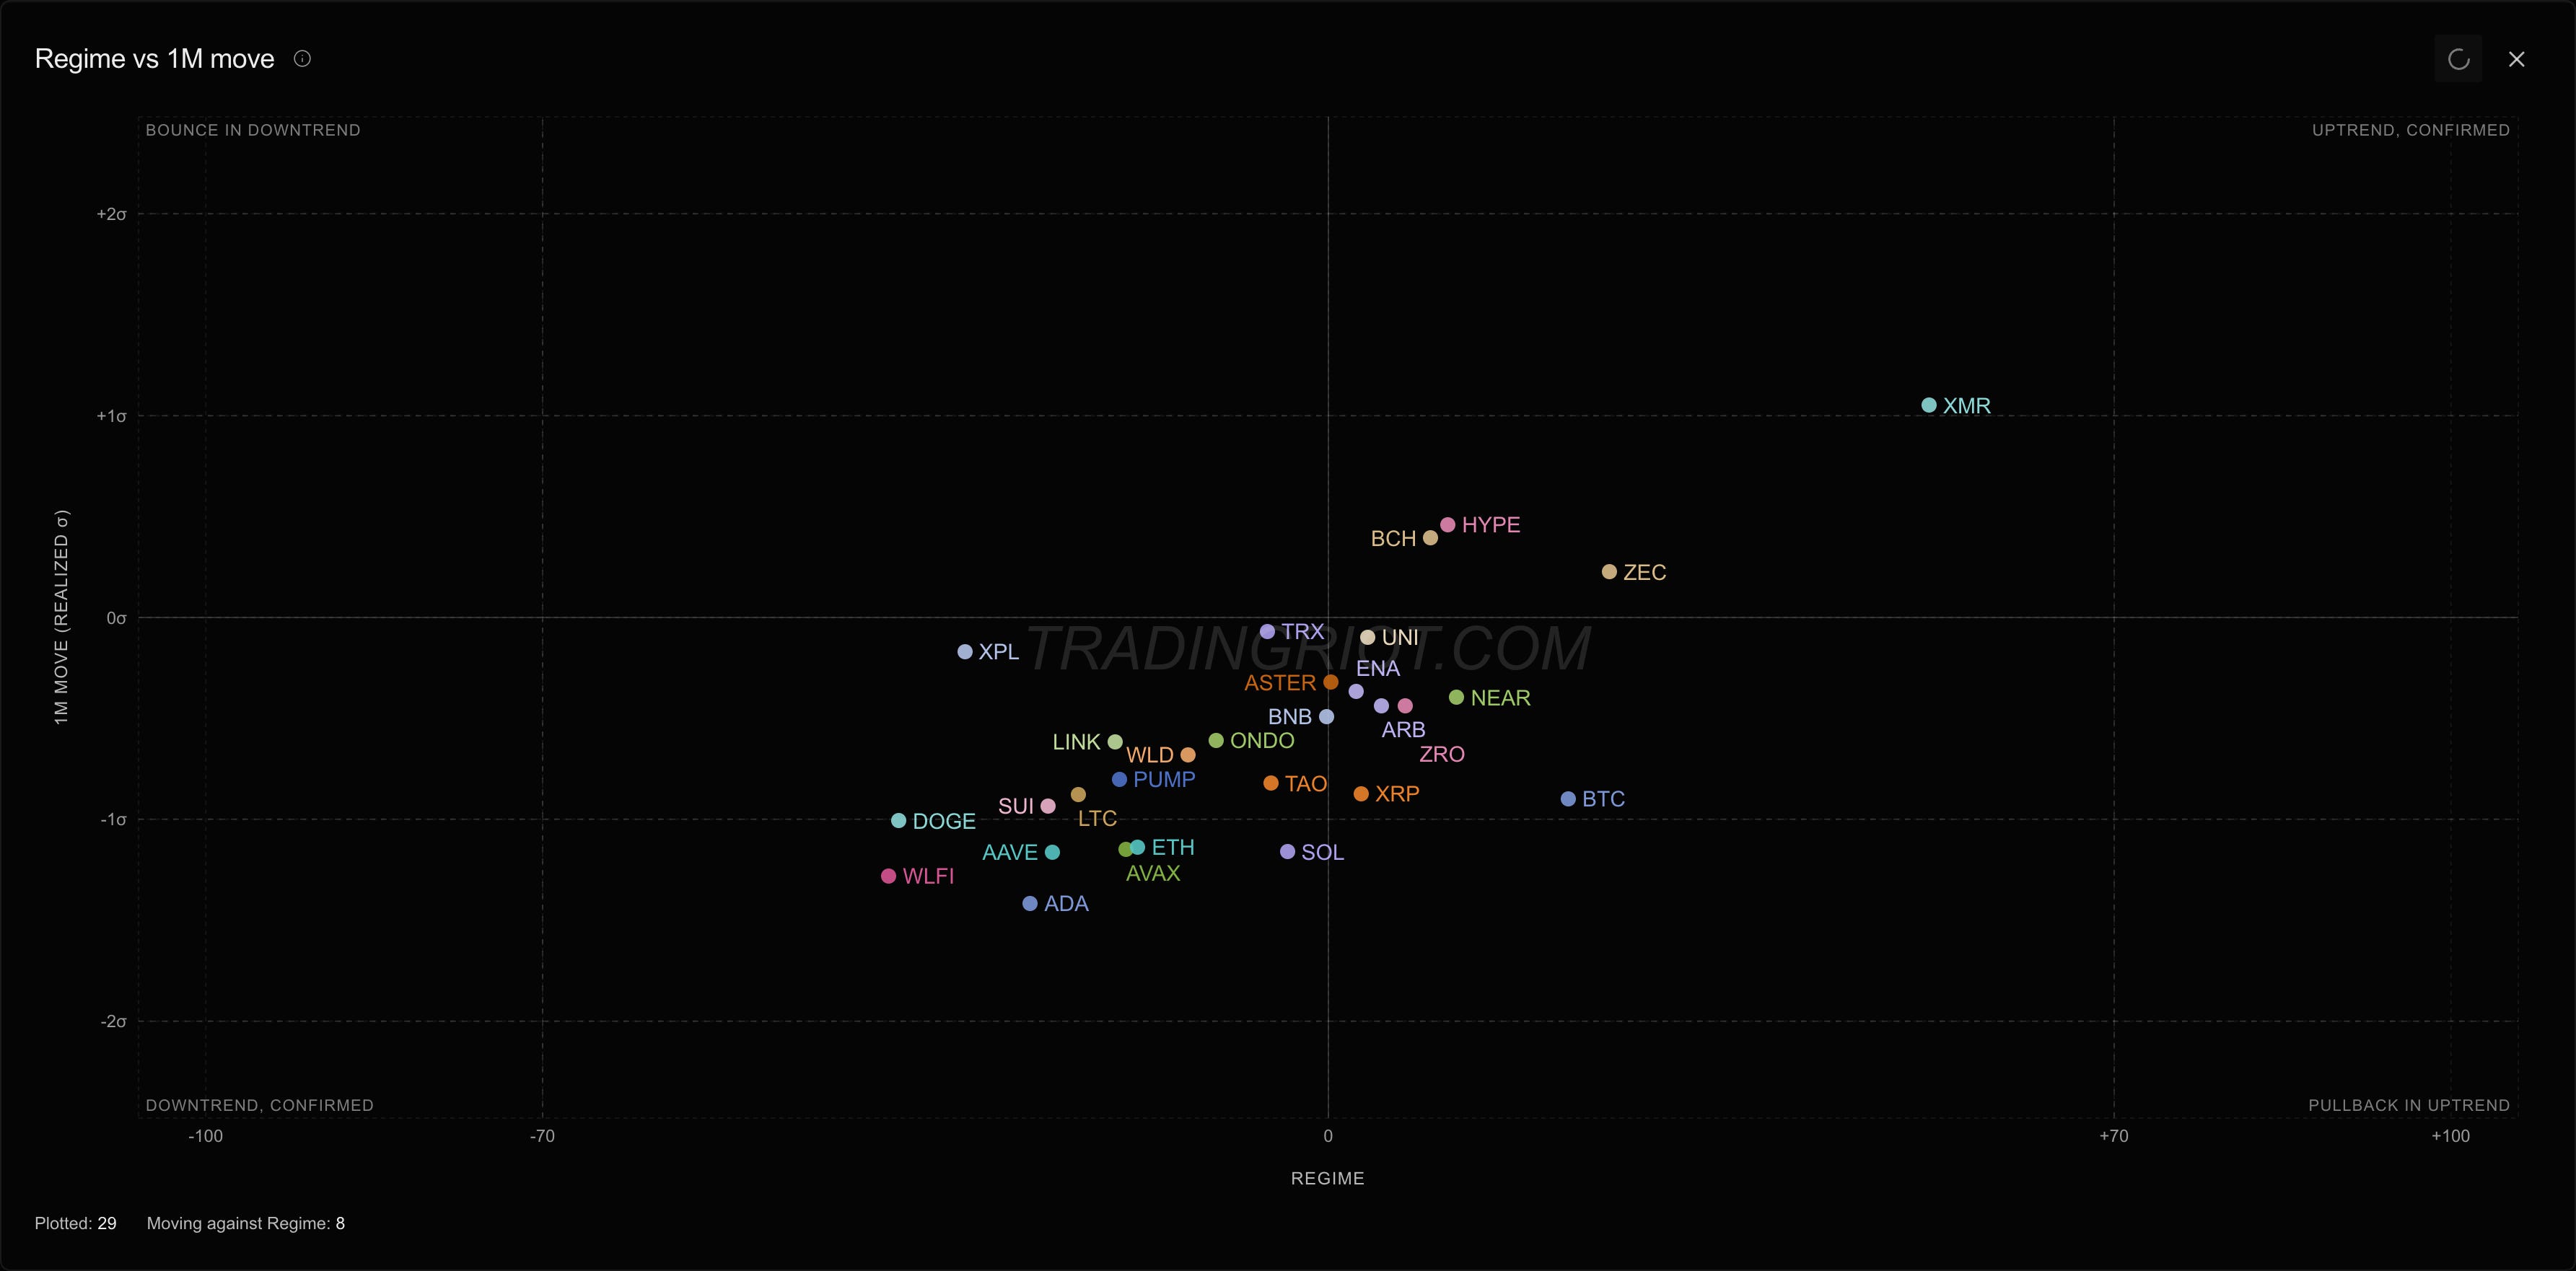
For altcoins, the main outliers besides Hyperliquid are Monero and Z-cash, with the privacy narrative still holding well, and XMR finally showing strength as the true privacy play.
Futures
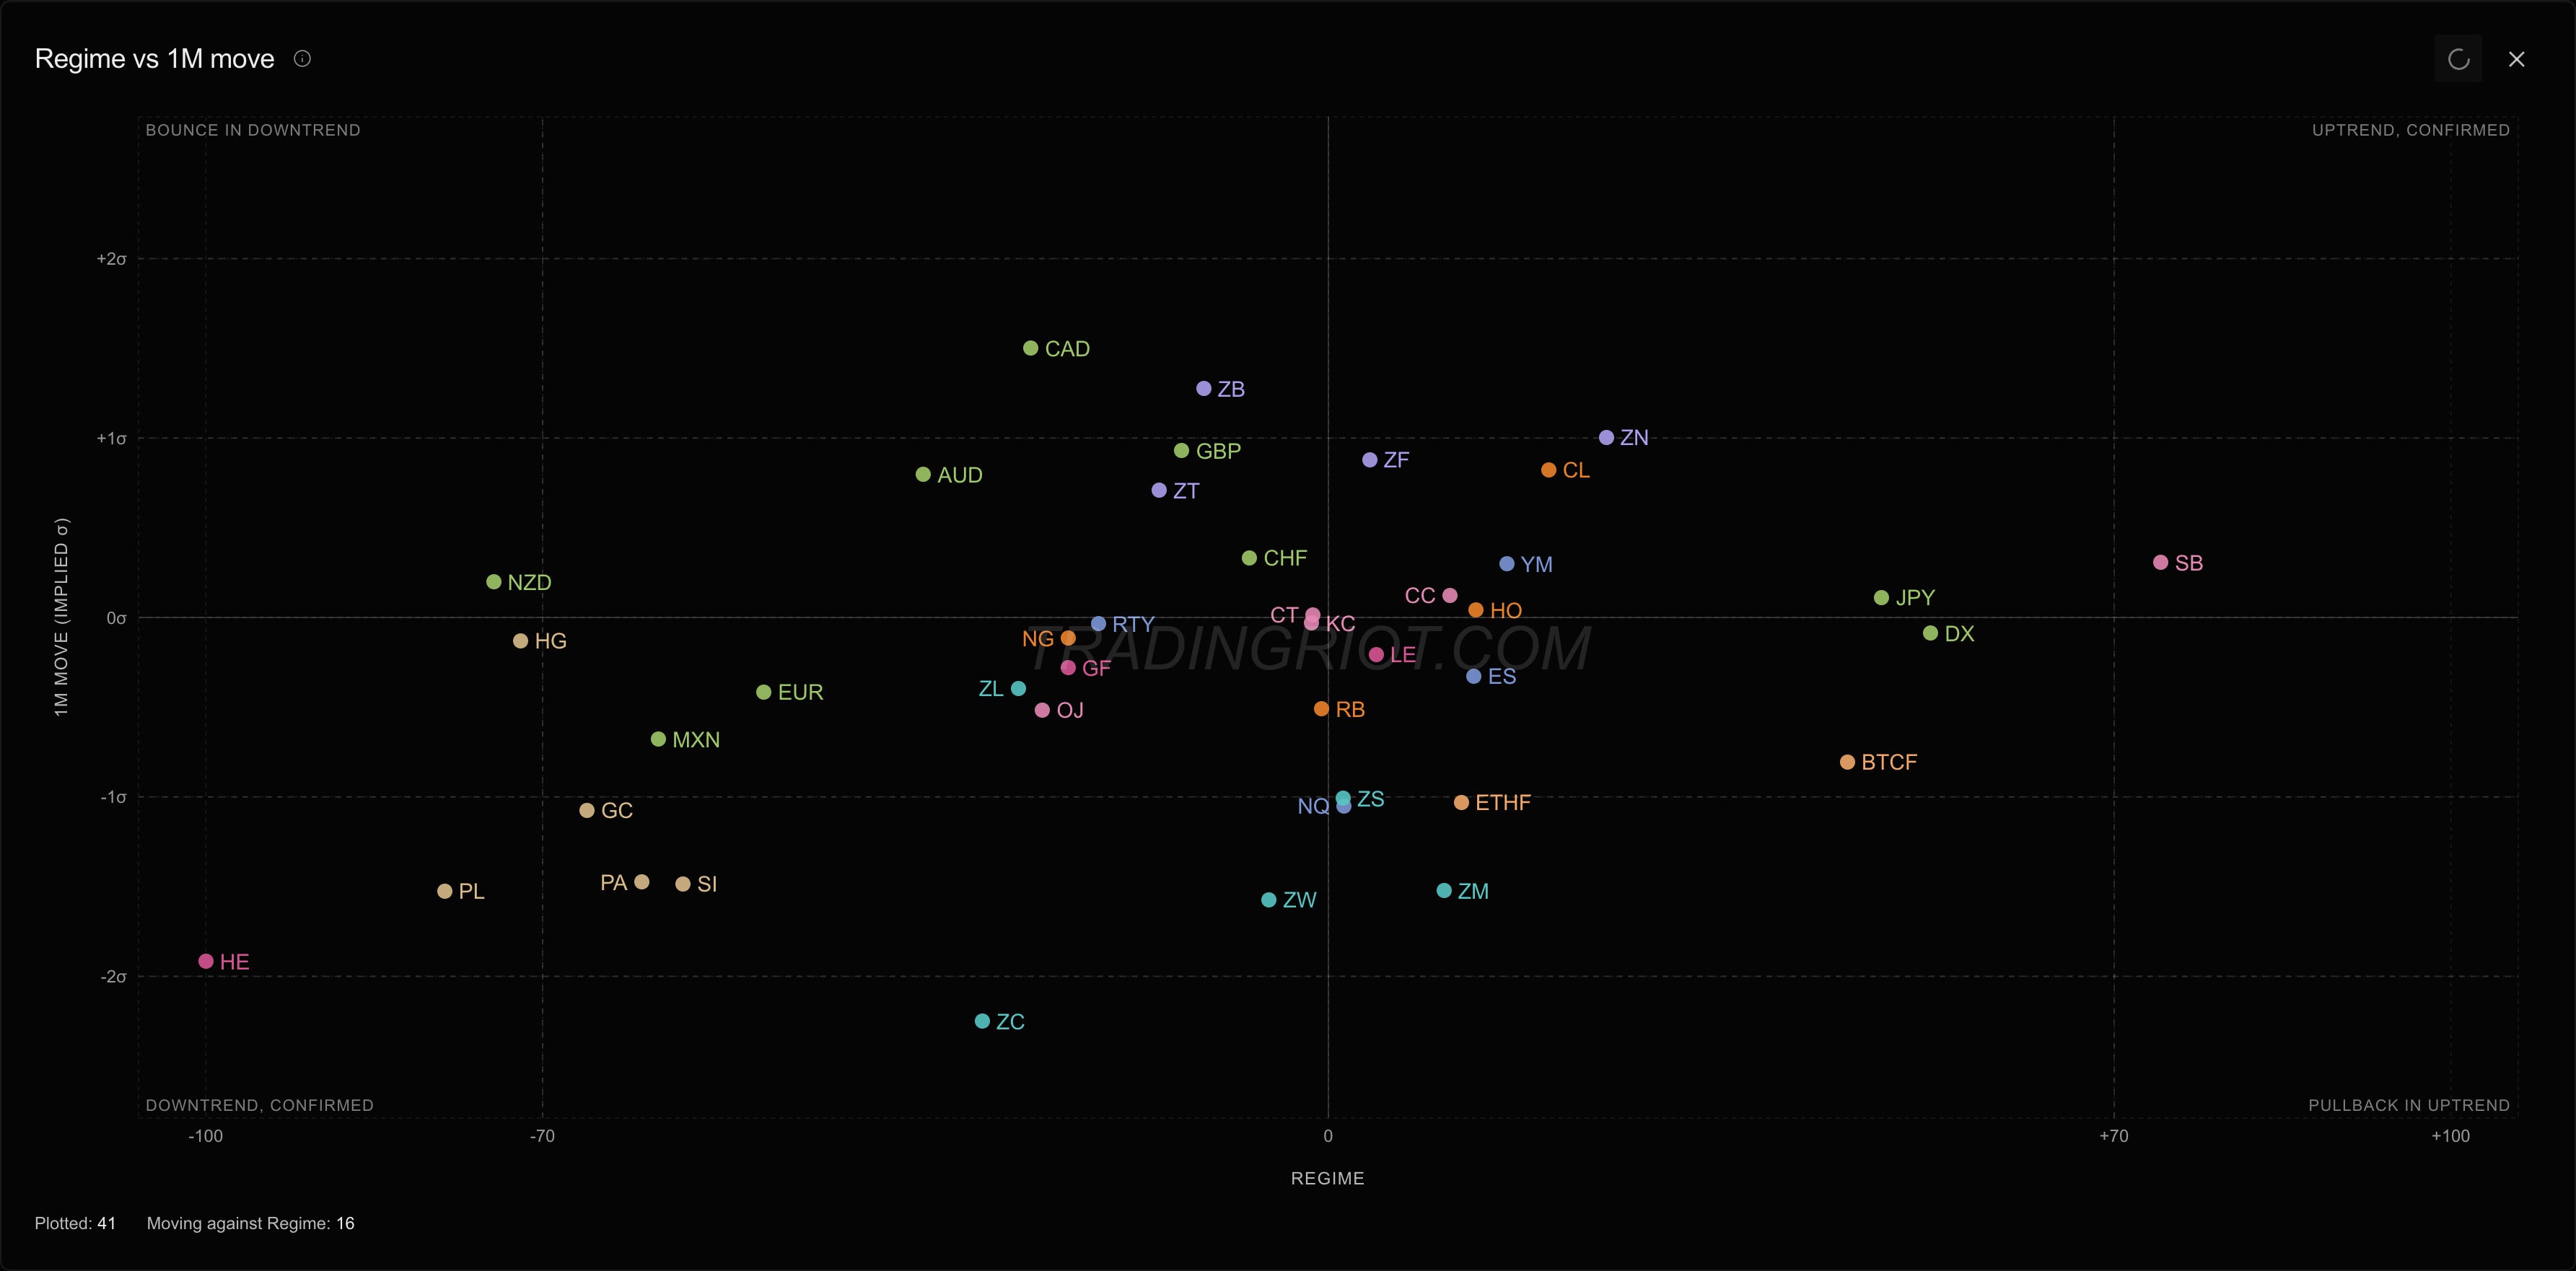
Metals fill the bottom of the regime board. In the future this regime consists of options skew, COT positioning, slope of term structure, and momentum.
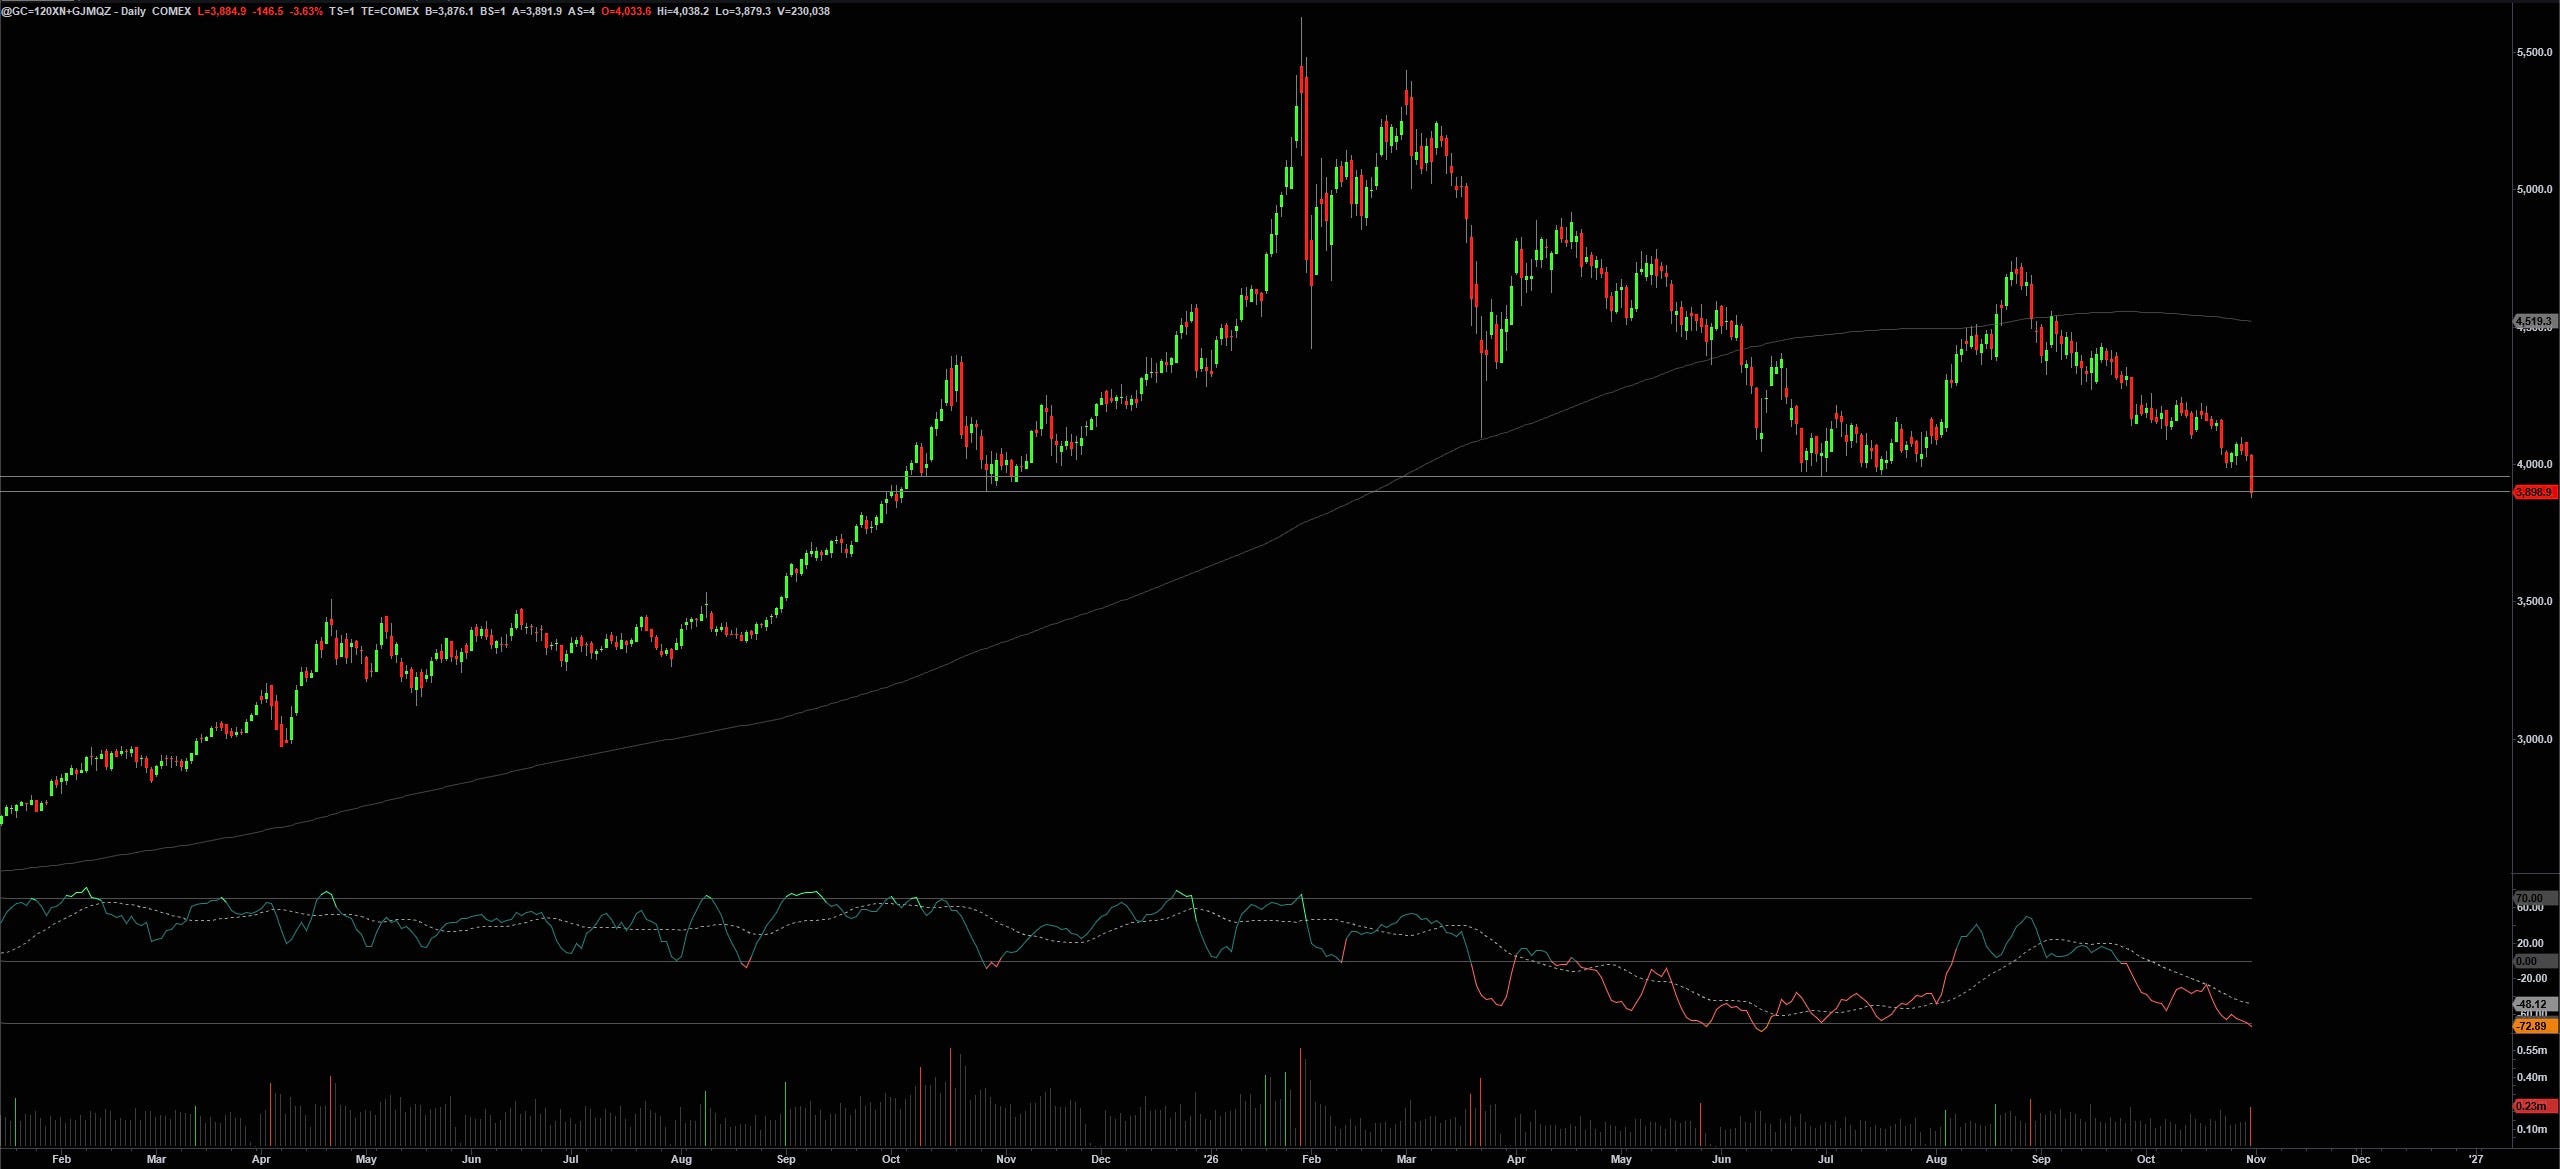
Gold’s regime is its weakest since October 2023, with gold itself reported at a one-year low. Platinum and silver are both at the bottom of their years as well.
Copper is the odd one out. Price barely moved this week, but its regime is the most extreme, with carry and skew what’s dragging it down, so the options and curve markets look a lot weaker than the price chart.
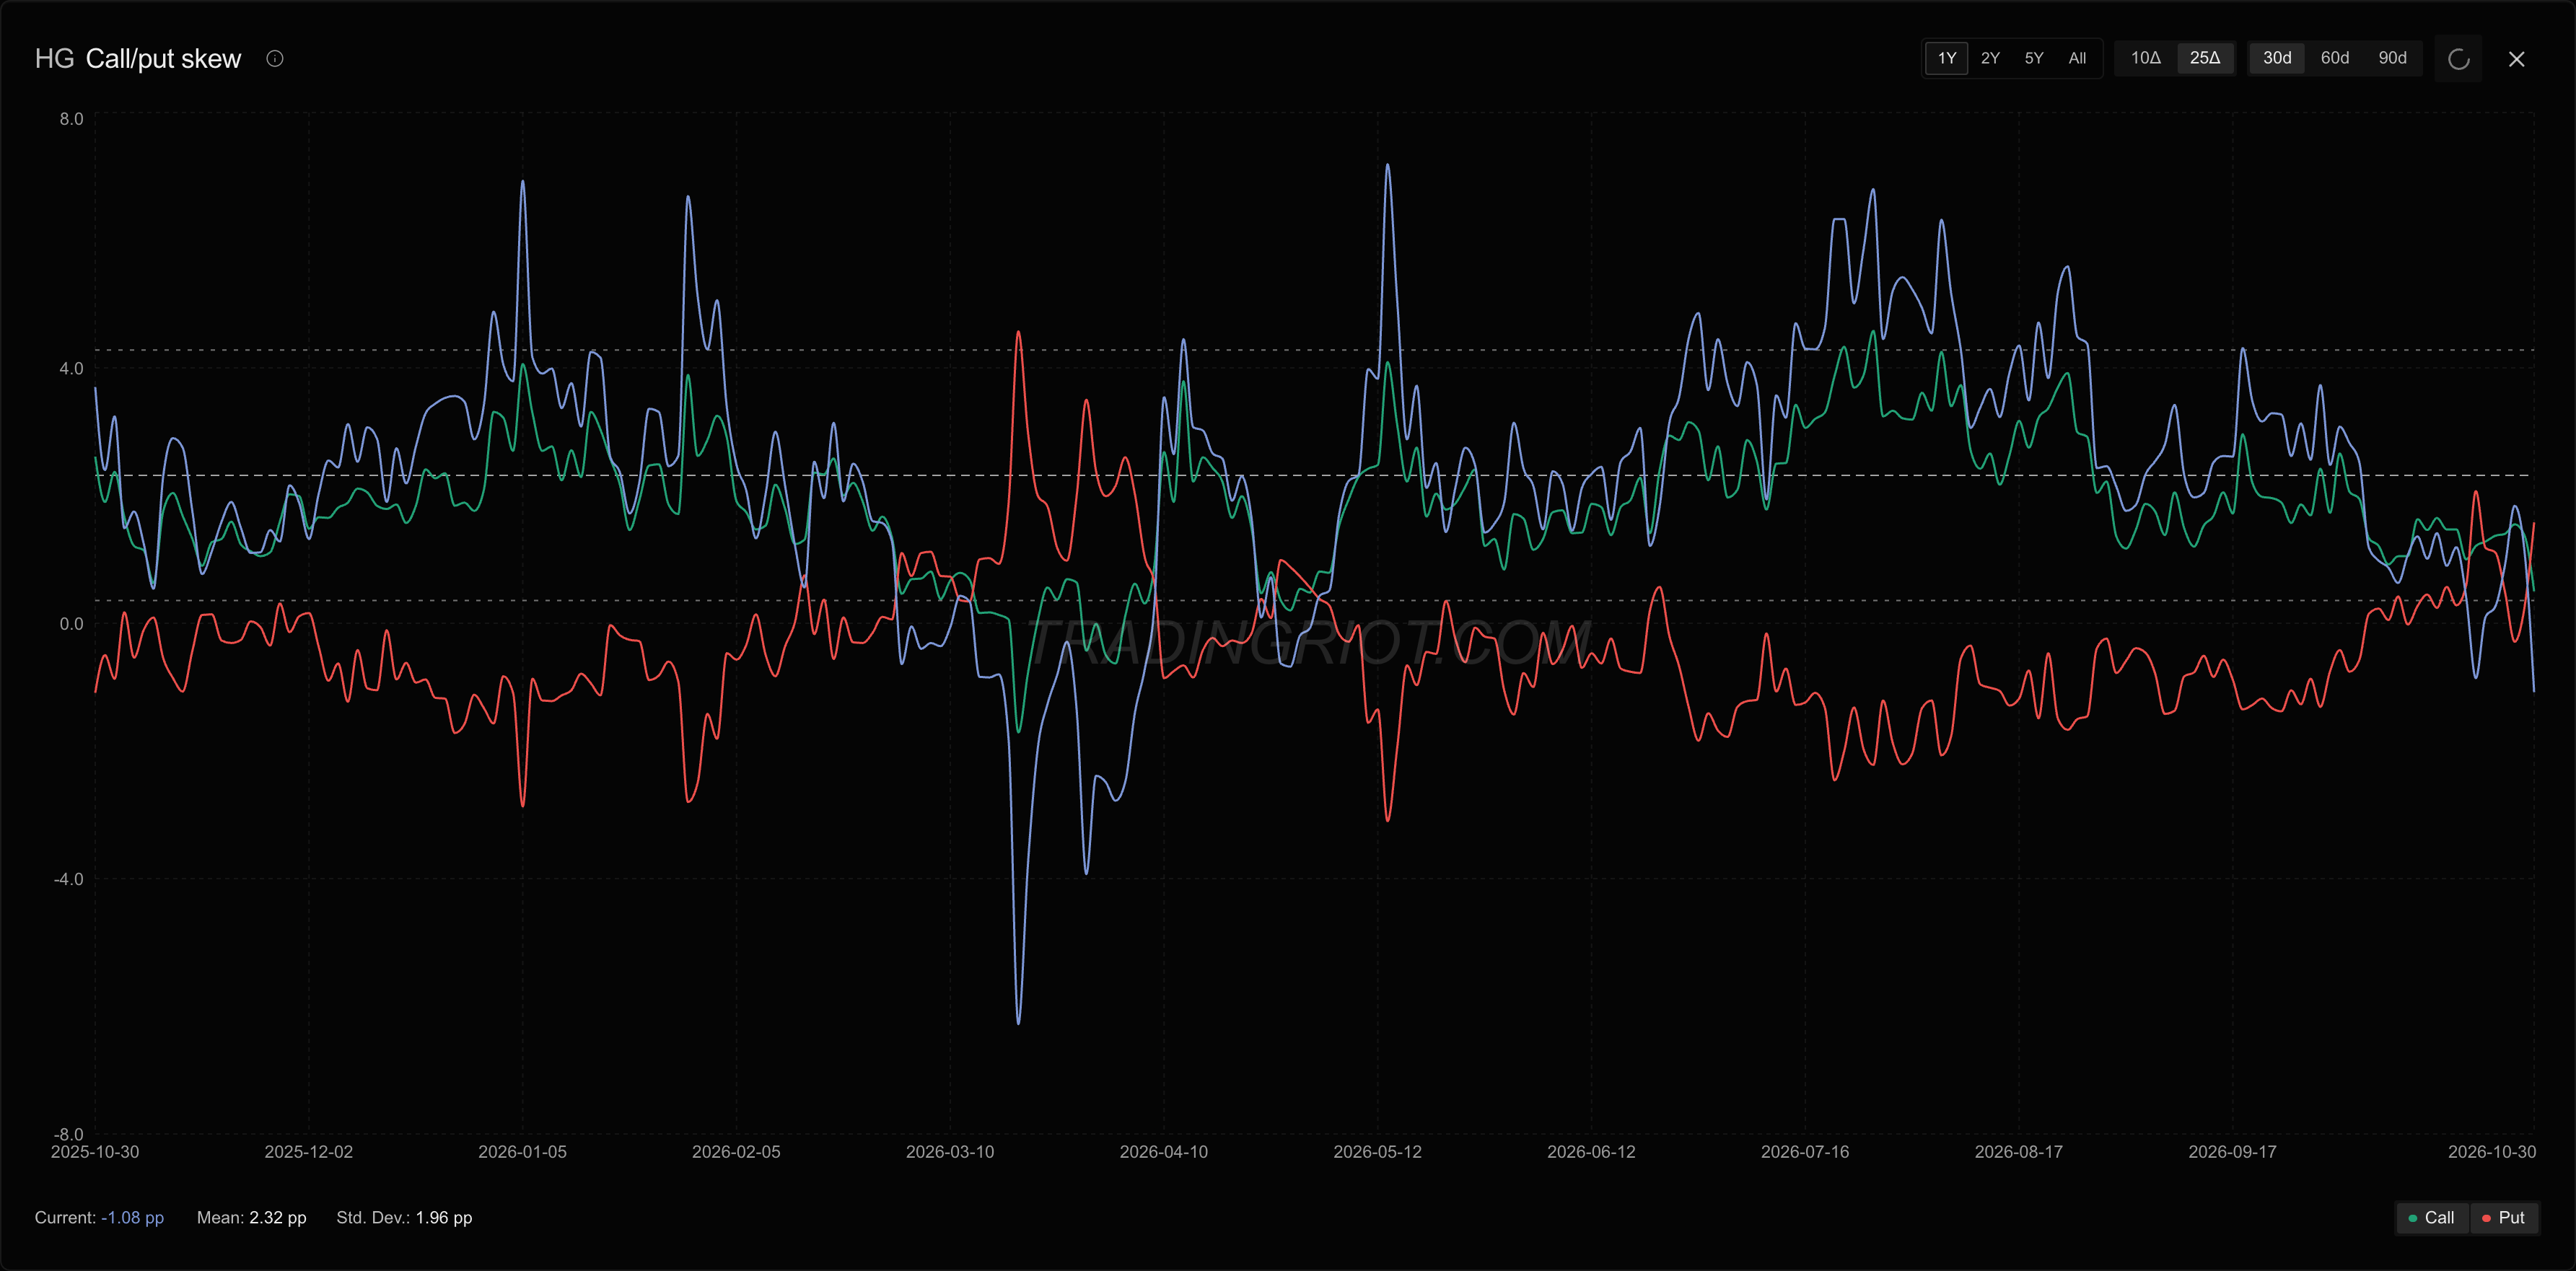
For the next week, I will be looking for some signs of mean reversion in metals; if that comes, I’d expect copper to lead.
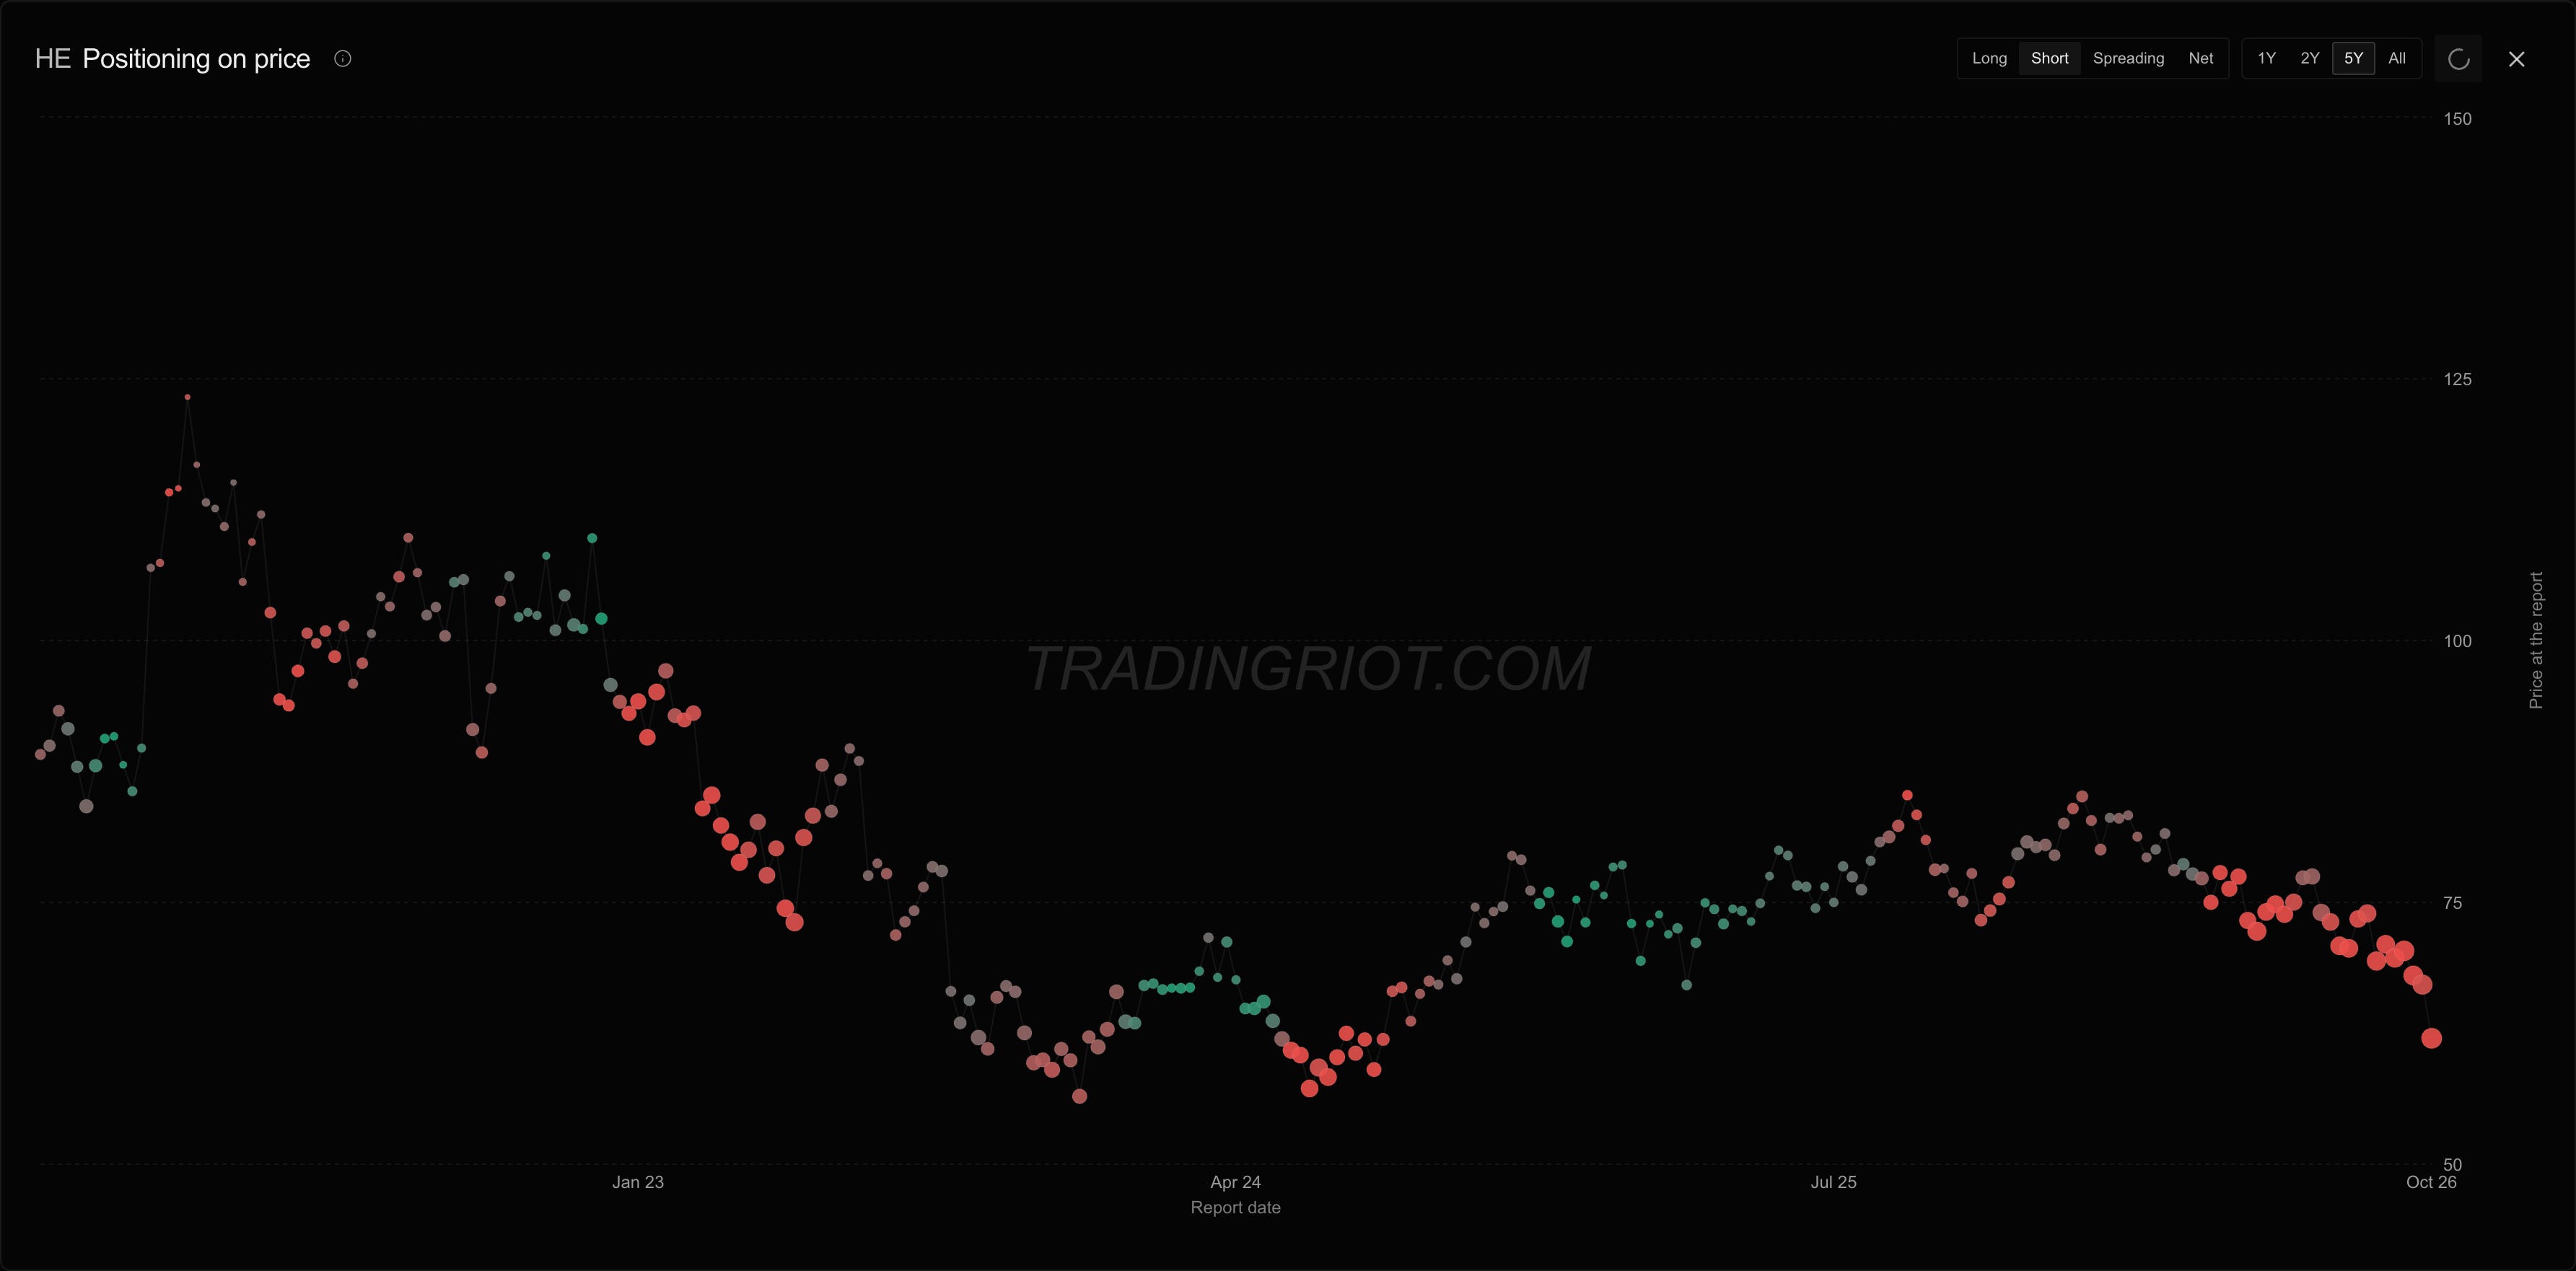
Lean hog futures are also at an interesting spot as the market is experiencing a huge sell-off due to oversupply, which large speculators being heavily short.