

This week could be summarized as a giant bait; after Democrats swept the midterms, stocks first took it as relief, with SPX rallying 1.6% on Wednesday and VIX dropping to 16.6.
By Thursday the market had worked out what a Democratic Congress could mean for AI data centers, and the relief turned into the Nasdaq’s worst day in over a year, and the SPX fell almost 5% in a single sessions.
Friday’s jobs report was not helpful either. Unemployment slipped and payrolls came way above expectations; Fed officials are now openly talking about a hike.
Oil had a full round trip of its own. Crude dropped more than 7% on Monday on Iran diplomacy, went under $90 on Wednesday as the midterm result was read as a possible end to the Iran war, and finished the week down almost 13%. Energy was the worst sector by a distance.
Crypto held up better than tech but still bled. ETF outflows pushed the 2026 ETF balance below zero.
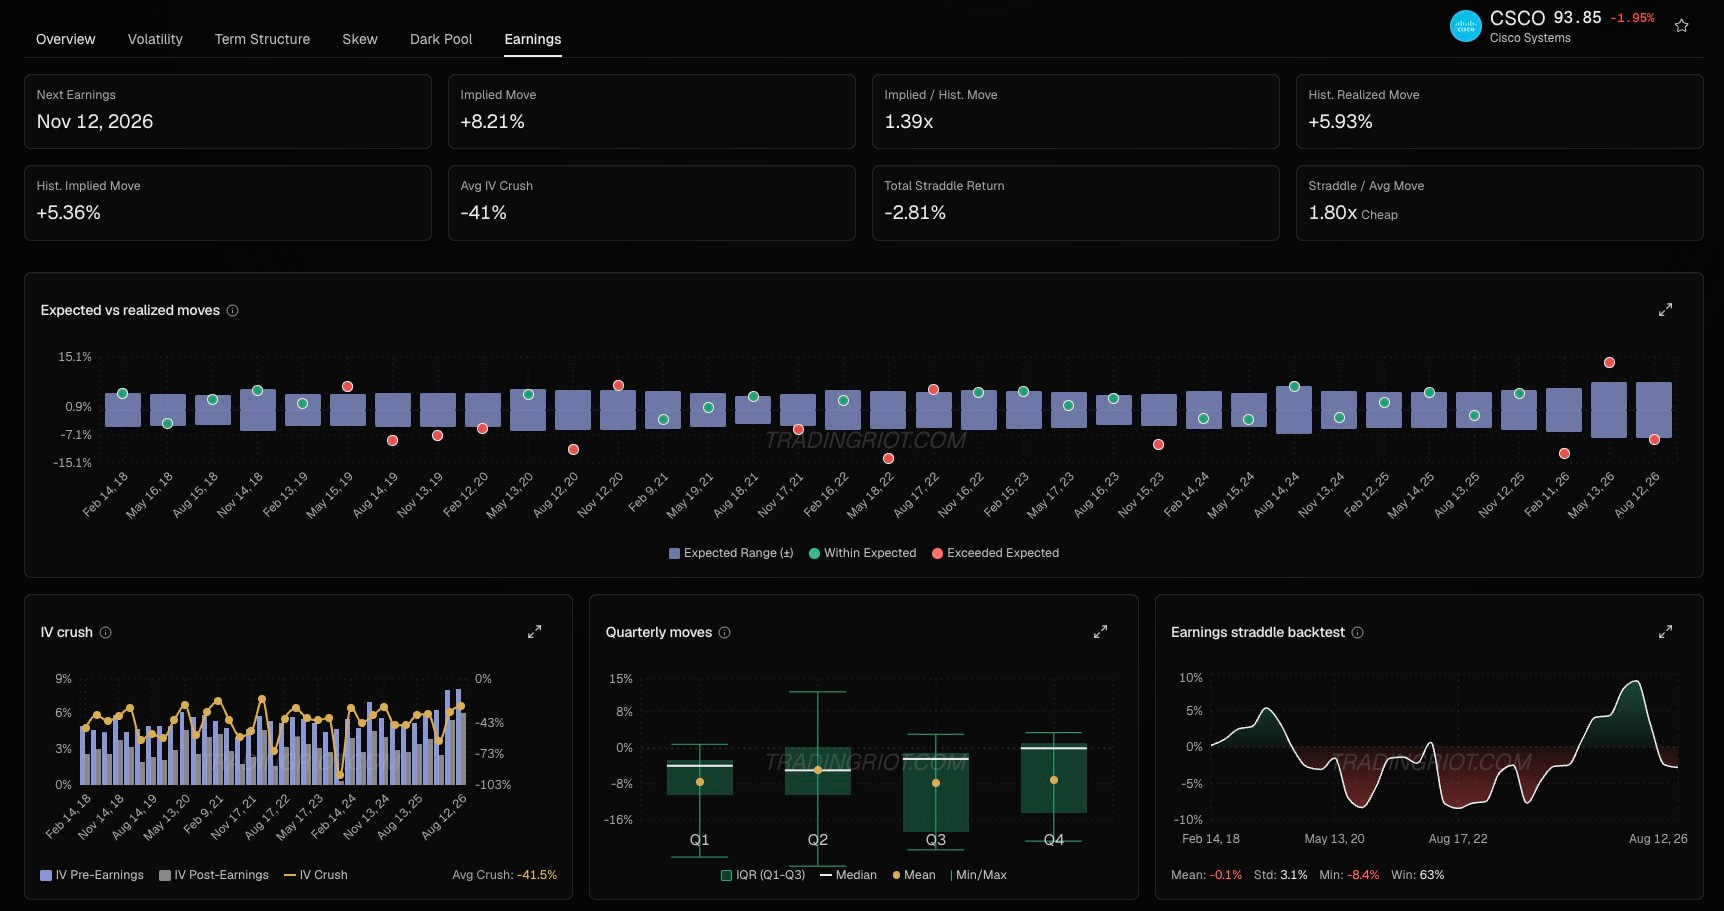
Next week should be equally fun, as it brings the October CPI, plus CoreWeave, Nebius, Applied Materials, and Cisco earnings.
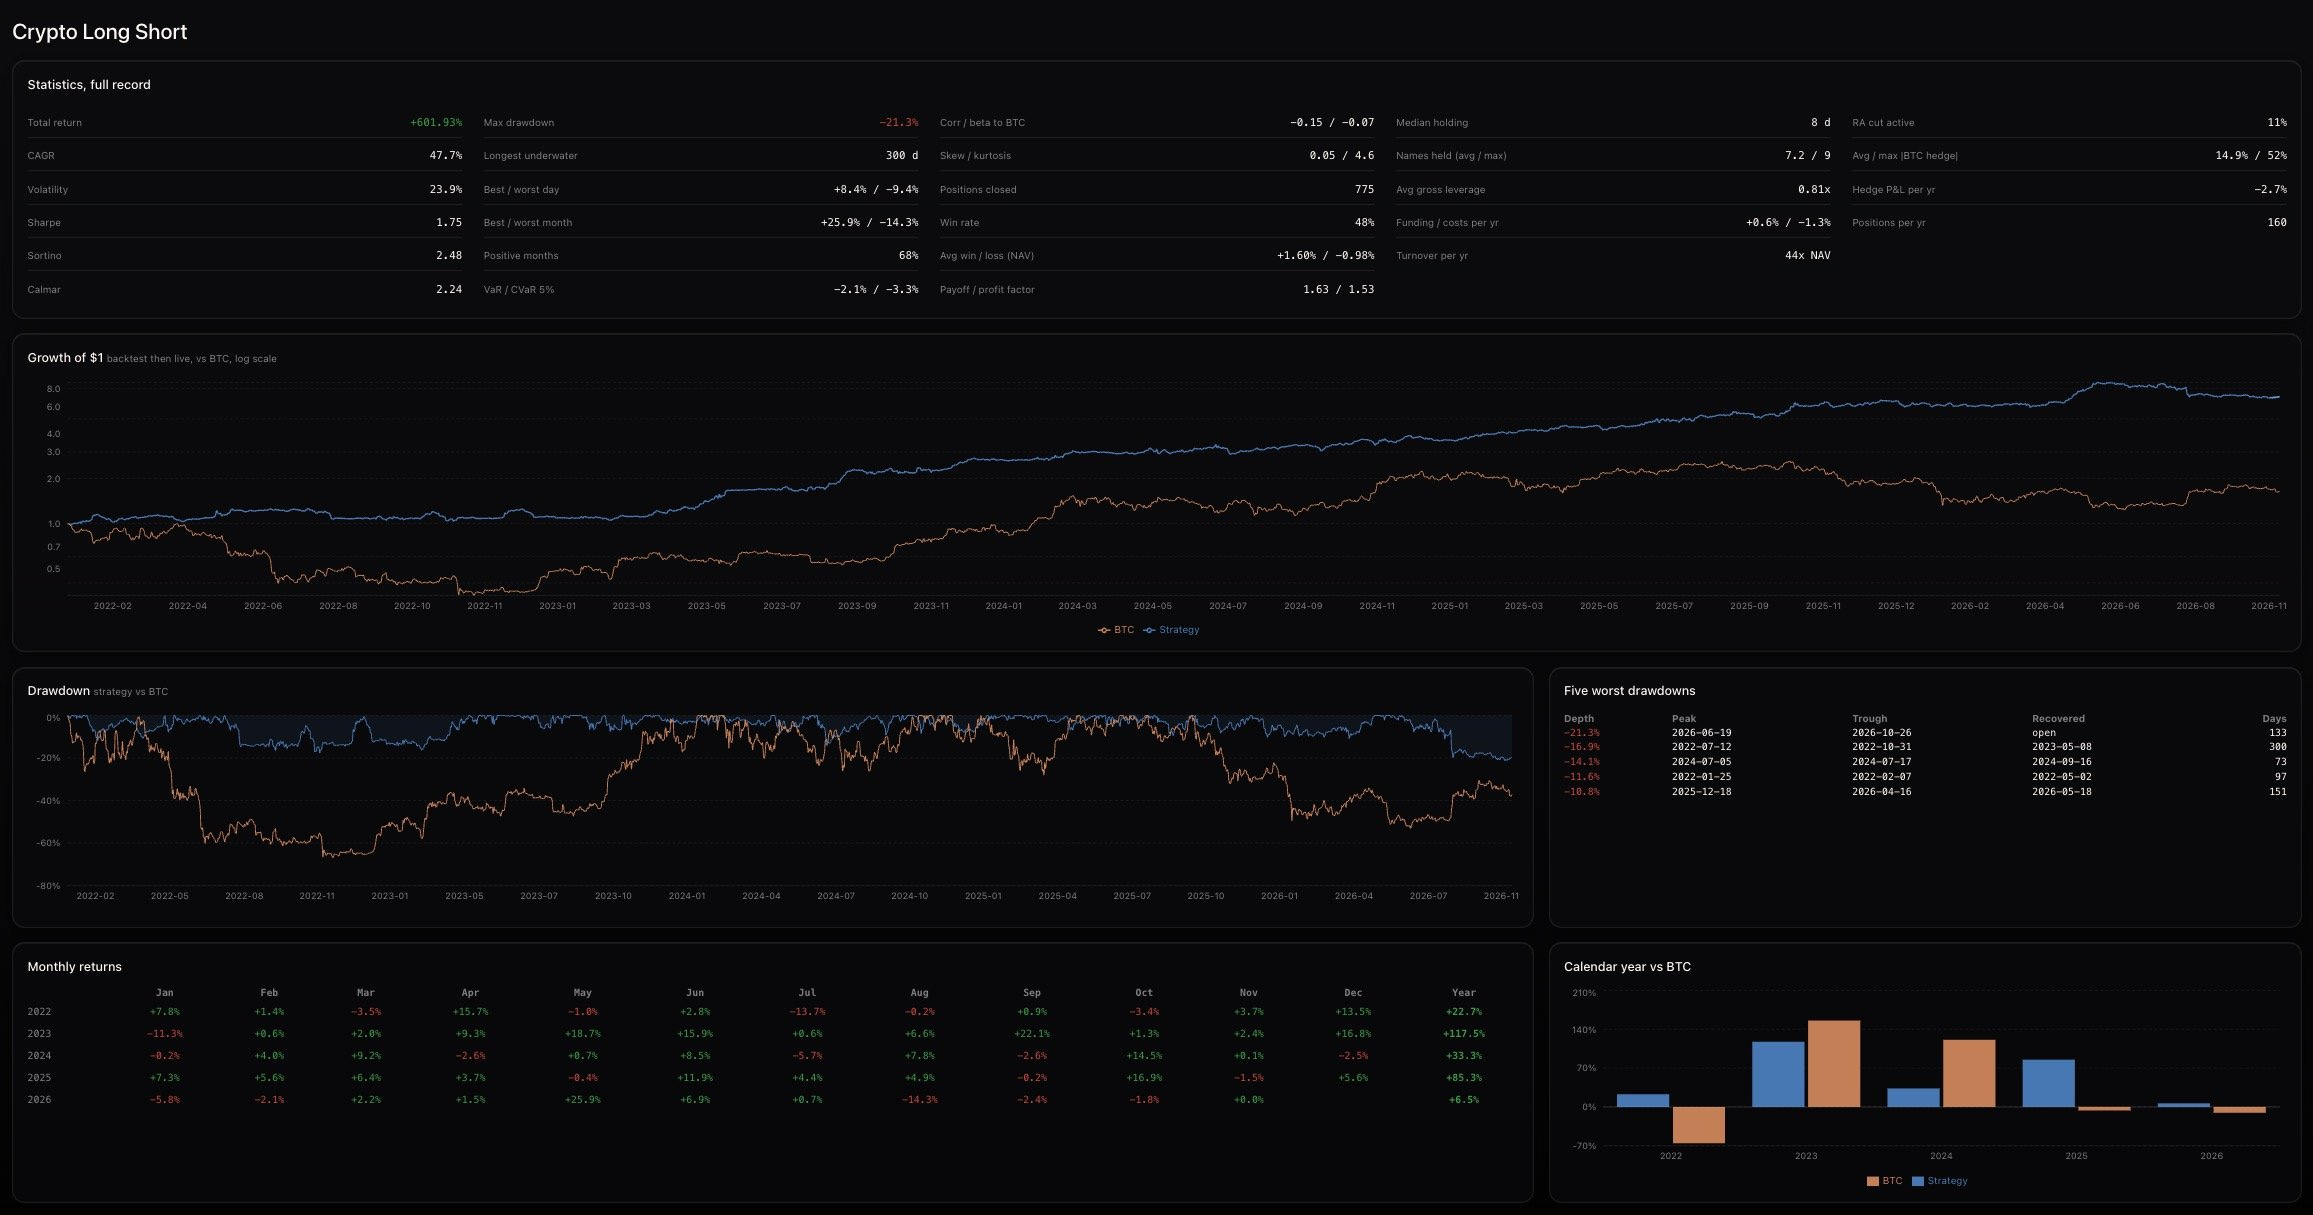
As a reminder, all data are coming from Tradingriot.com, those of you that decide to subscribe will get access to historical options and futures data for equities, commodities, rates, FX & digital assets. Distilled into daily signals, actionable strategies, and two pre-made portfolios to follow, with a newly launched crypto L/S strategy.
If you are interested in getting free market updates during the week, you can join a free read-only Discord.
Equities
This week the price caught on to the strong divergence in regime1. The regime fell every session from Tuesday and sits near the 11th percentile of its year, with now all components being negative.
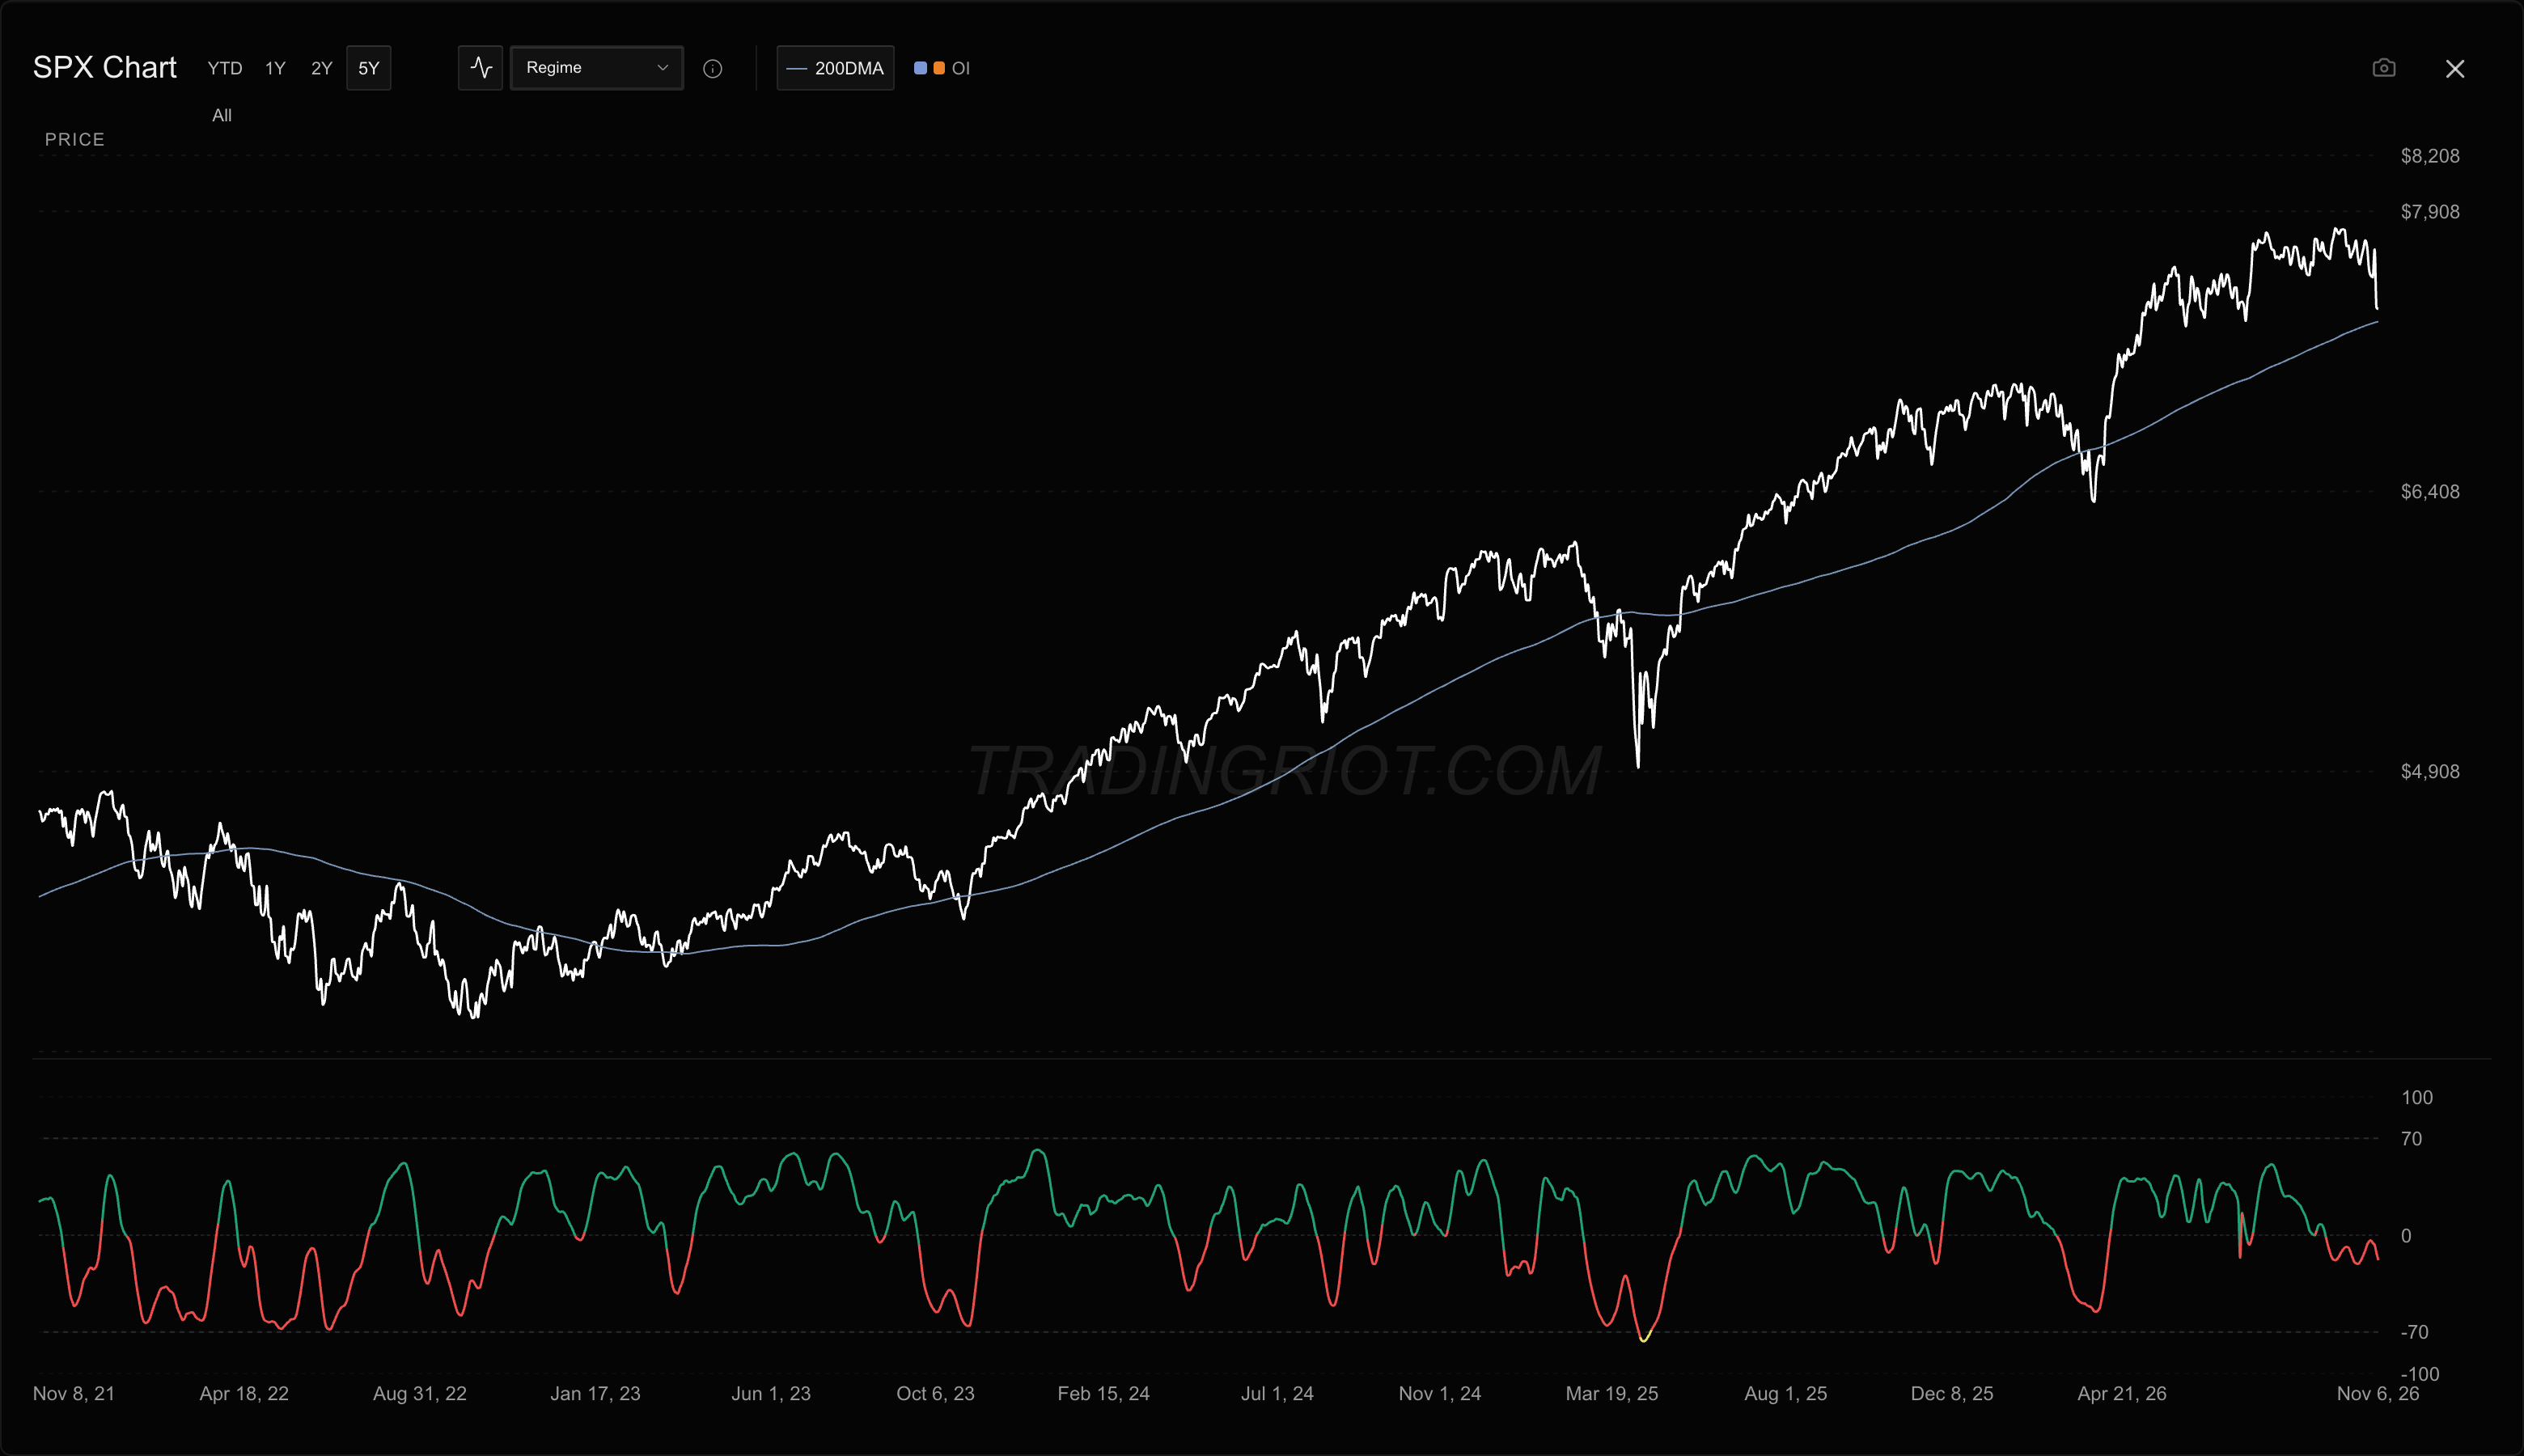
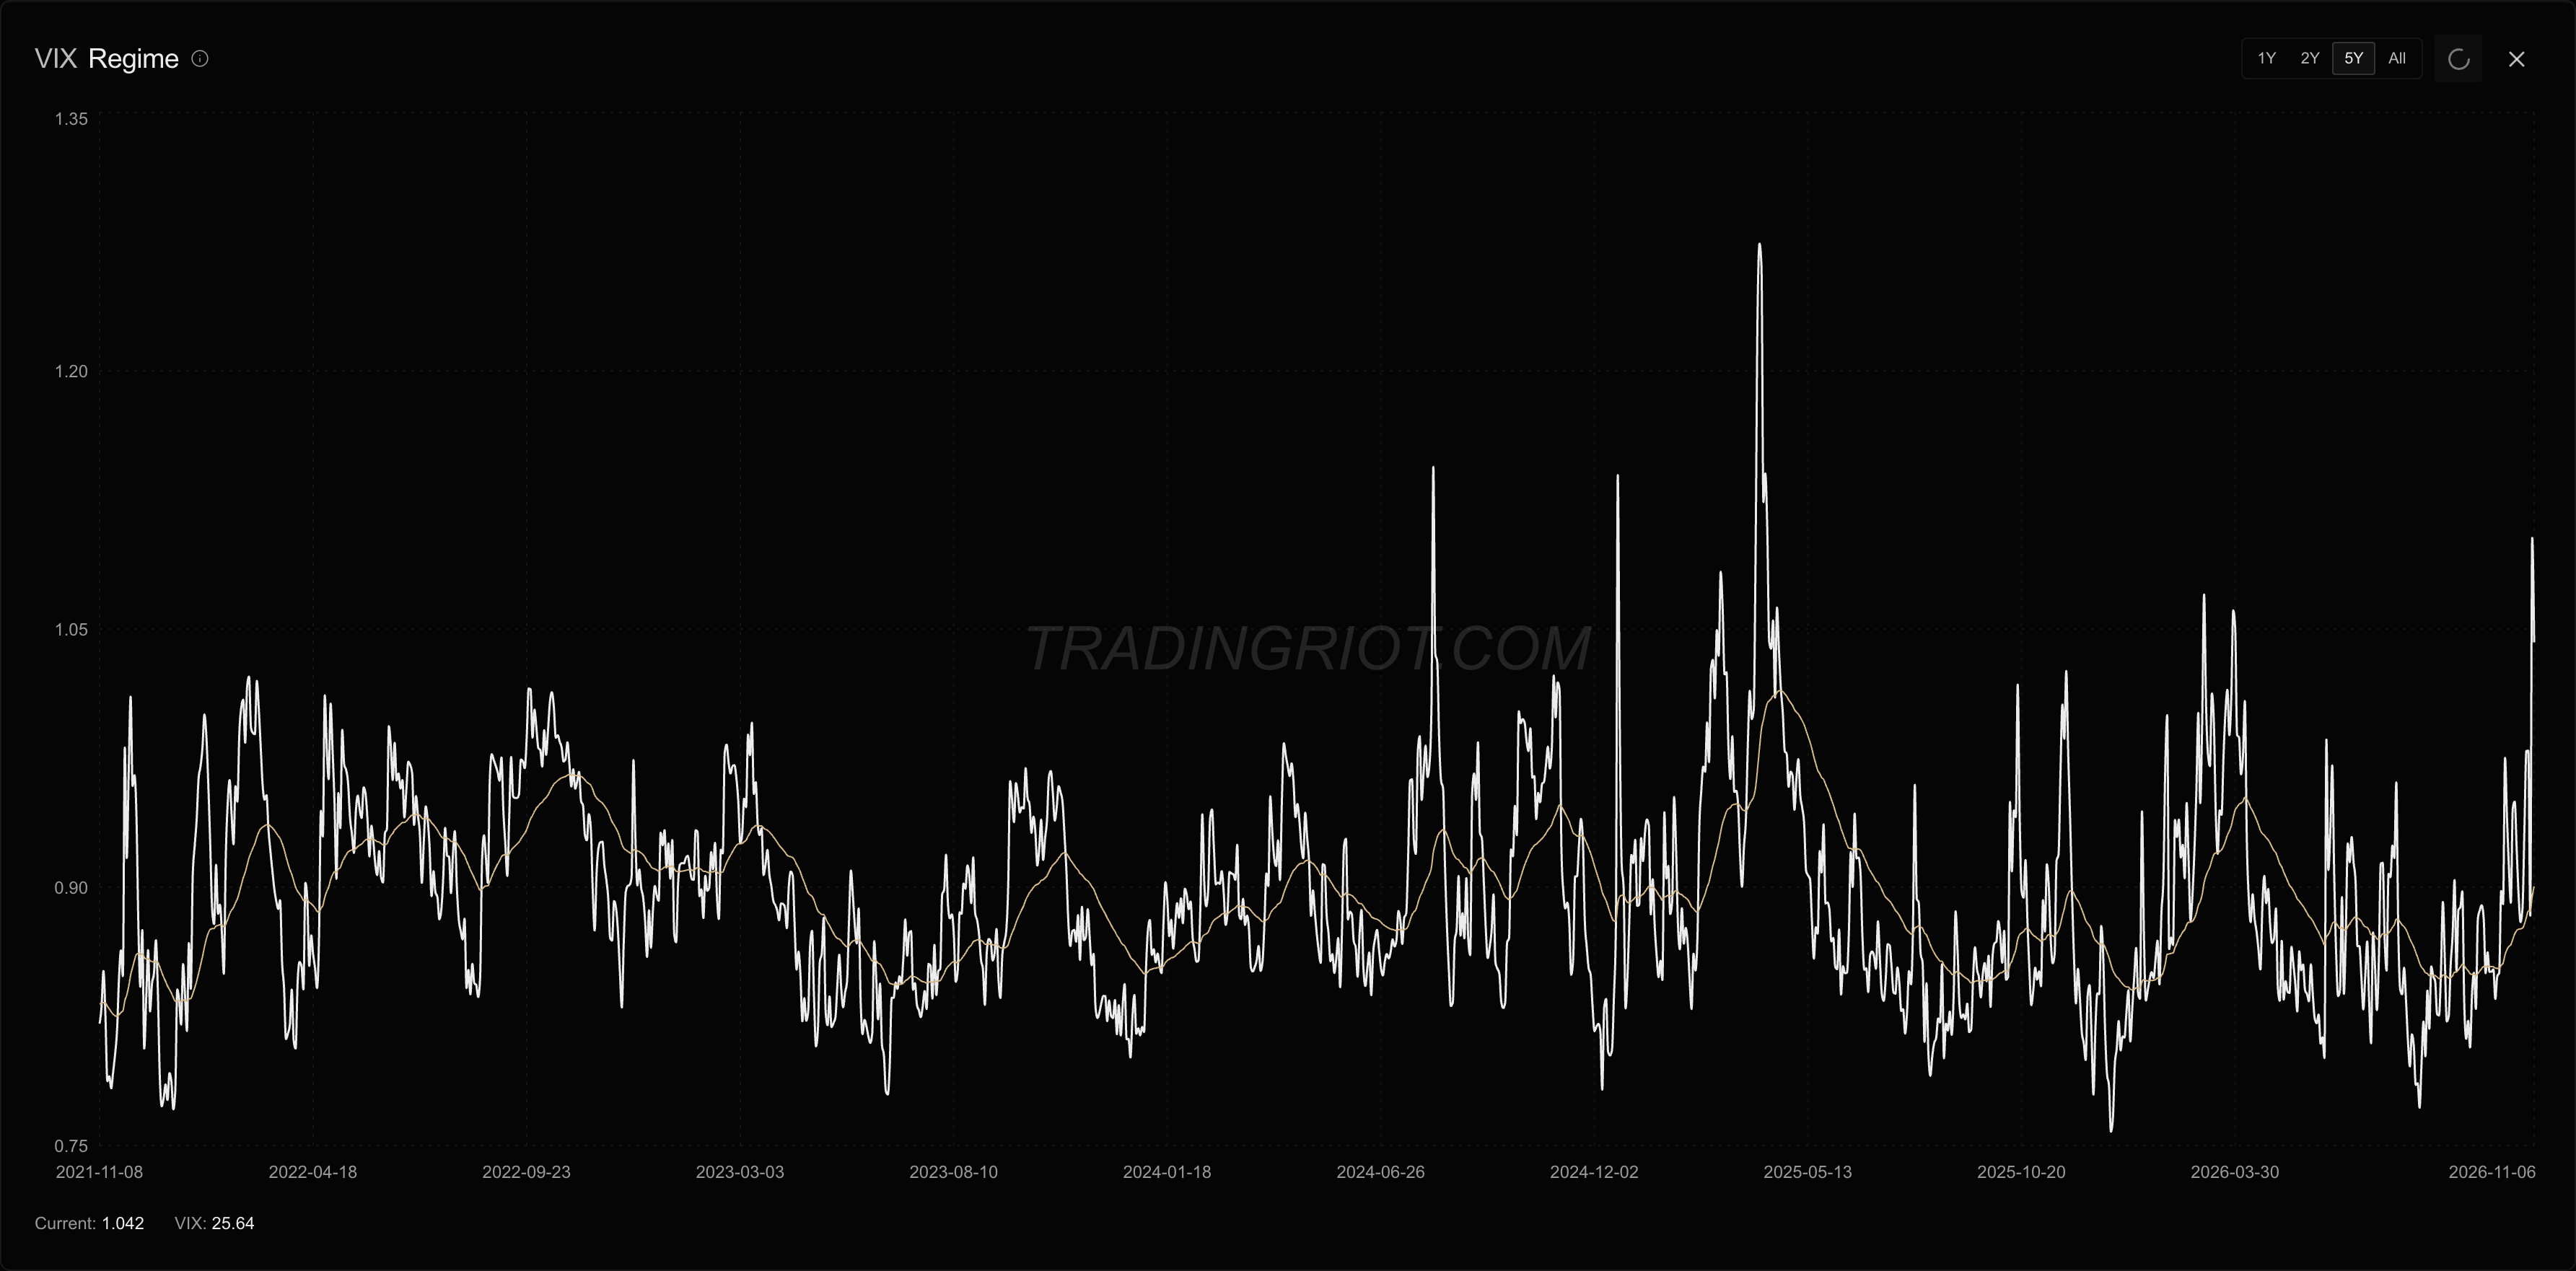
Last week I mentioned that I don’t see much of a panic yet; this week signs are definitely there.
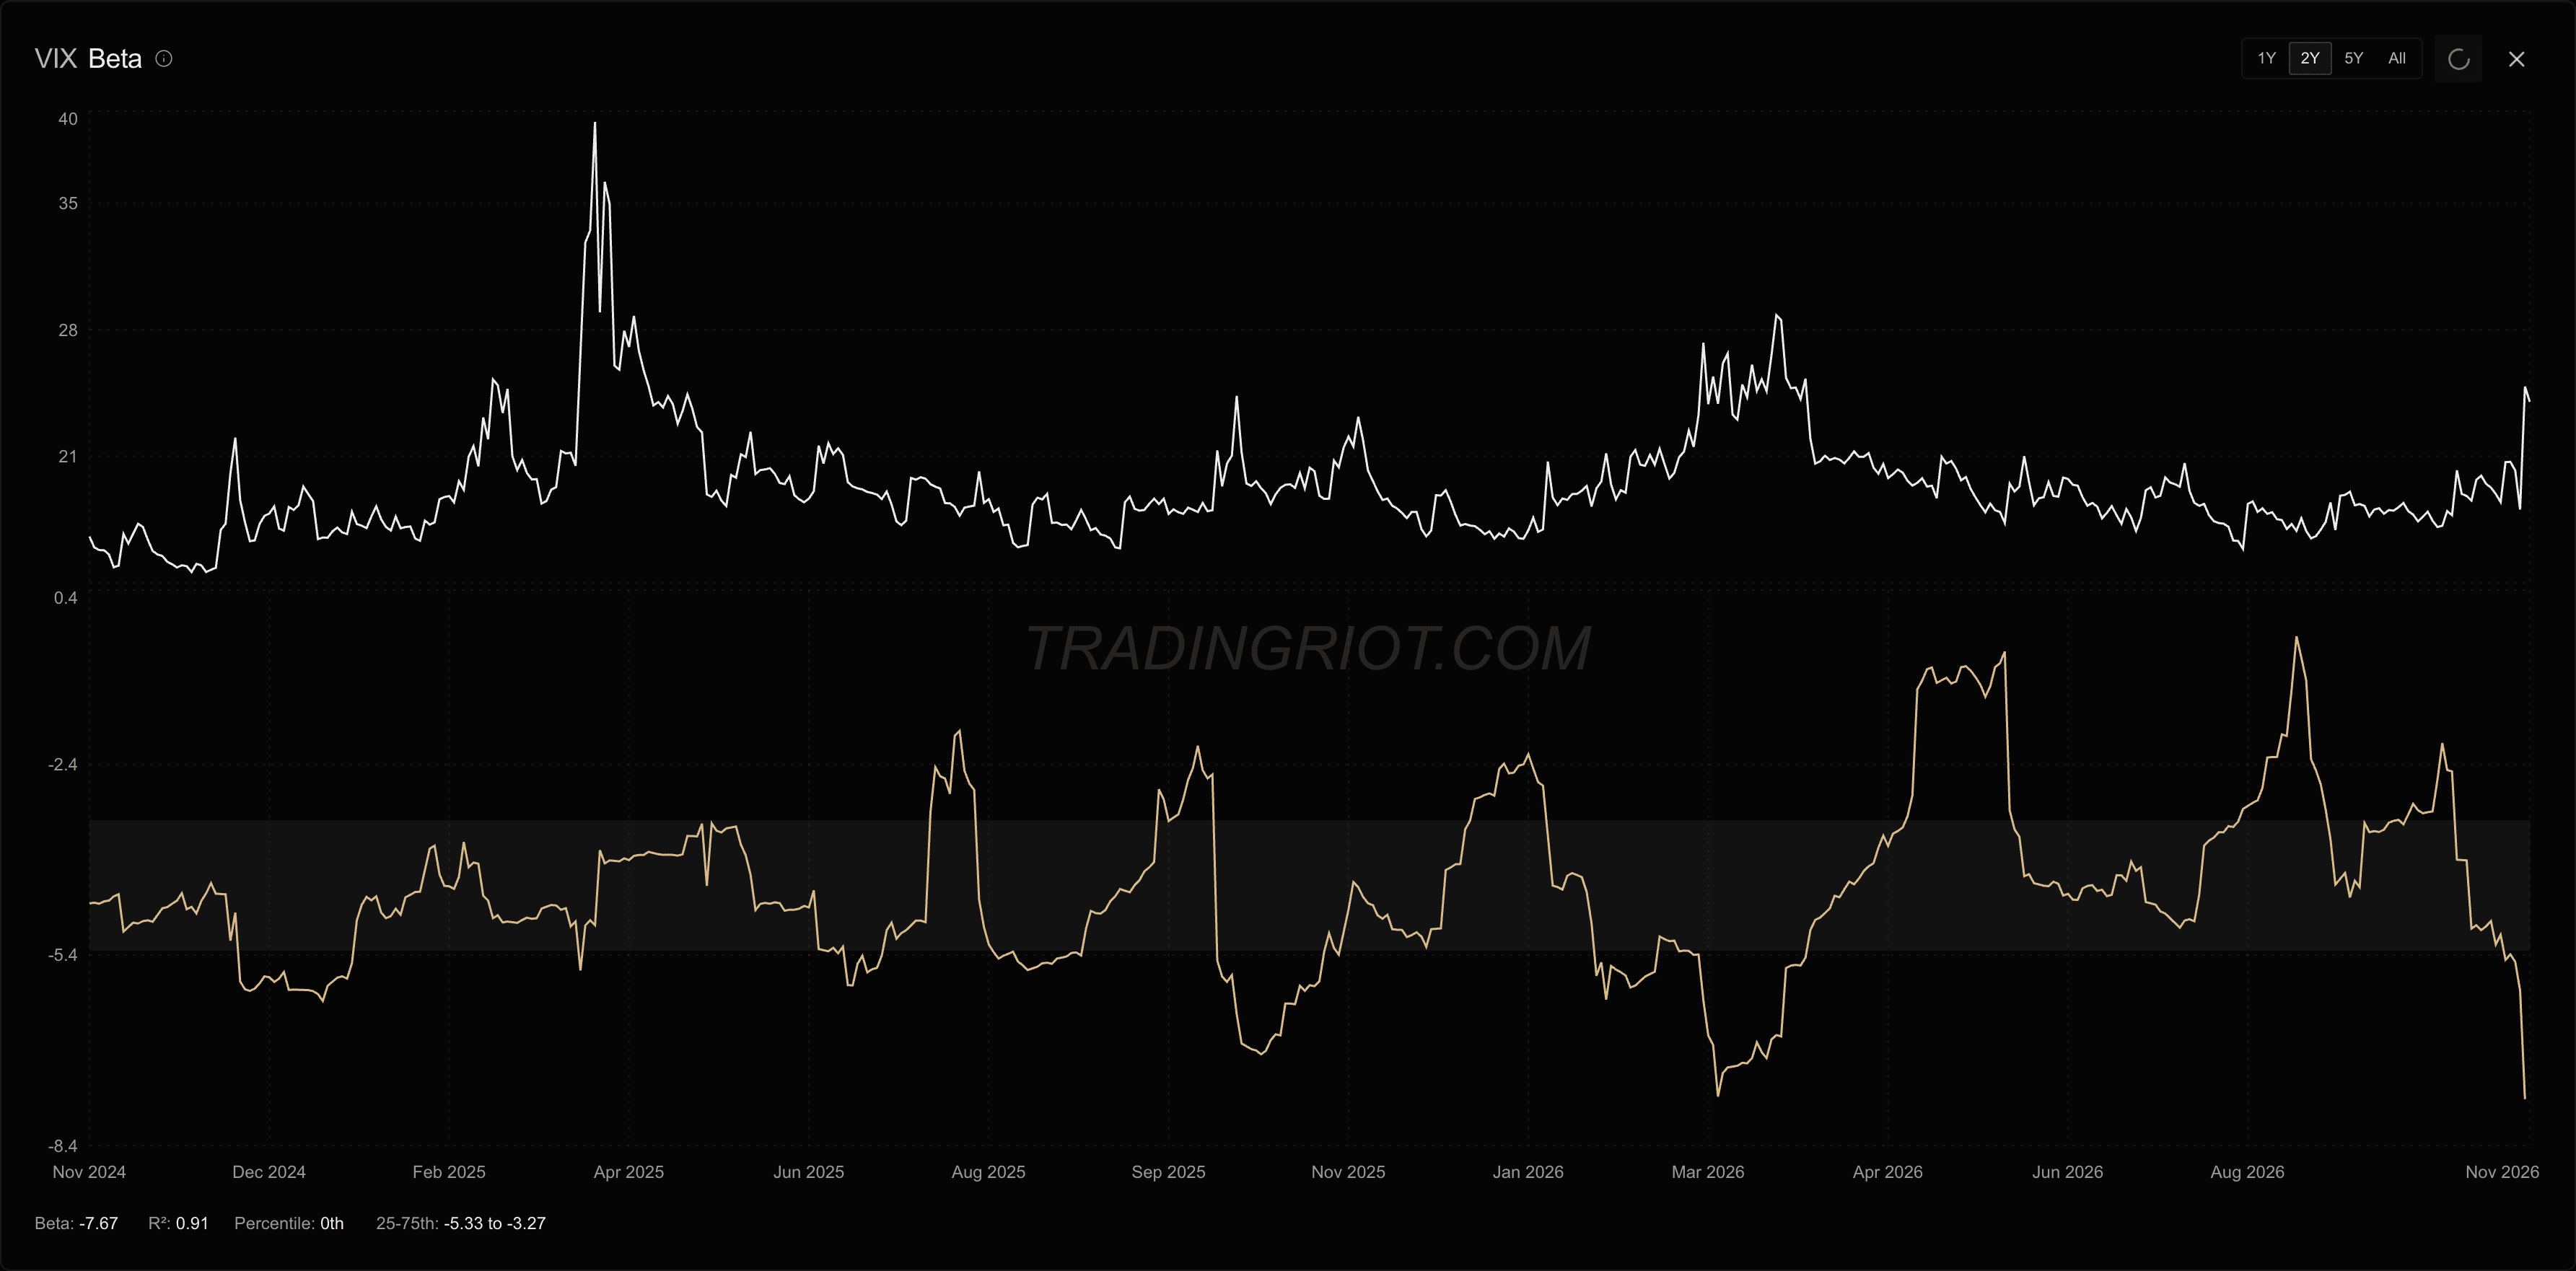
The sensitivity of the front-month VIX to SPX is also at its highest; it has been for over 2 years, as VIX moves about 7.5% for every 1% drop in SPX.
Credit has been risk-off since late October and slipped further this week, so it hasn’t given the all-clear either.
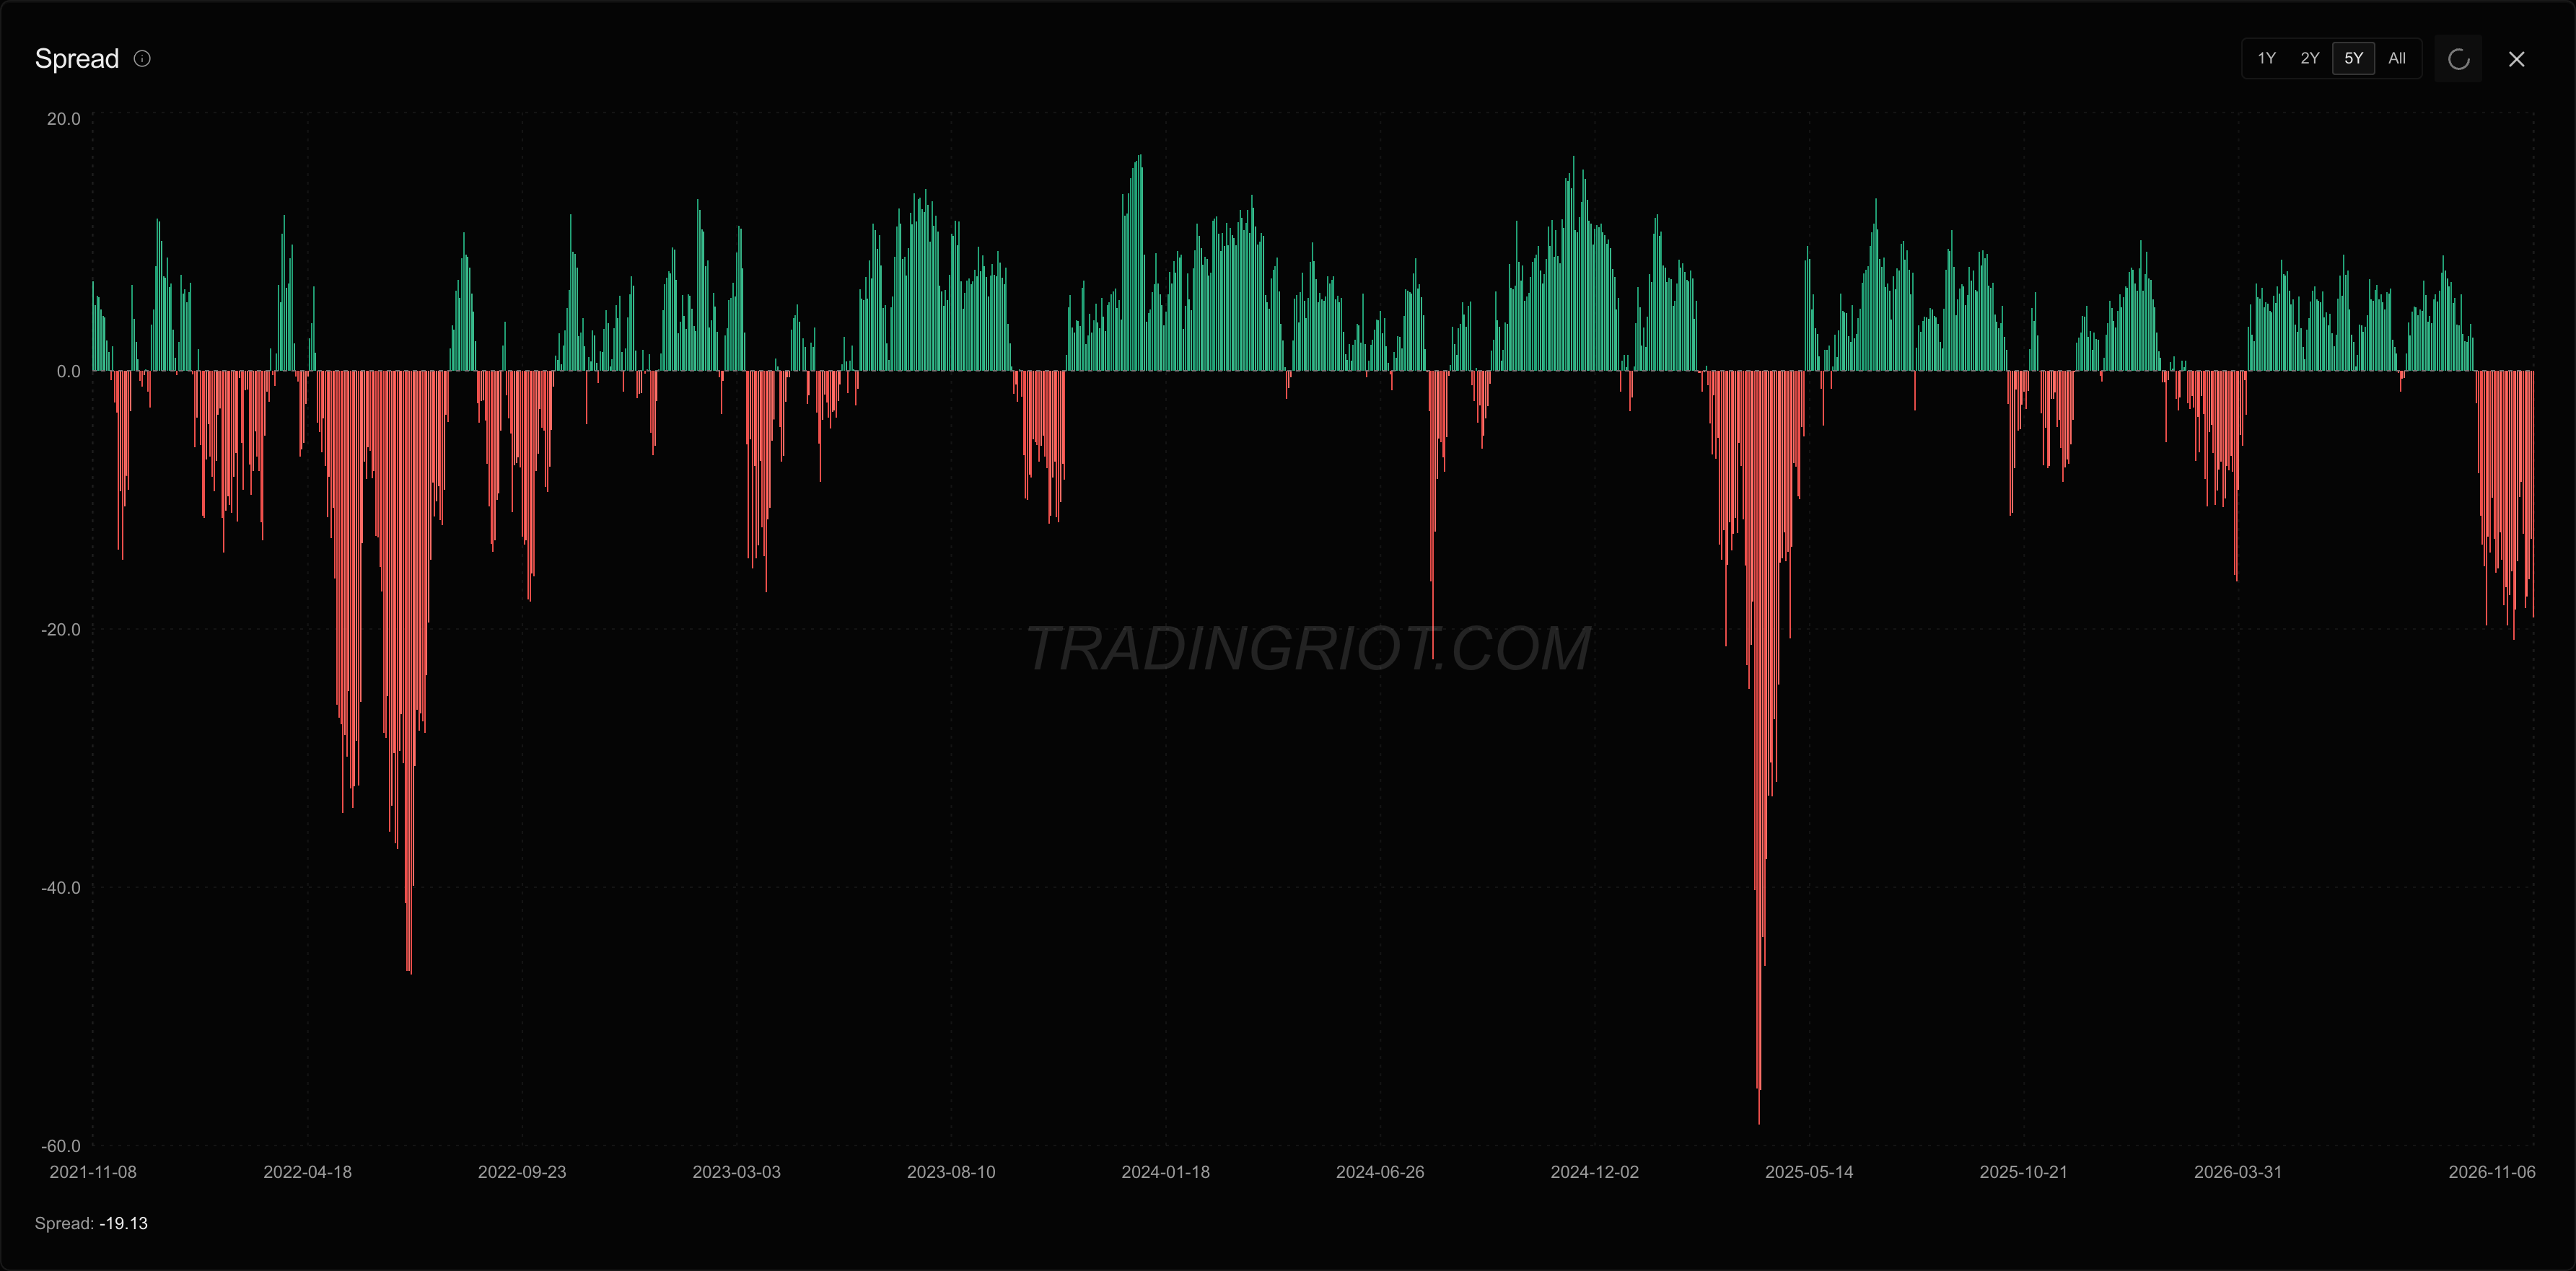
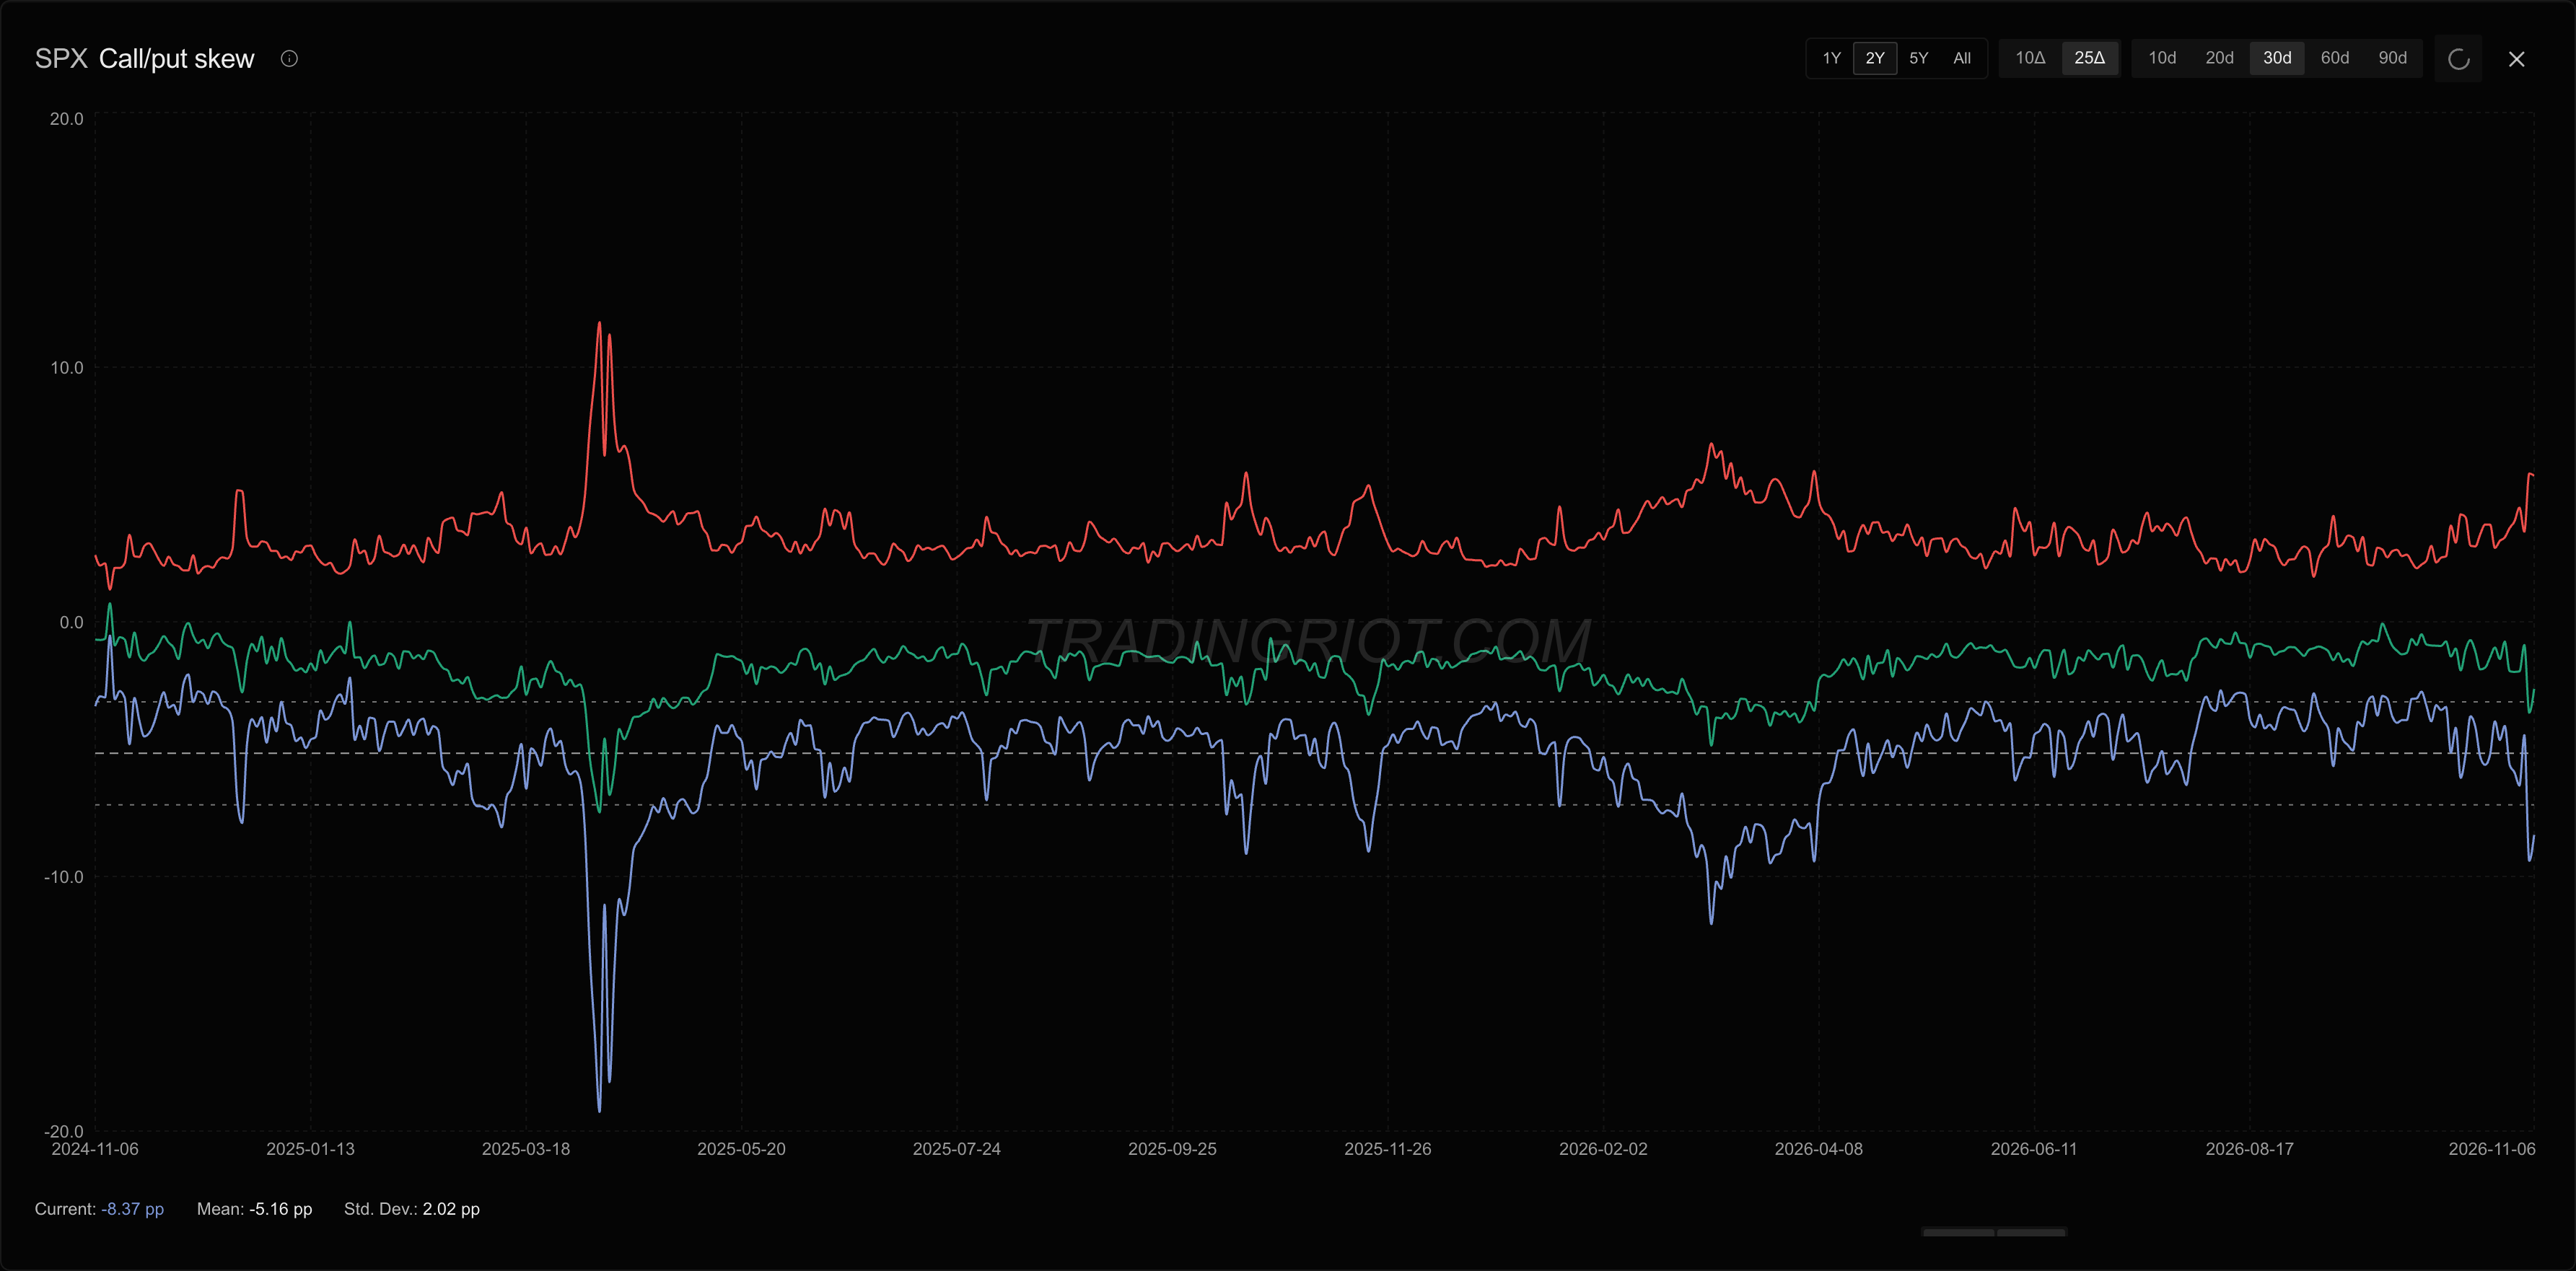
Overall, all indicators are undoubtedly stretched, but it’s not screaming for the end of the world just yet, which can also be seen in skew.
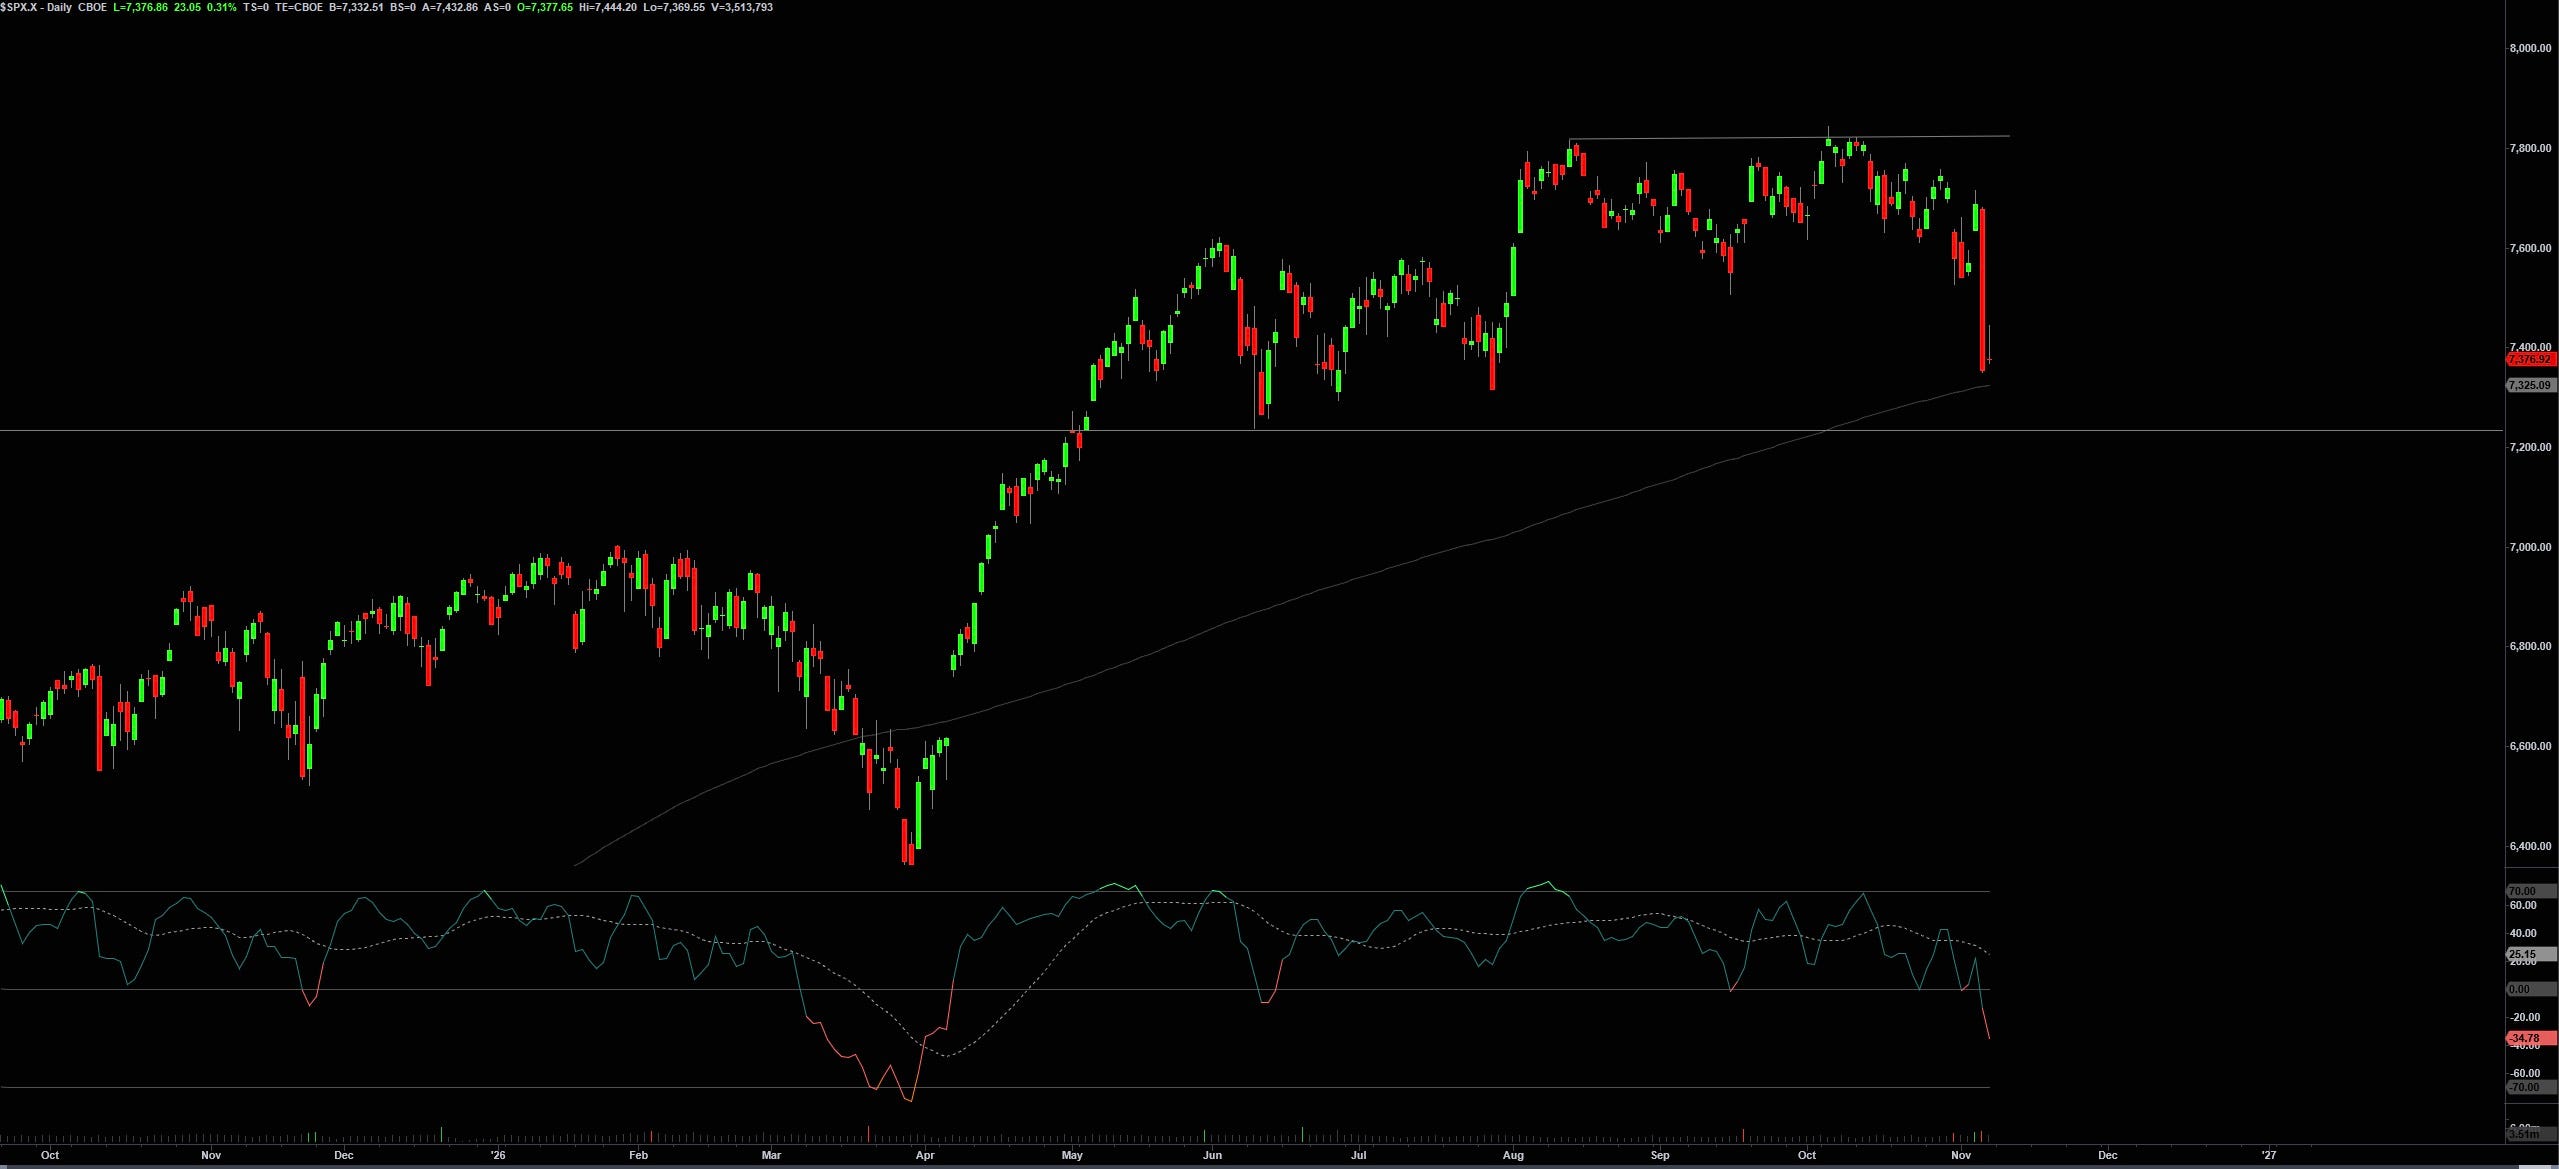
Besides watching my systematic portfolio not having great time, I am not in a rush to buy the dips yet; the area where I would be interested is around 7200 below 200-DMA.
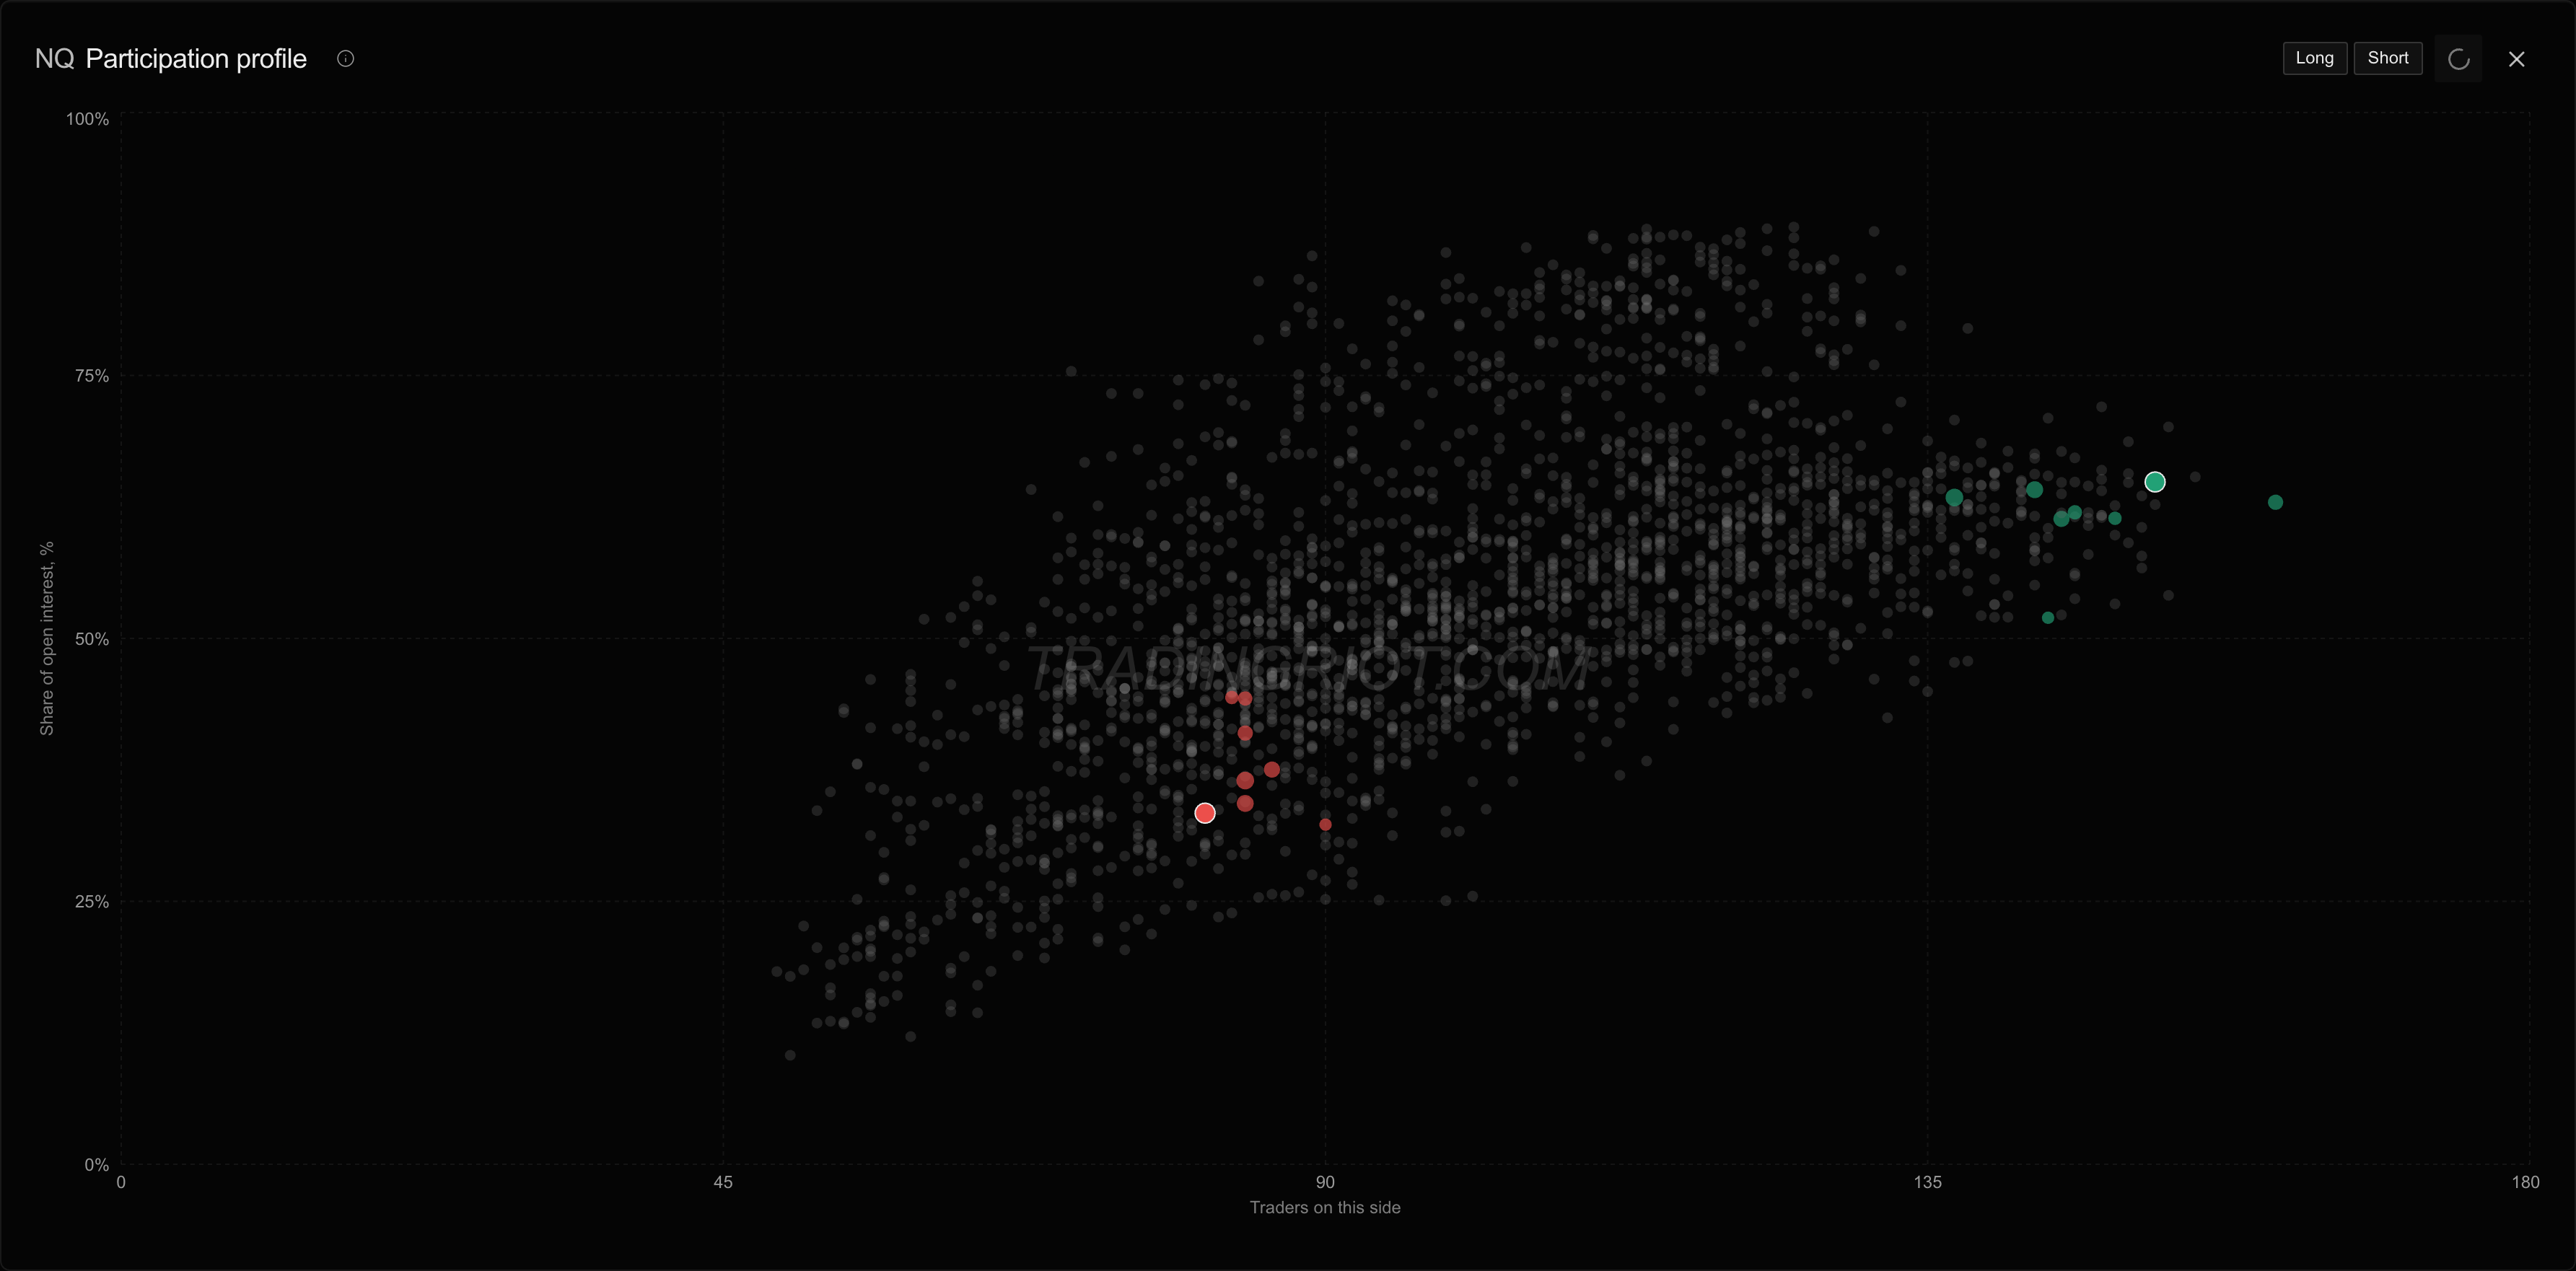
What I also find not ideal is the fact that Nasdaq has had the highest net-long positioning in futures from large speculators over the year, so it seems like dips are already being bought too aggressively there.
Sectors
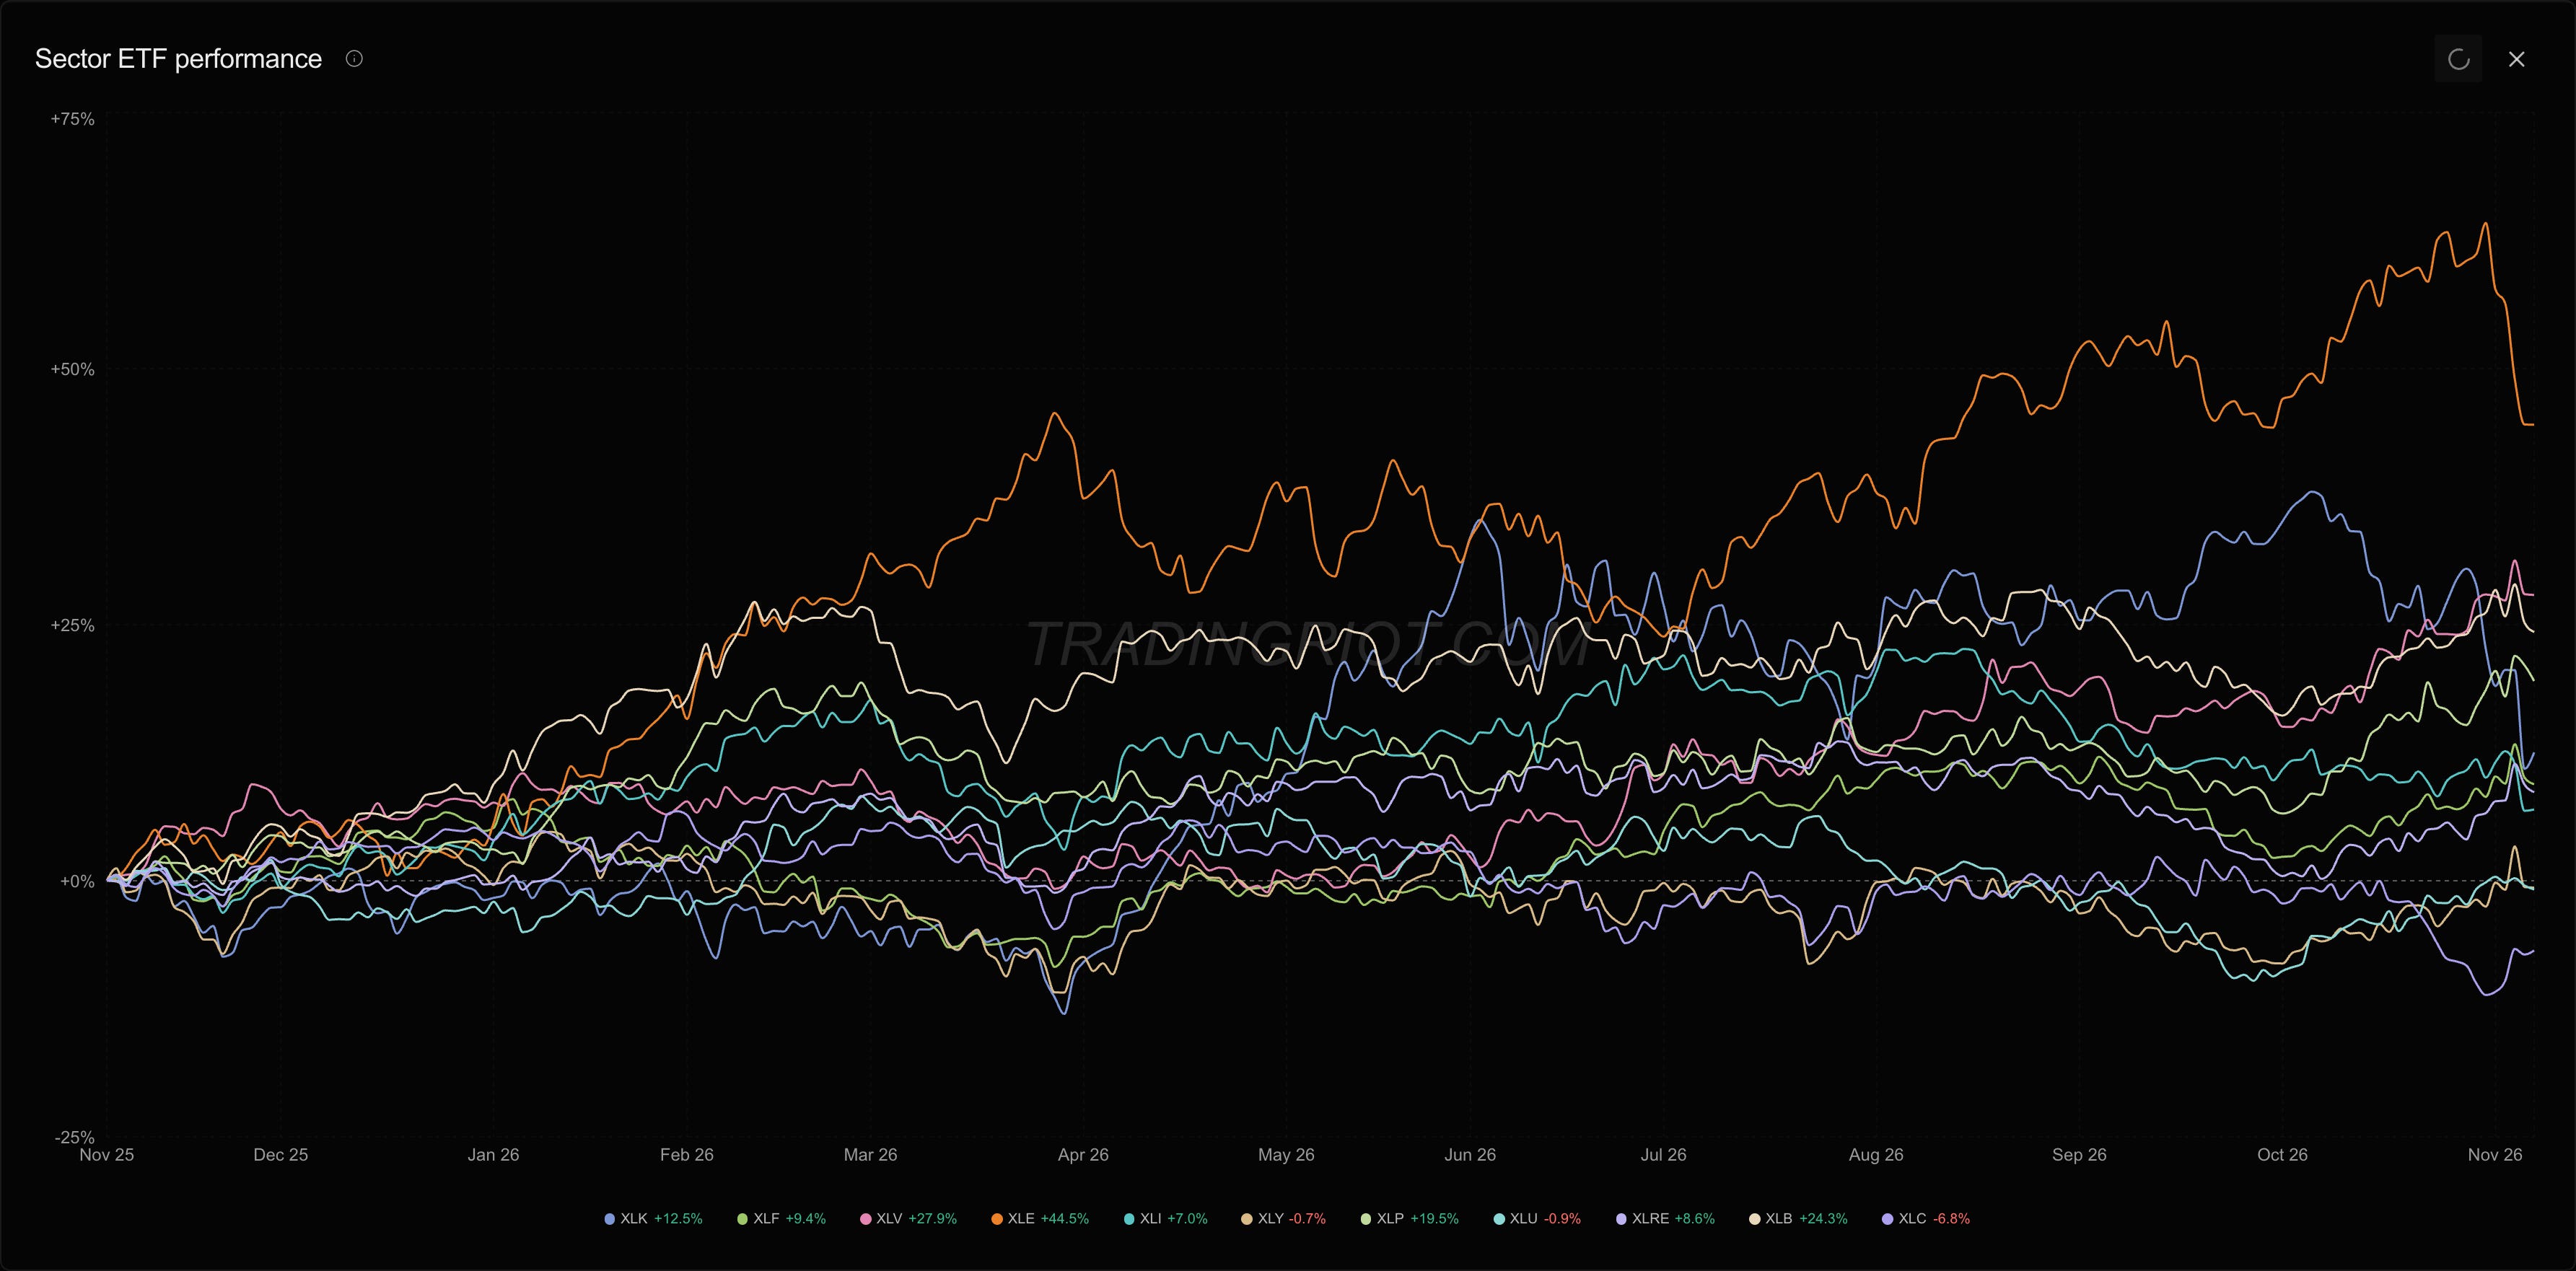
The rotation out of tech kept going. Over the month XLV is up about 10%, staples and real estate about 8%, while XLK is down 17% and SMH 24%. This week energy joined the losers with oil, XLE down 12%, and small caps lost less than the Nasdaq, with IWM down 2% against QQQ down 5%.
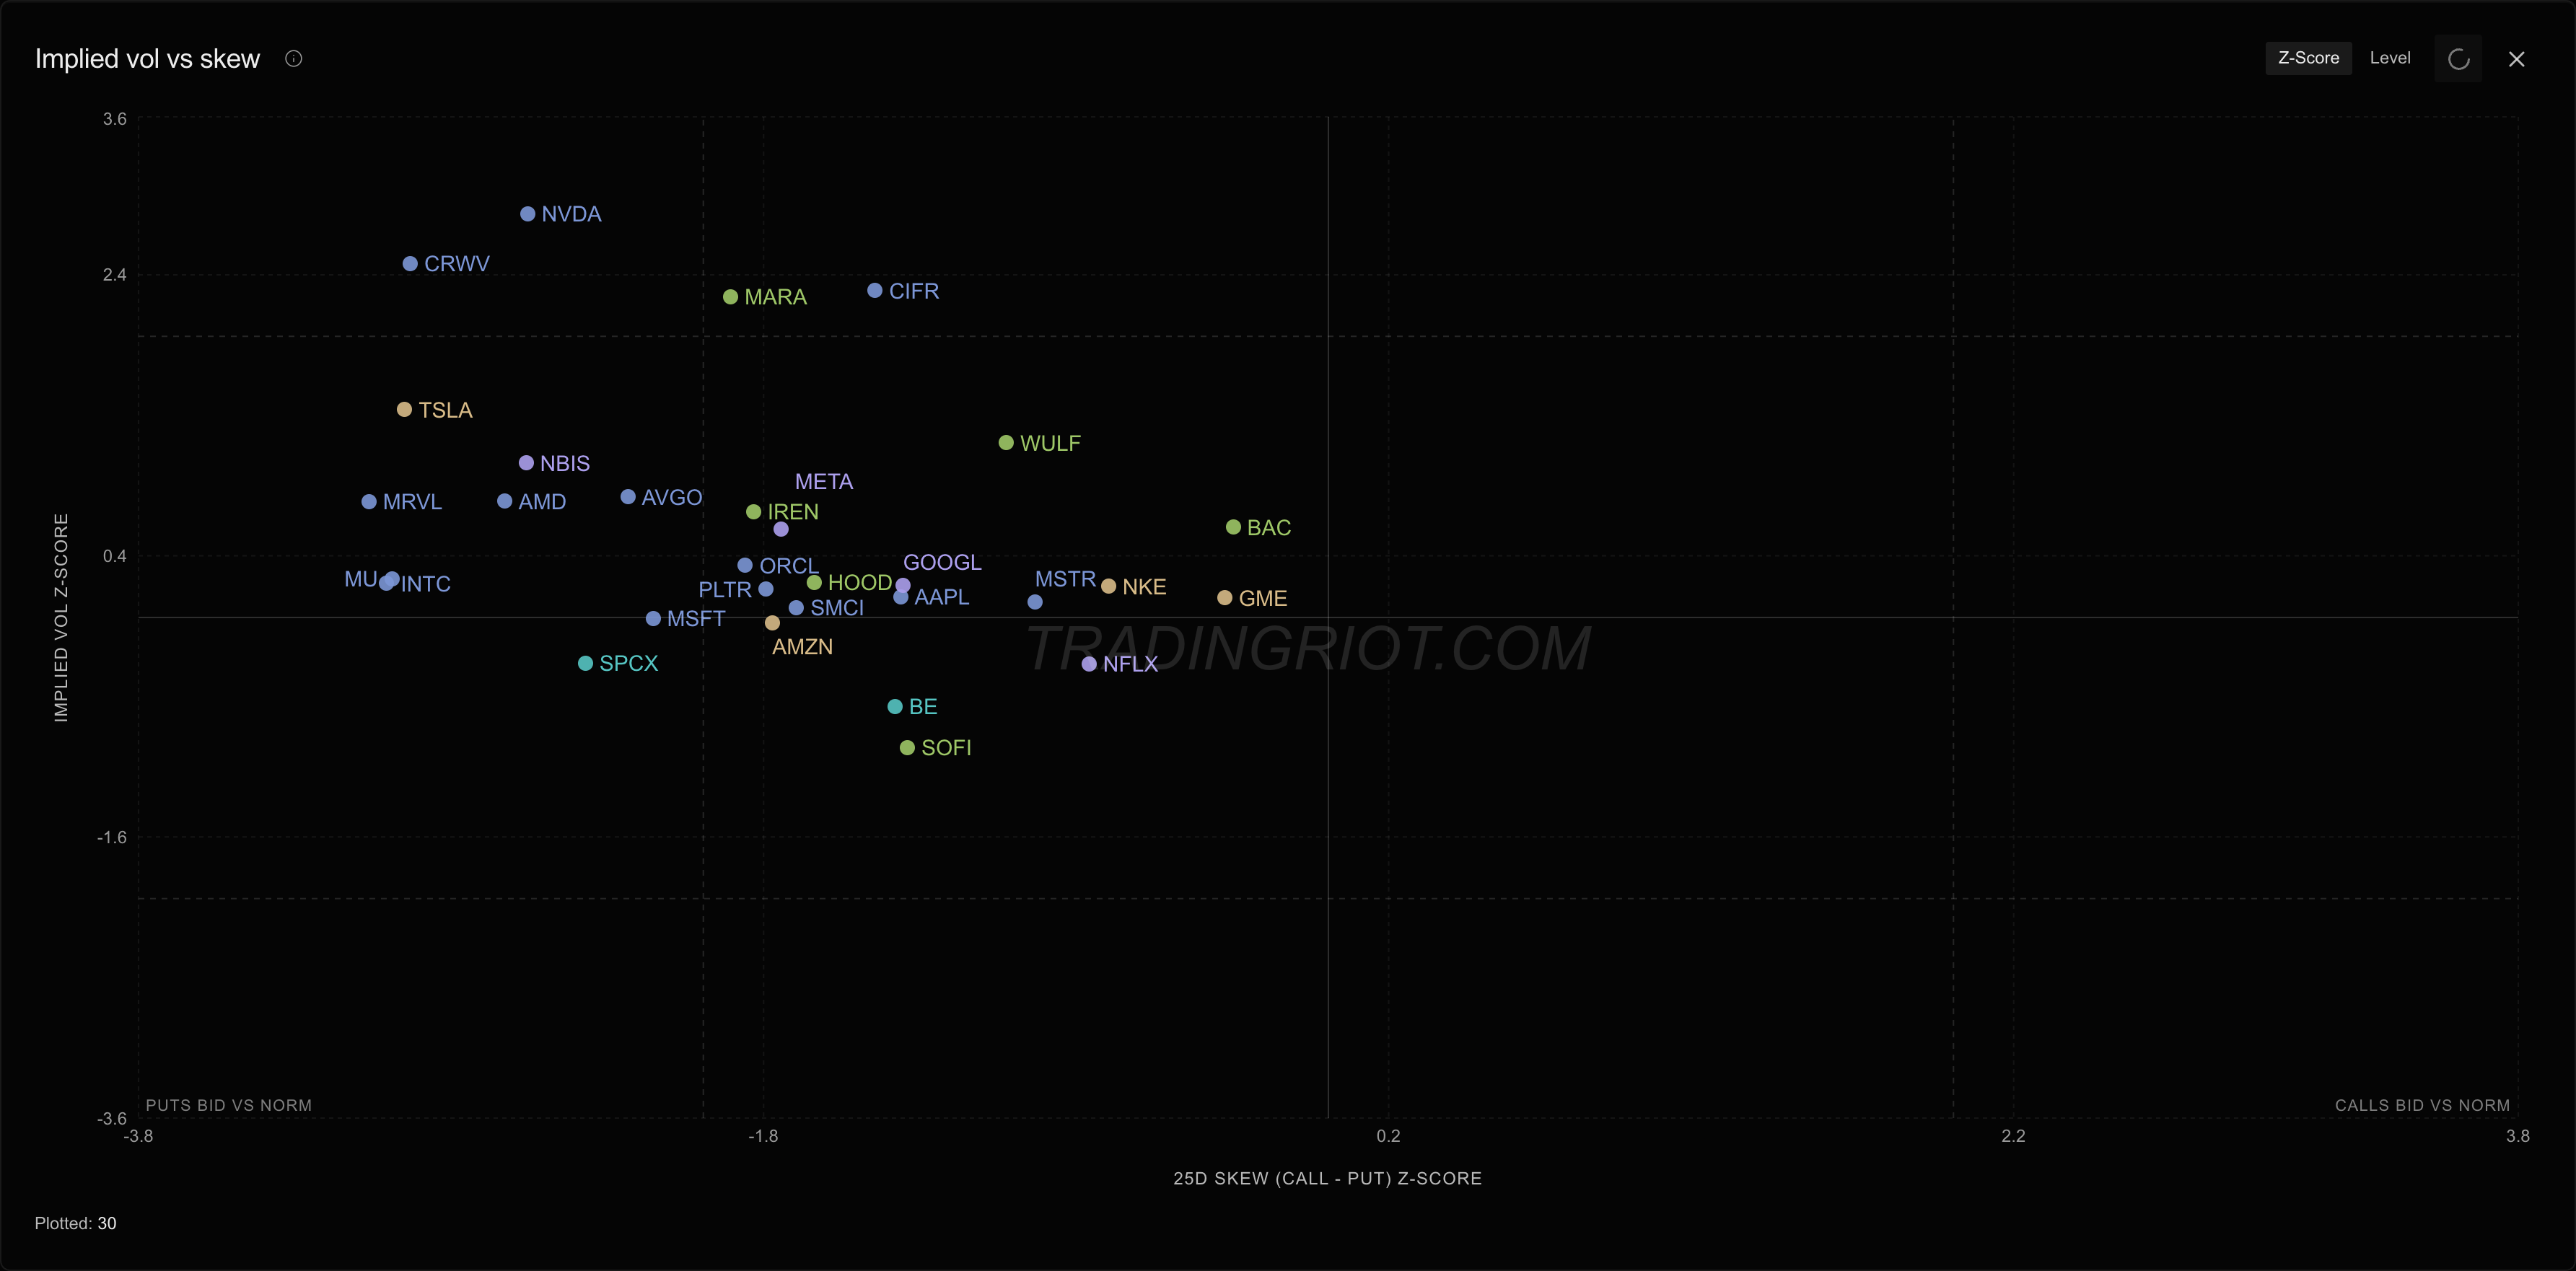
The damage sat in memory and AI hardware, with many names losing close to 30%. Options went the same way: puts are bid across the chip names, with skew at the bottom of its year in Micron, Marvell, Dell, Nvidia and AMD.
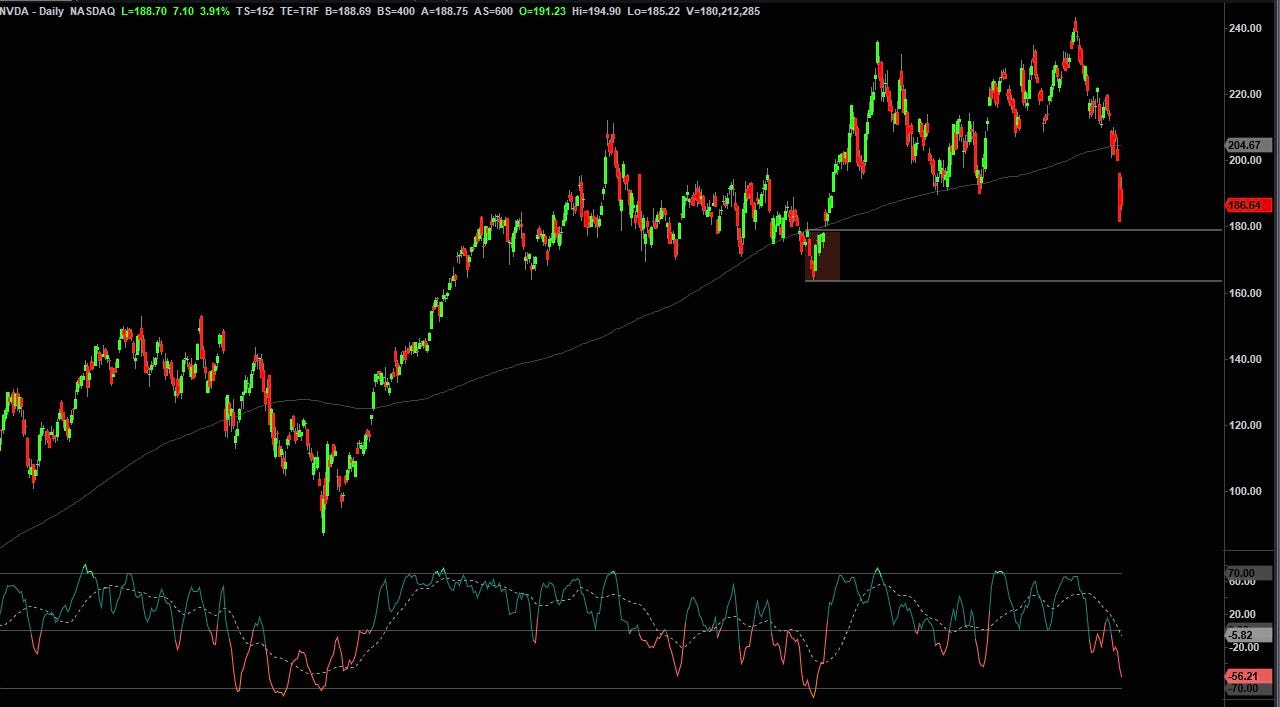
If you want to play a hero and feel like catching a falling knife, NVDA looks most constructive to me from the names mentioned, as it is heading into the structure below the price.
Earnings
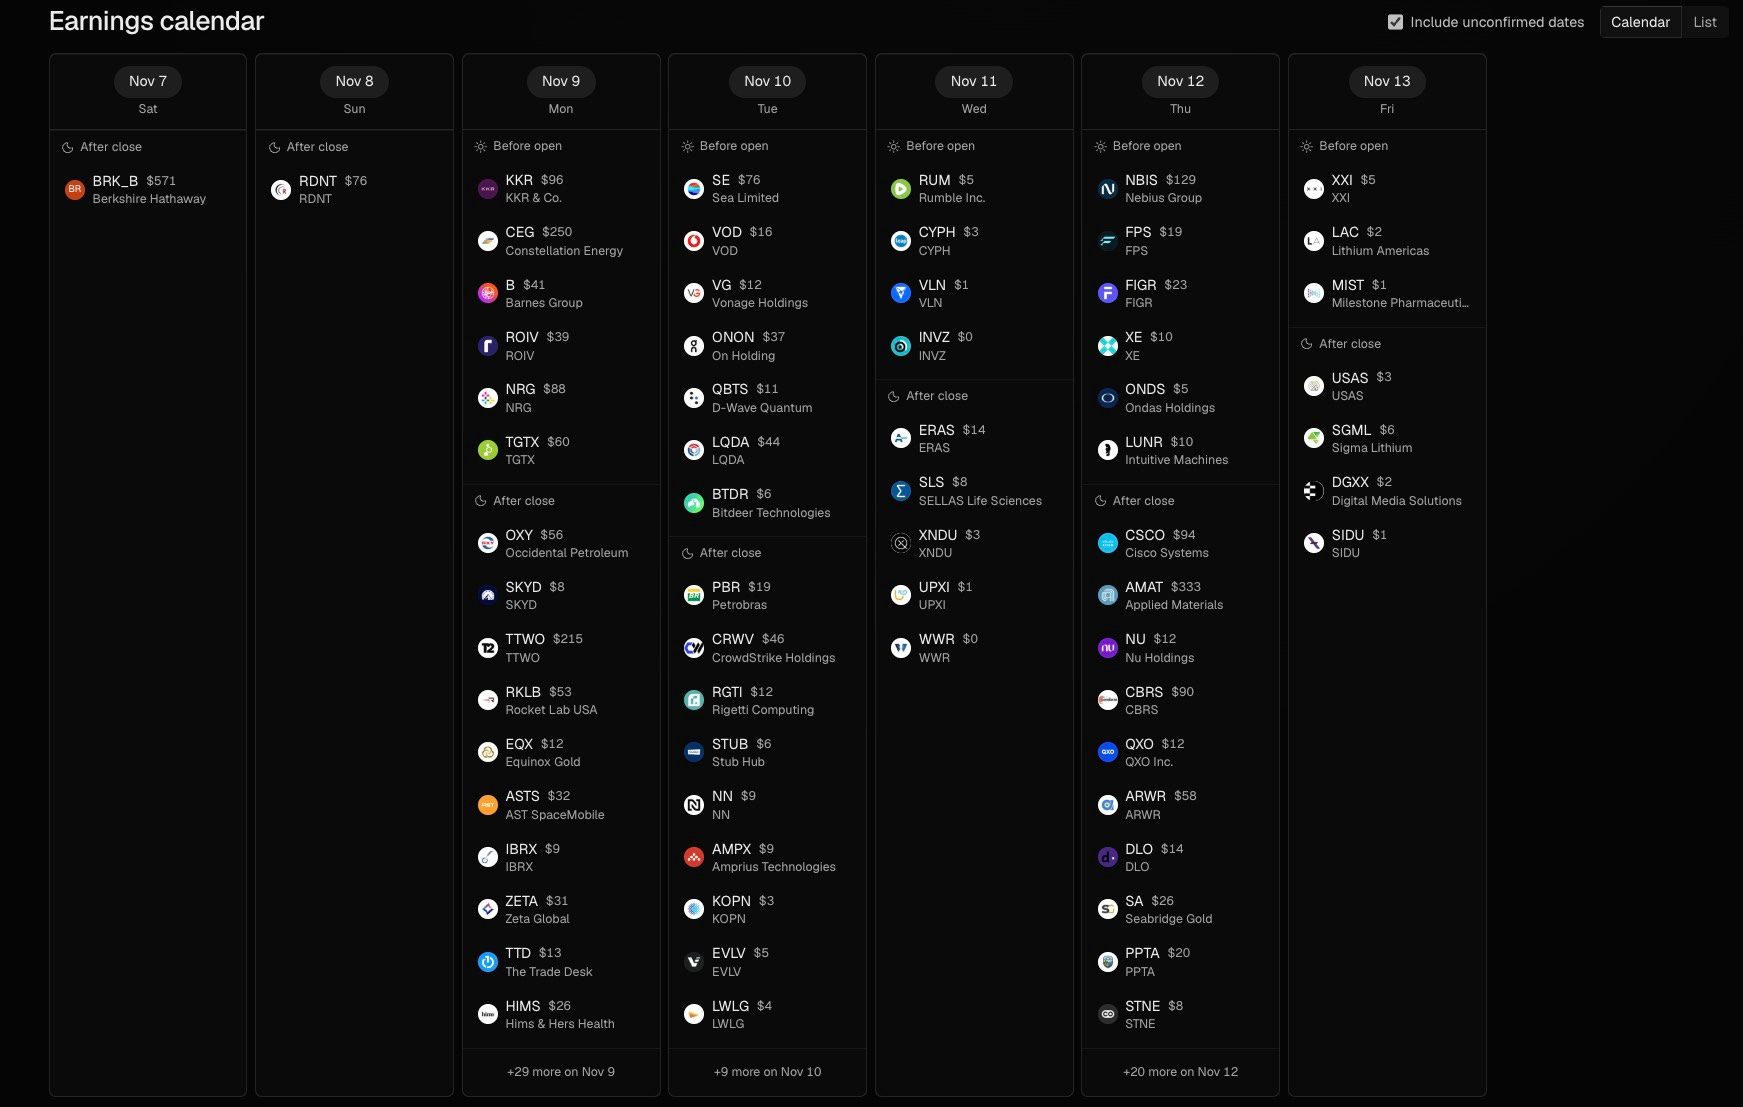
Next week the AI read-through continues. CoreWeave reports Tuesday with the options pricing about 17.8% against its usual 14.8%. Nebius is priced at 16.3%, nearly double its history, and Applied Materials and Cisco are both priced well above theirs too, so there are several solid opportunities for trading vol around the events.
Crypto
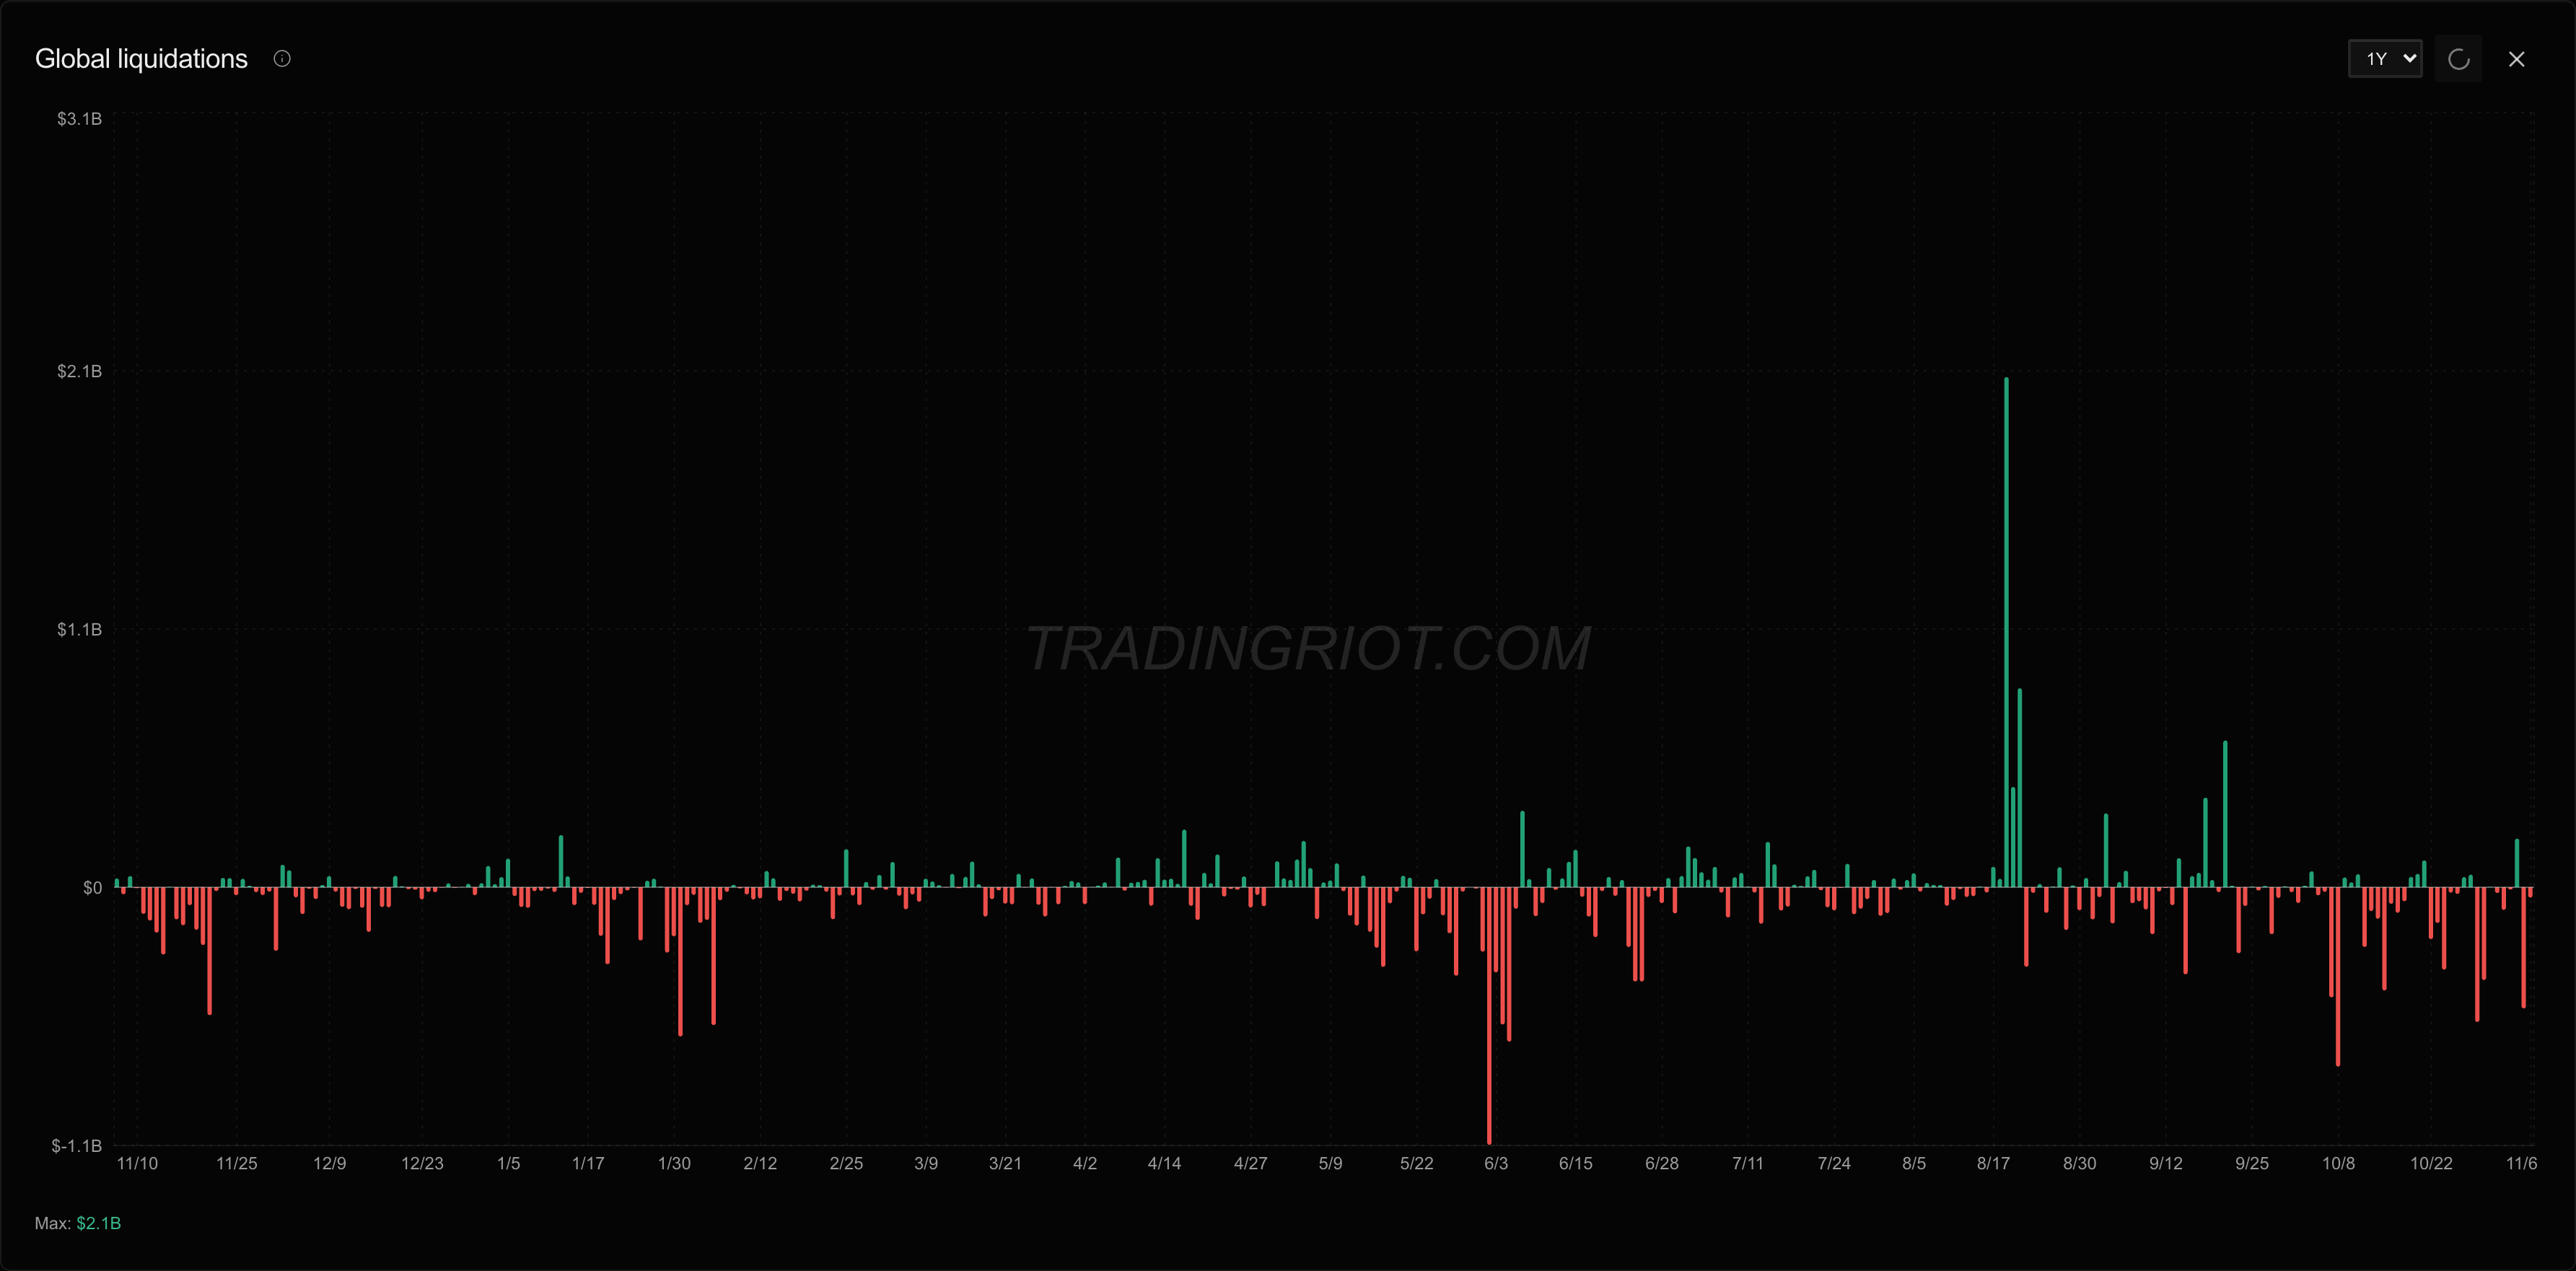
Spot ETF outflows erased what was left of 2026’s net inflows, more than a billion dollars in longs got liquidated, and the Trumps’ memecoin went to a record low the day after the election.
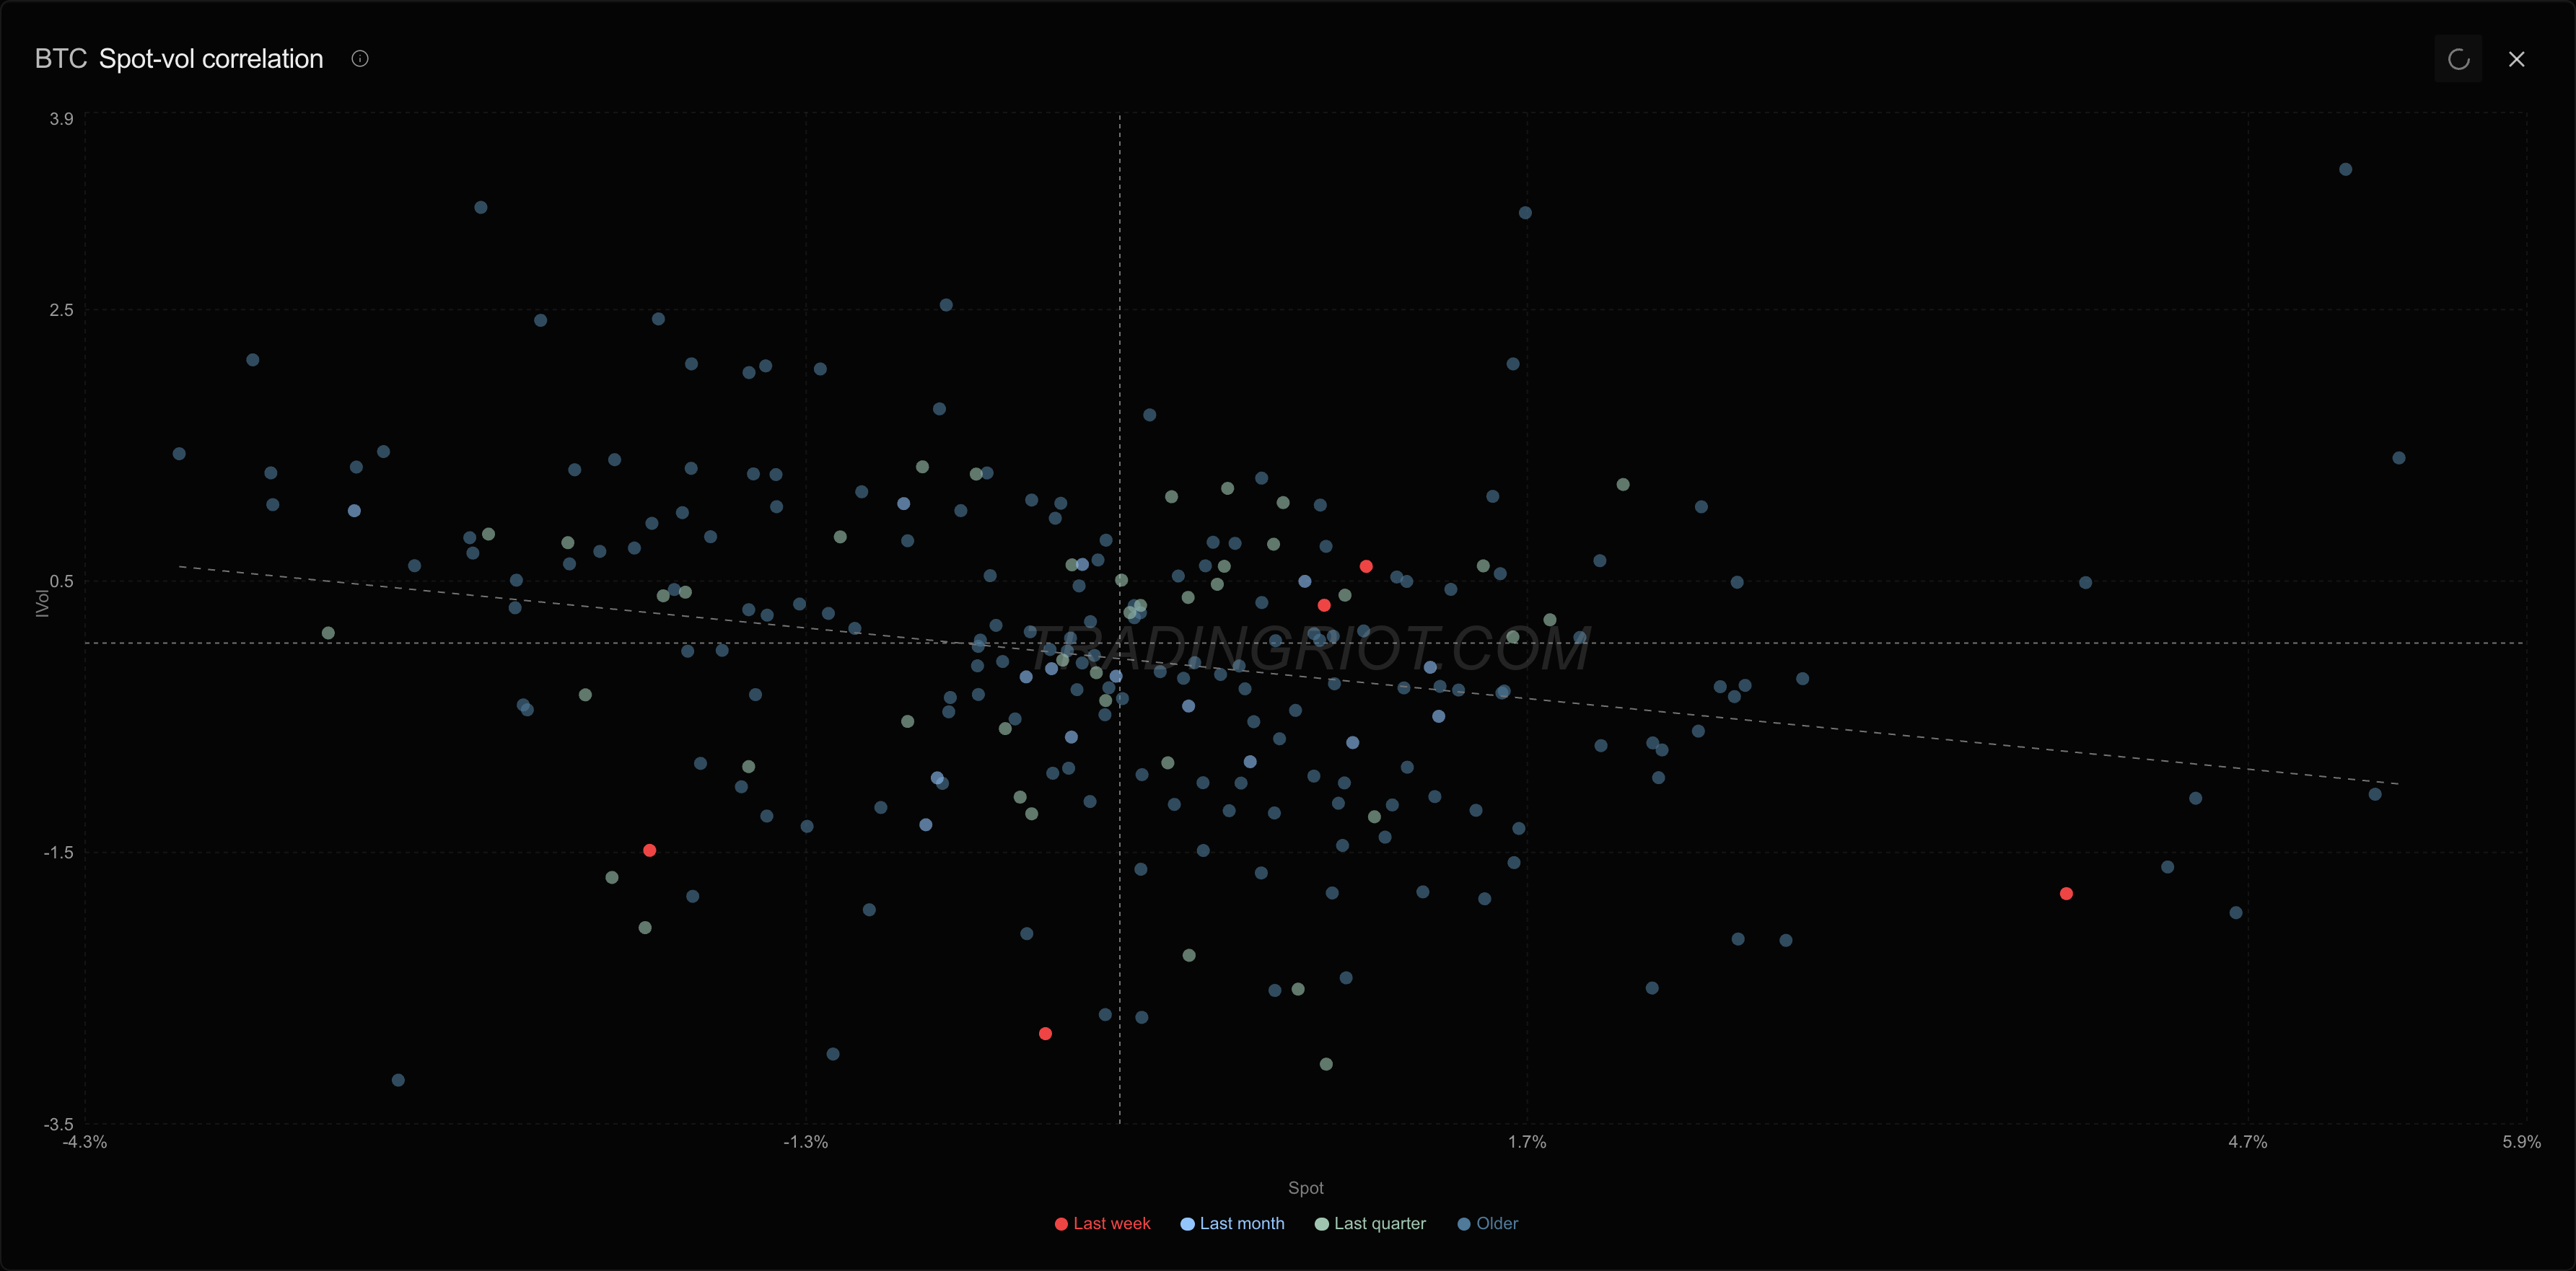
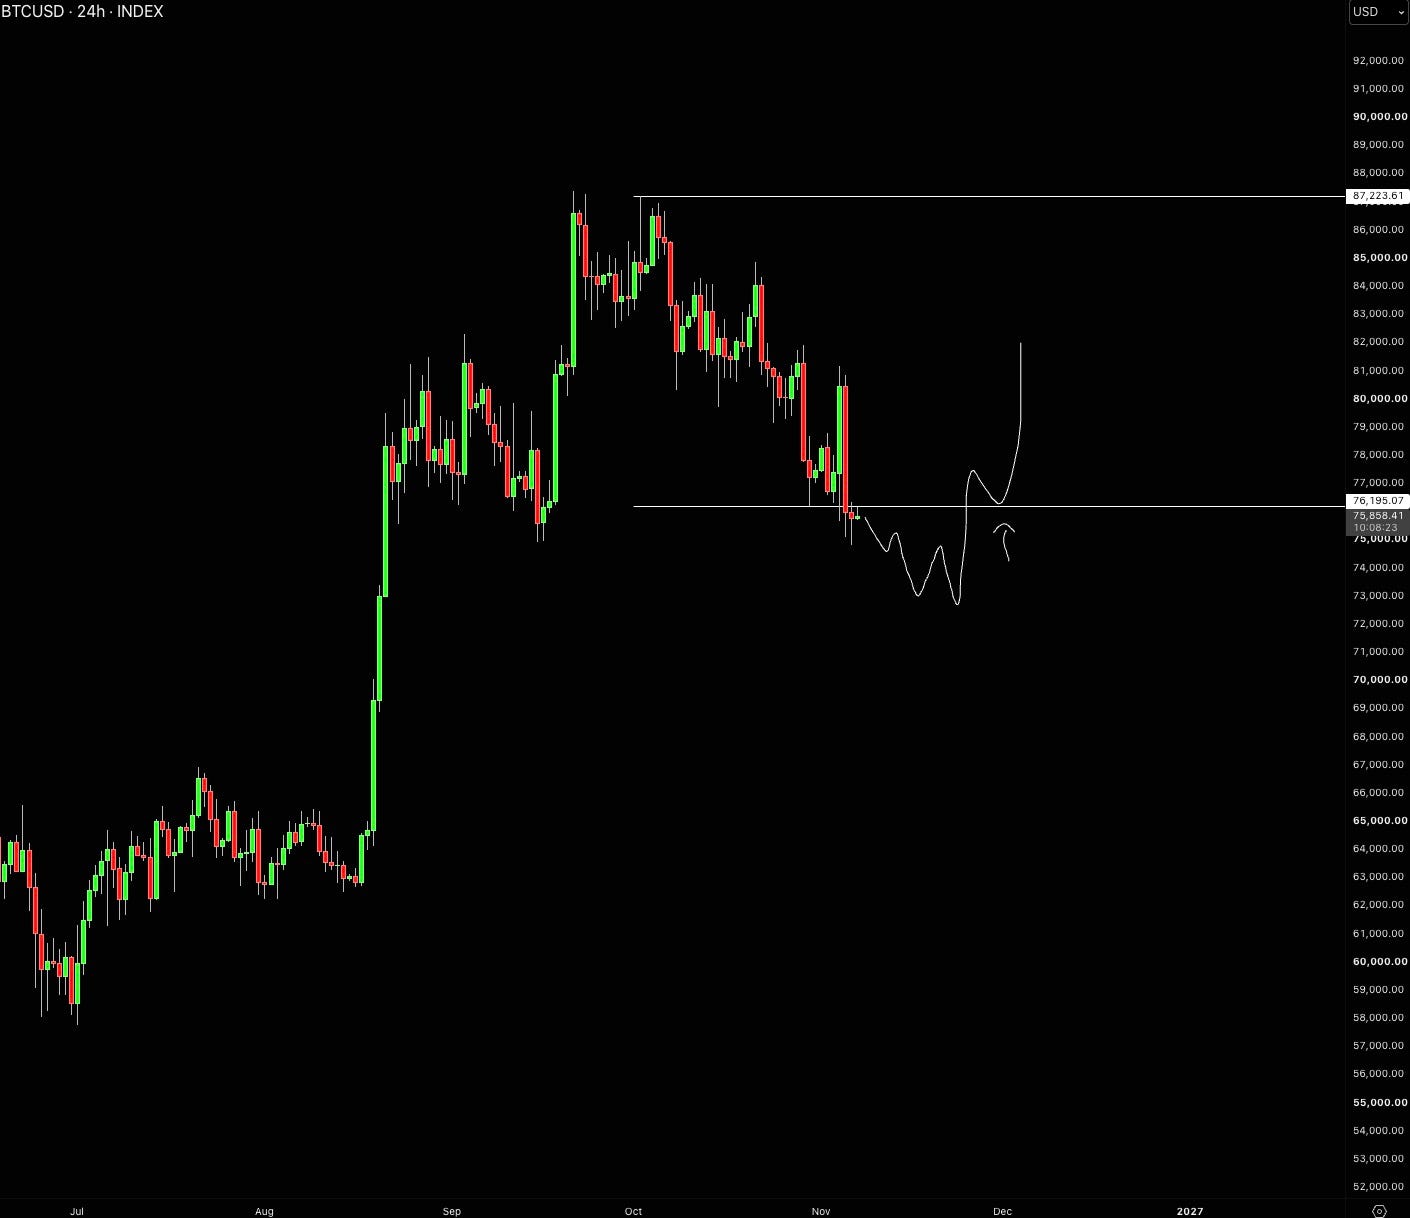
That being said, Bitcoin held pretty well. It was down about 2% while the Nasdaq lost 5%. Realized vol jumped hard, but implied vol barely moved and sits in the lower half of its year, so options didn’t chase the move.
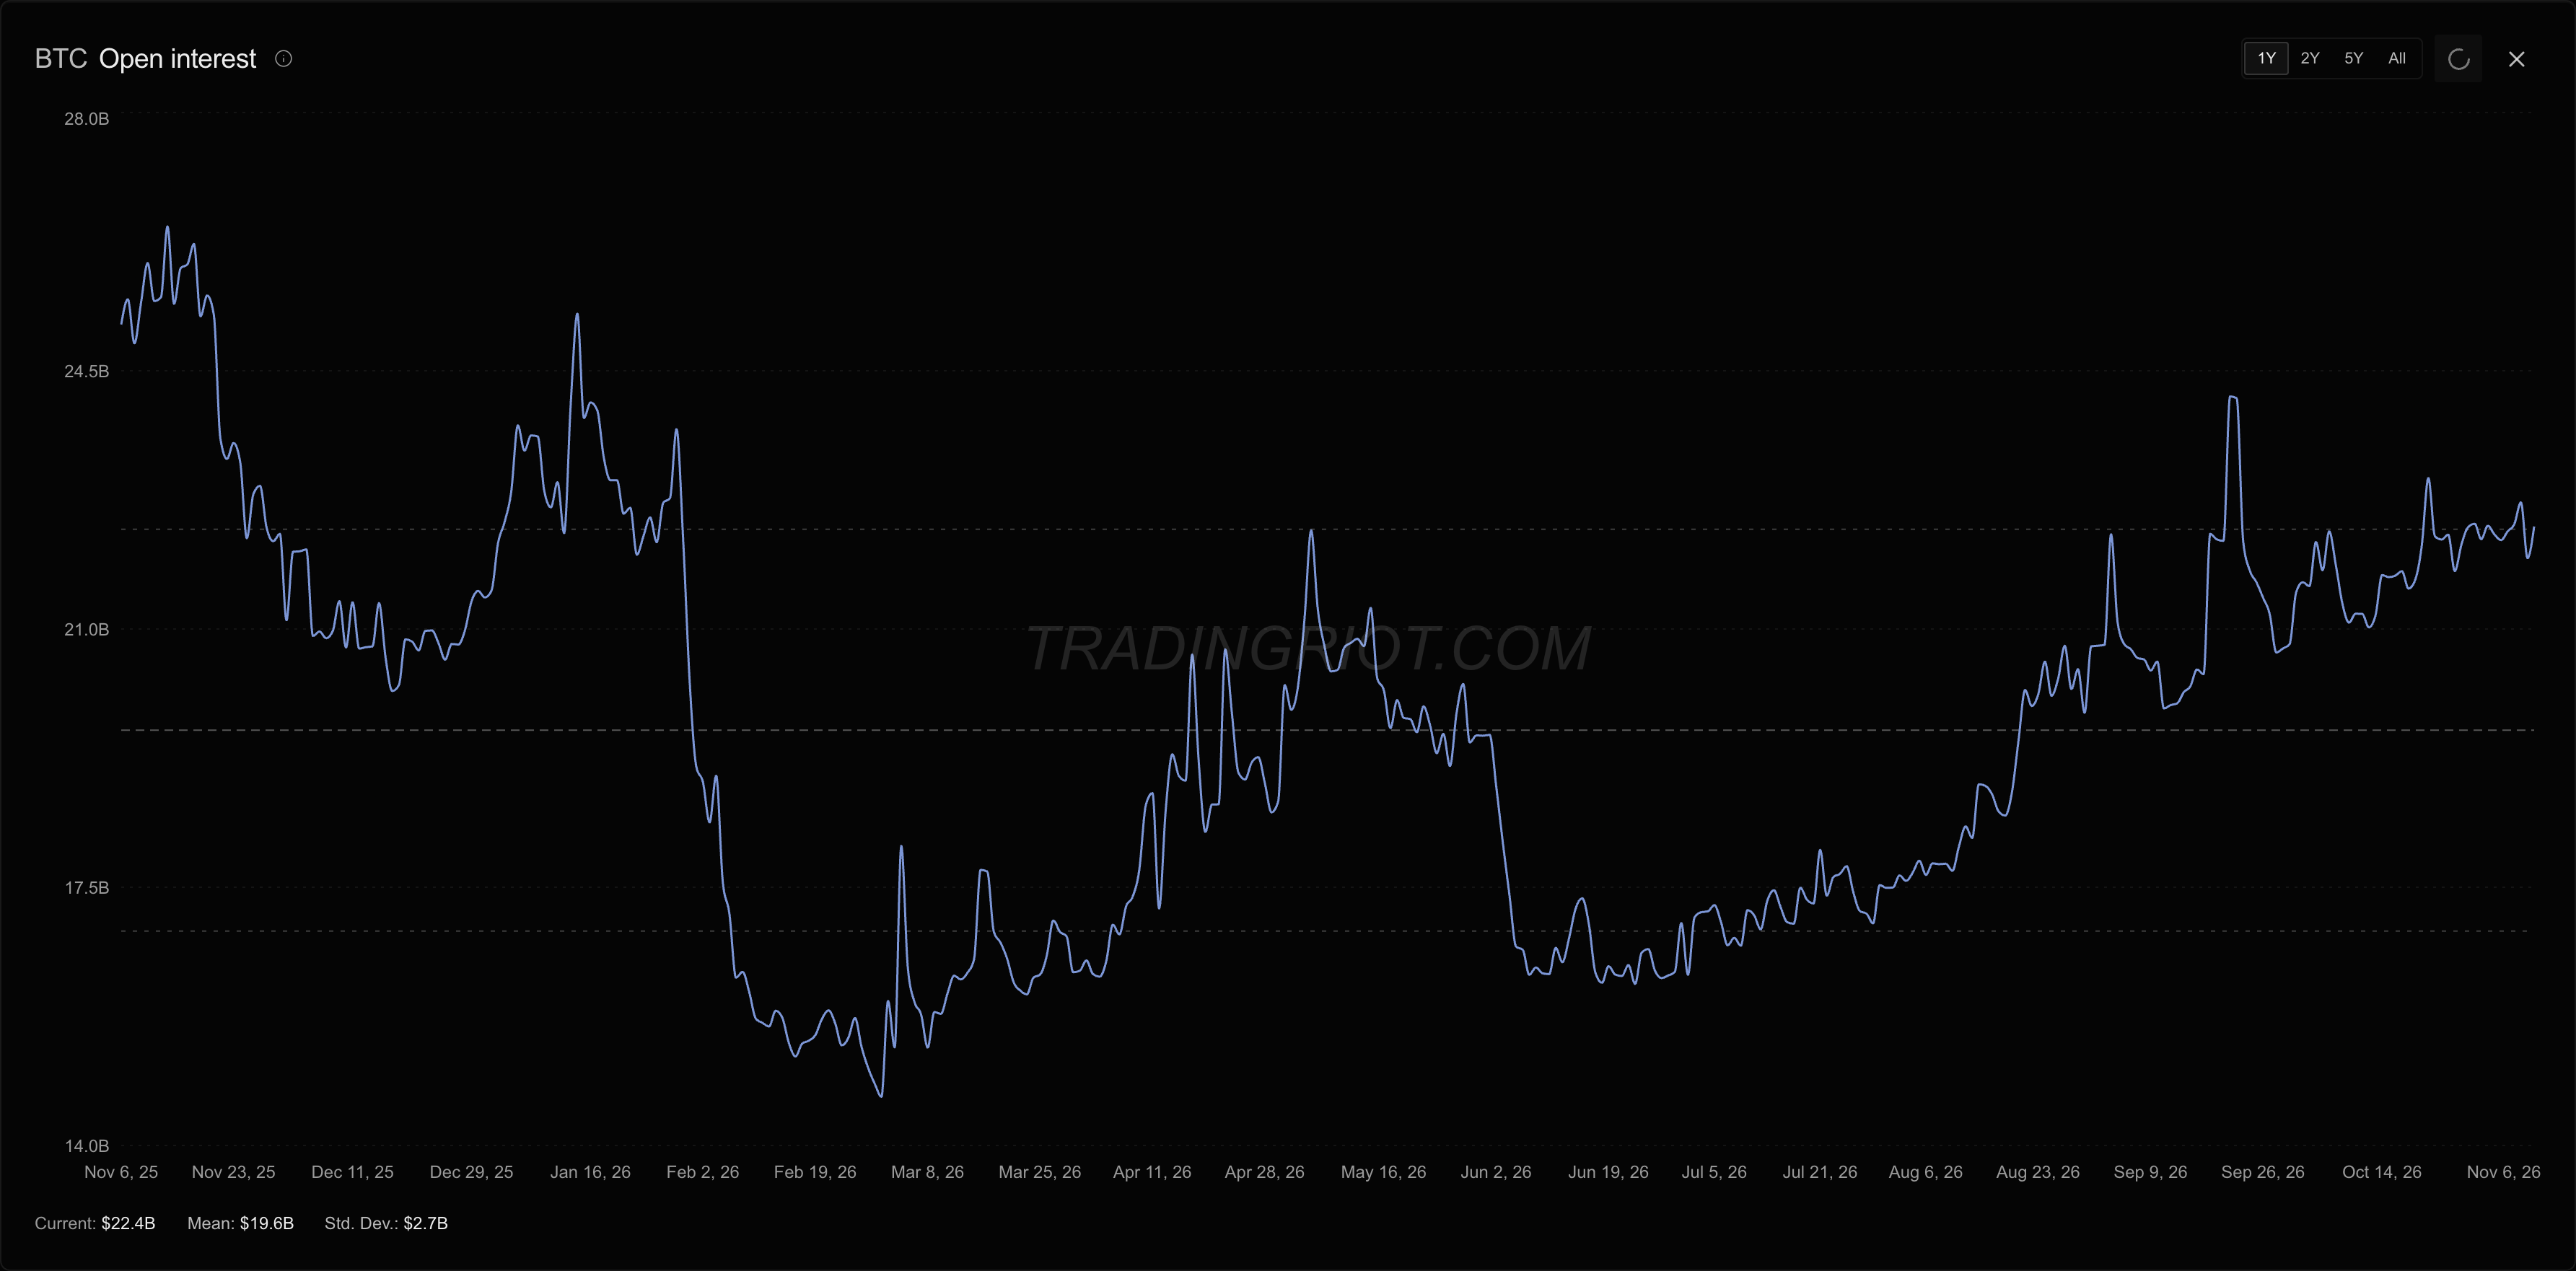
Perps are slightly worrisome for any long bias as funding is elevated and open interest is near the top of its year, and there has been no real flush.
We have tagged the level I spoke about last week, but I am not very eager to buy yet for any longer-term position. To get long, I would want to see price accepting back inside prior months’ range.
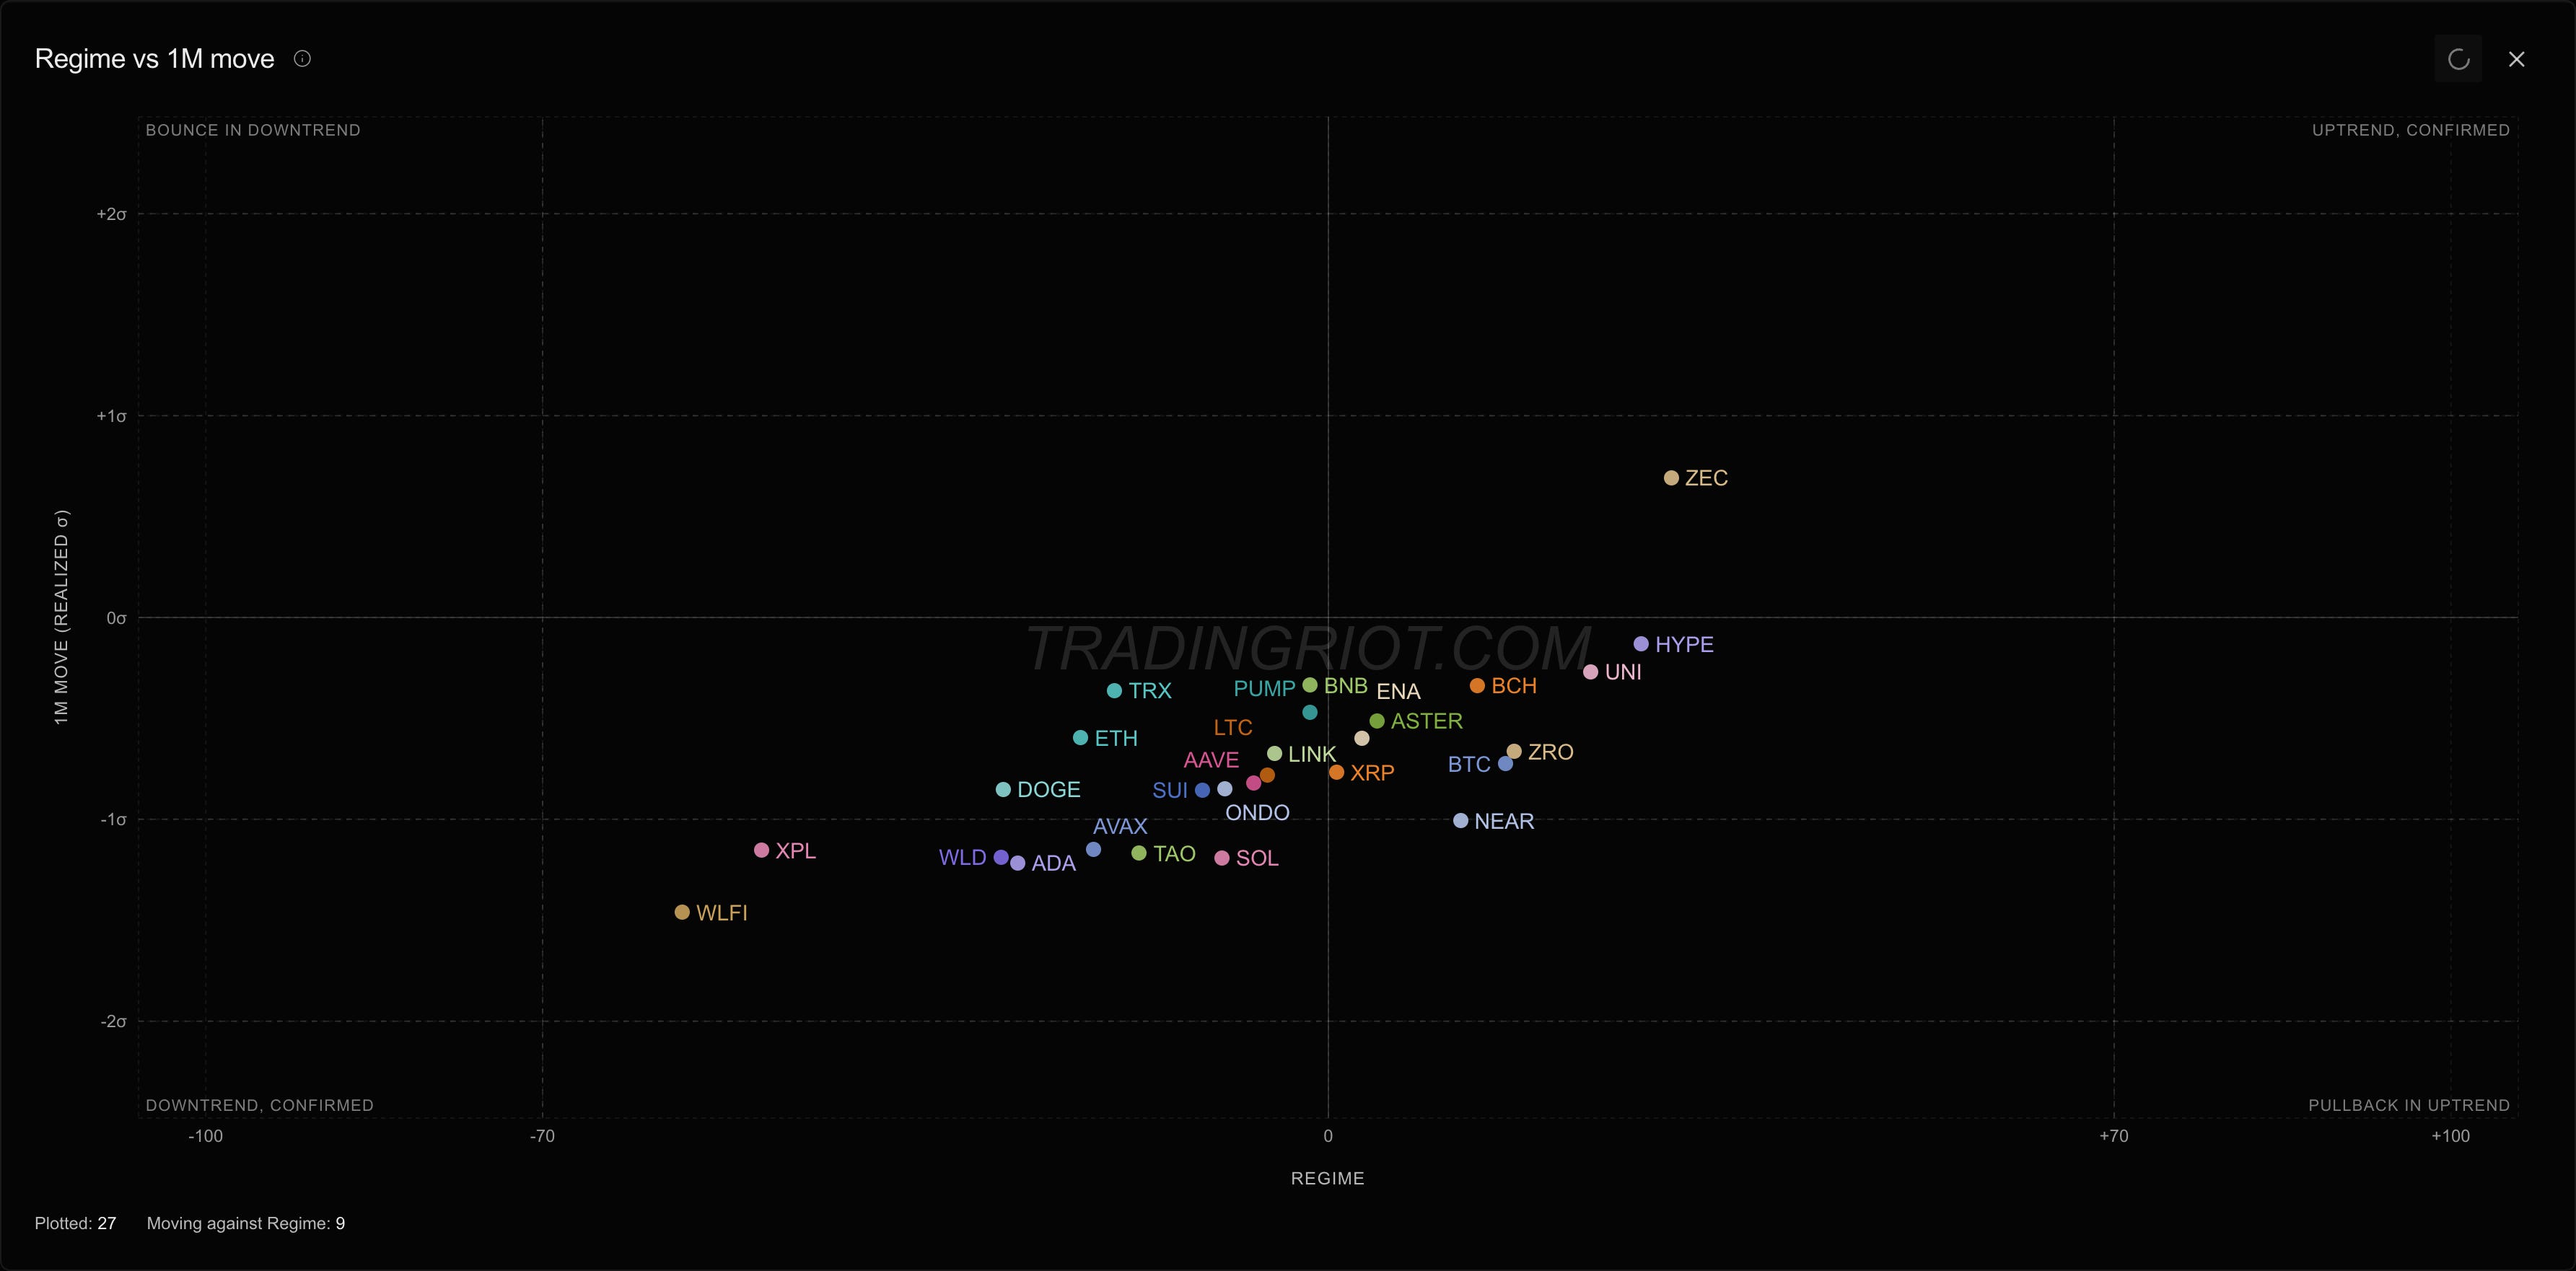
For altcoins, privacy is still the one narrative holding, with both Monero and ZEC holding well.
Futures
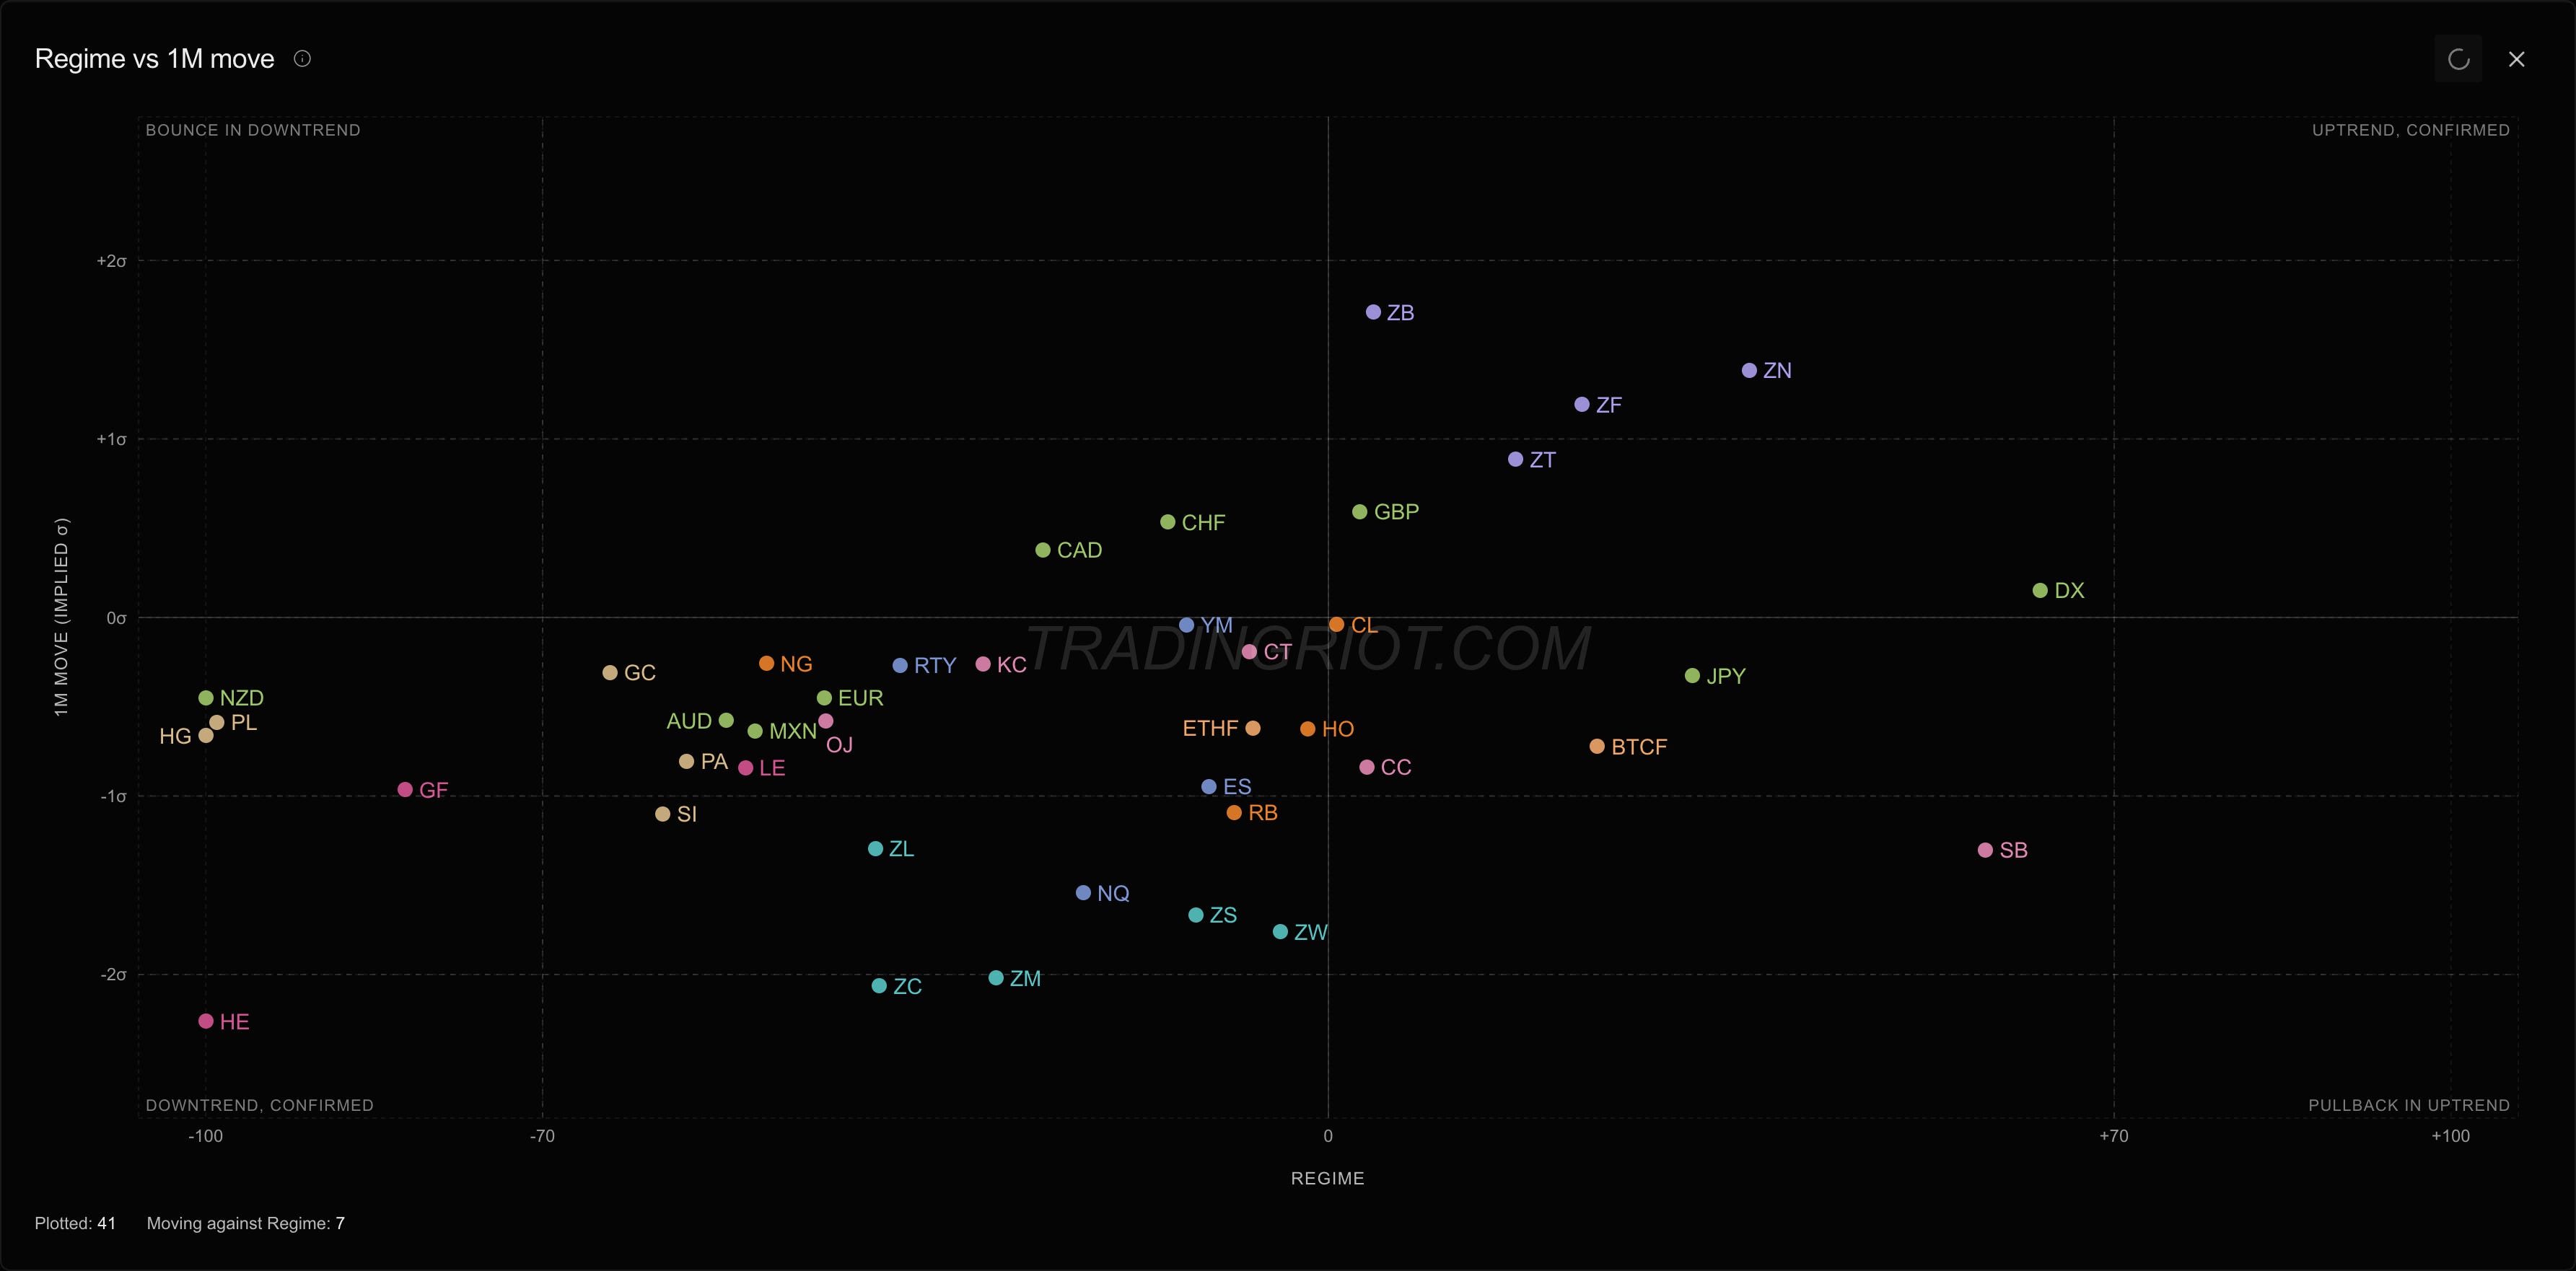
Copper didn’t lead the mean reversion I was looking for last week. It went the other way, dropping almost 4% on fears of an AI backlash; other metals held well, and I picked up some positions in gold, which bounced from level I showed.
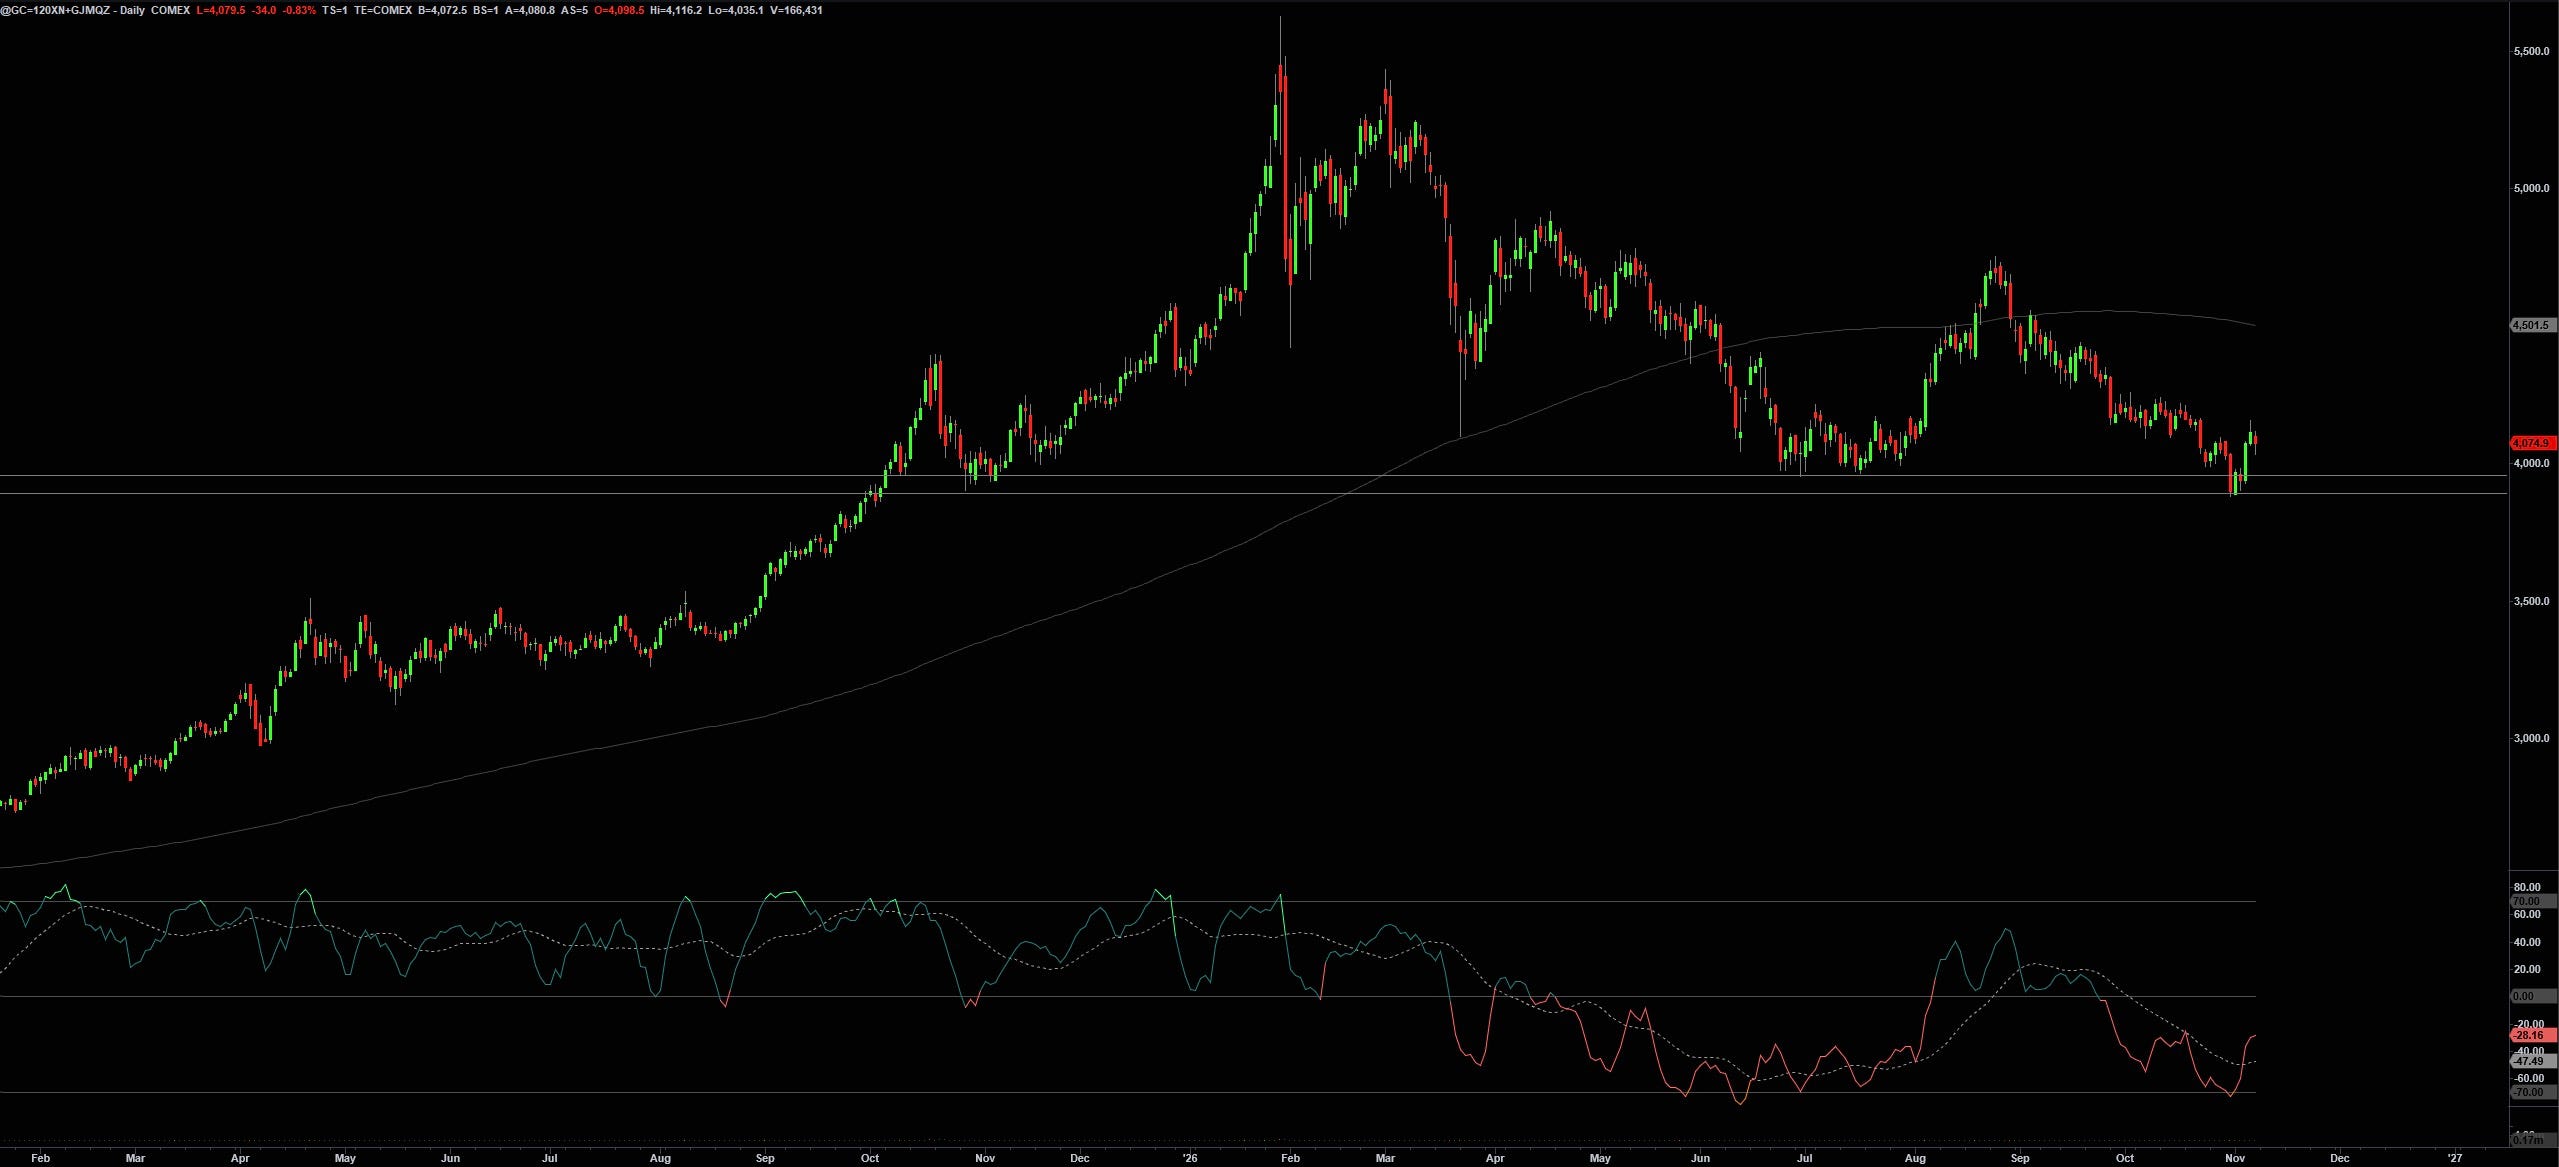
Both gold and silver rallied about 5% this week as yields fell after the election, while their regimes still sit near the bottom of their years, so price could push higher or at least stabilize around here.
At the other end, the dollar has the strongest regime on the board, and Treasuries are near the top of their years too, with a call skew bid across the curve. But I don’t feel like fading any of these yet.
The regime in SPX tracks the relationship between momentum, VIX, credit spreads, and breadth.